📄 Exam Questions & Readable Text Transcript
Full OCR-extracted text of questions, syllabus codes, and exam instructions.
Extracted Content: 6001q1specimen paper
Page 1
Extracted Text
Surname Forename(s) Centre Number Candidate NumberFor Performance Measurement
ZIMBABWE SCHOOL EXAMINATIONS COUNCIL
General Certificate of Education Advanced Level
ACCOUNTING 6001/1
PAPER 1 Multiple Choice
1 hour 20 minutes
Additional materials:
Multiple Choice answer sheet
Soft clean eraser
Soft pencil (type B or HB is recommended)
TIME 1 hour 20 minutes
INSTRUCTIONS TO CANDIDATES
Do not open this booklet until you are told to do so.
Write your name, centre number and candidate number on the answer sheet in the spaces
provided unless this has already been done for you.
There are forty questions in this paper. Answer all questions. For each question there are
four possible answers, A, B,C and D. Choose the one you consider correct and record your
choice in soft pencil on the separate answer sheet.
Read very carefully the instructions on the answer sheet.
INFORMATION FOR CANDIDATES
Each correct answer will score onemark. A mark will not be deducted for a wrong answer.
Any rough working should be done in this booklet.
Calculators may be used.
The businesses in this question paper are intended to be fictitious.
This question paper consists of 11 printed pages and 1 blank page.
Copyright: Zimbabwe School Examinations Council, Specimen Paper.
\ ©ZIMSEC Specimen Paper [Turn over }
---
Page 2
Extracted Text
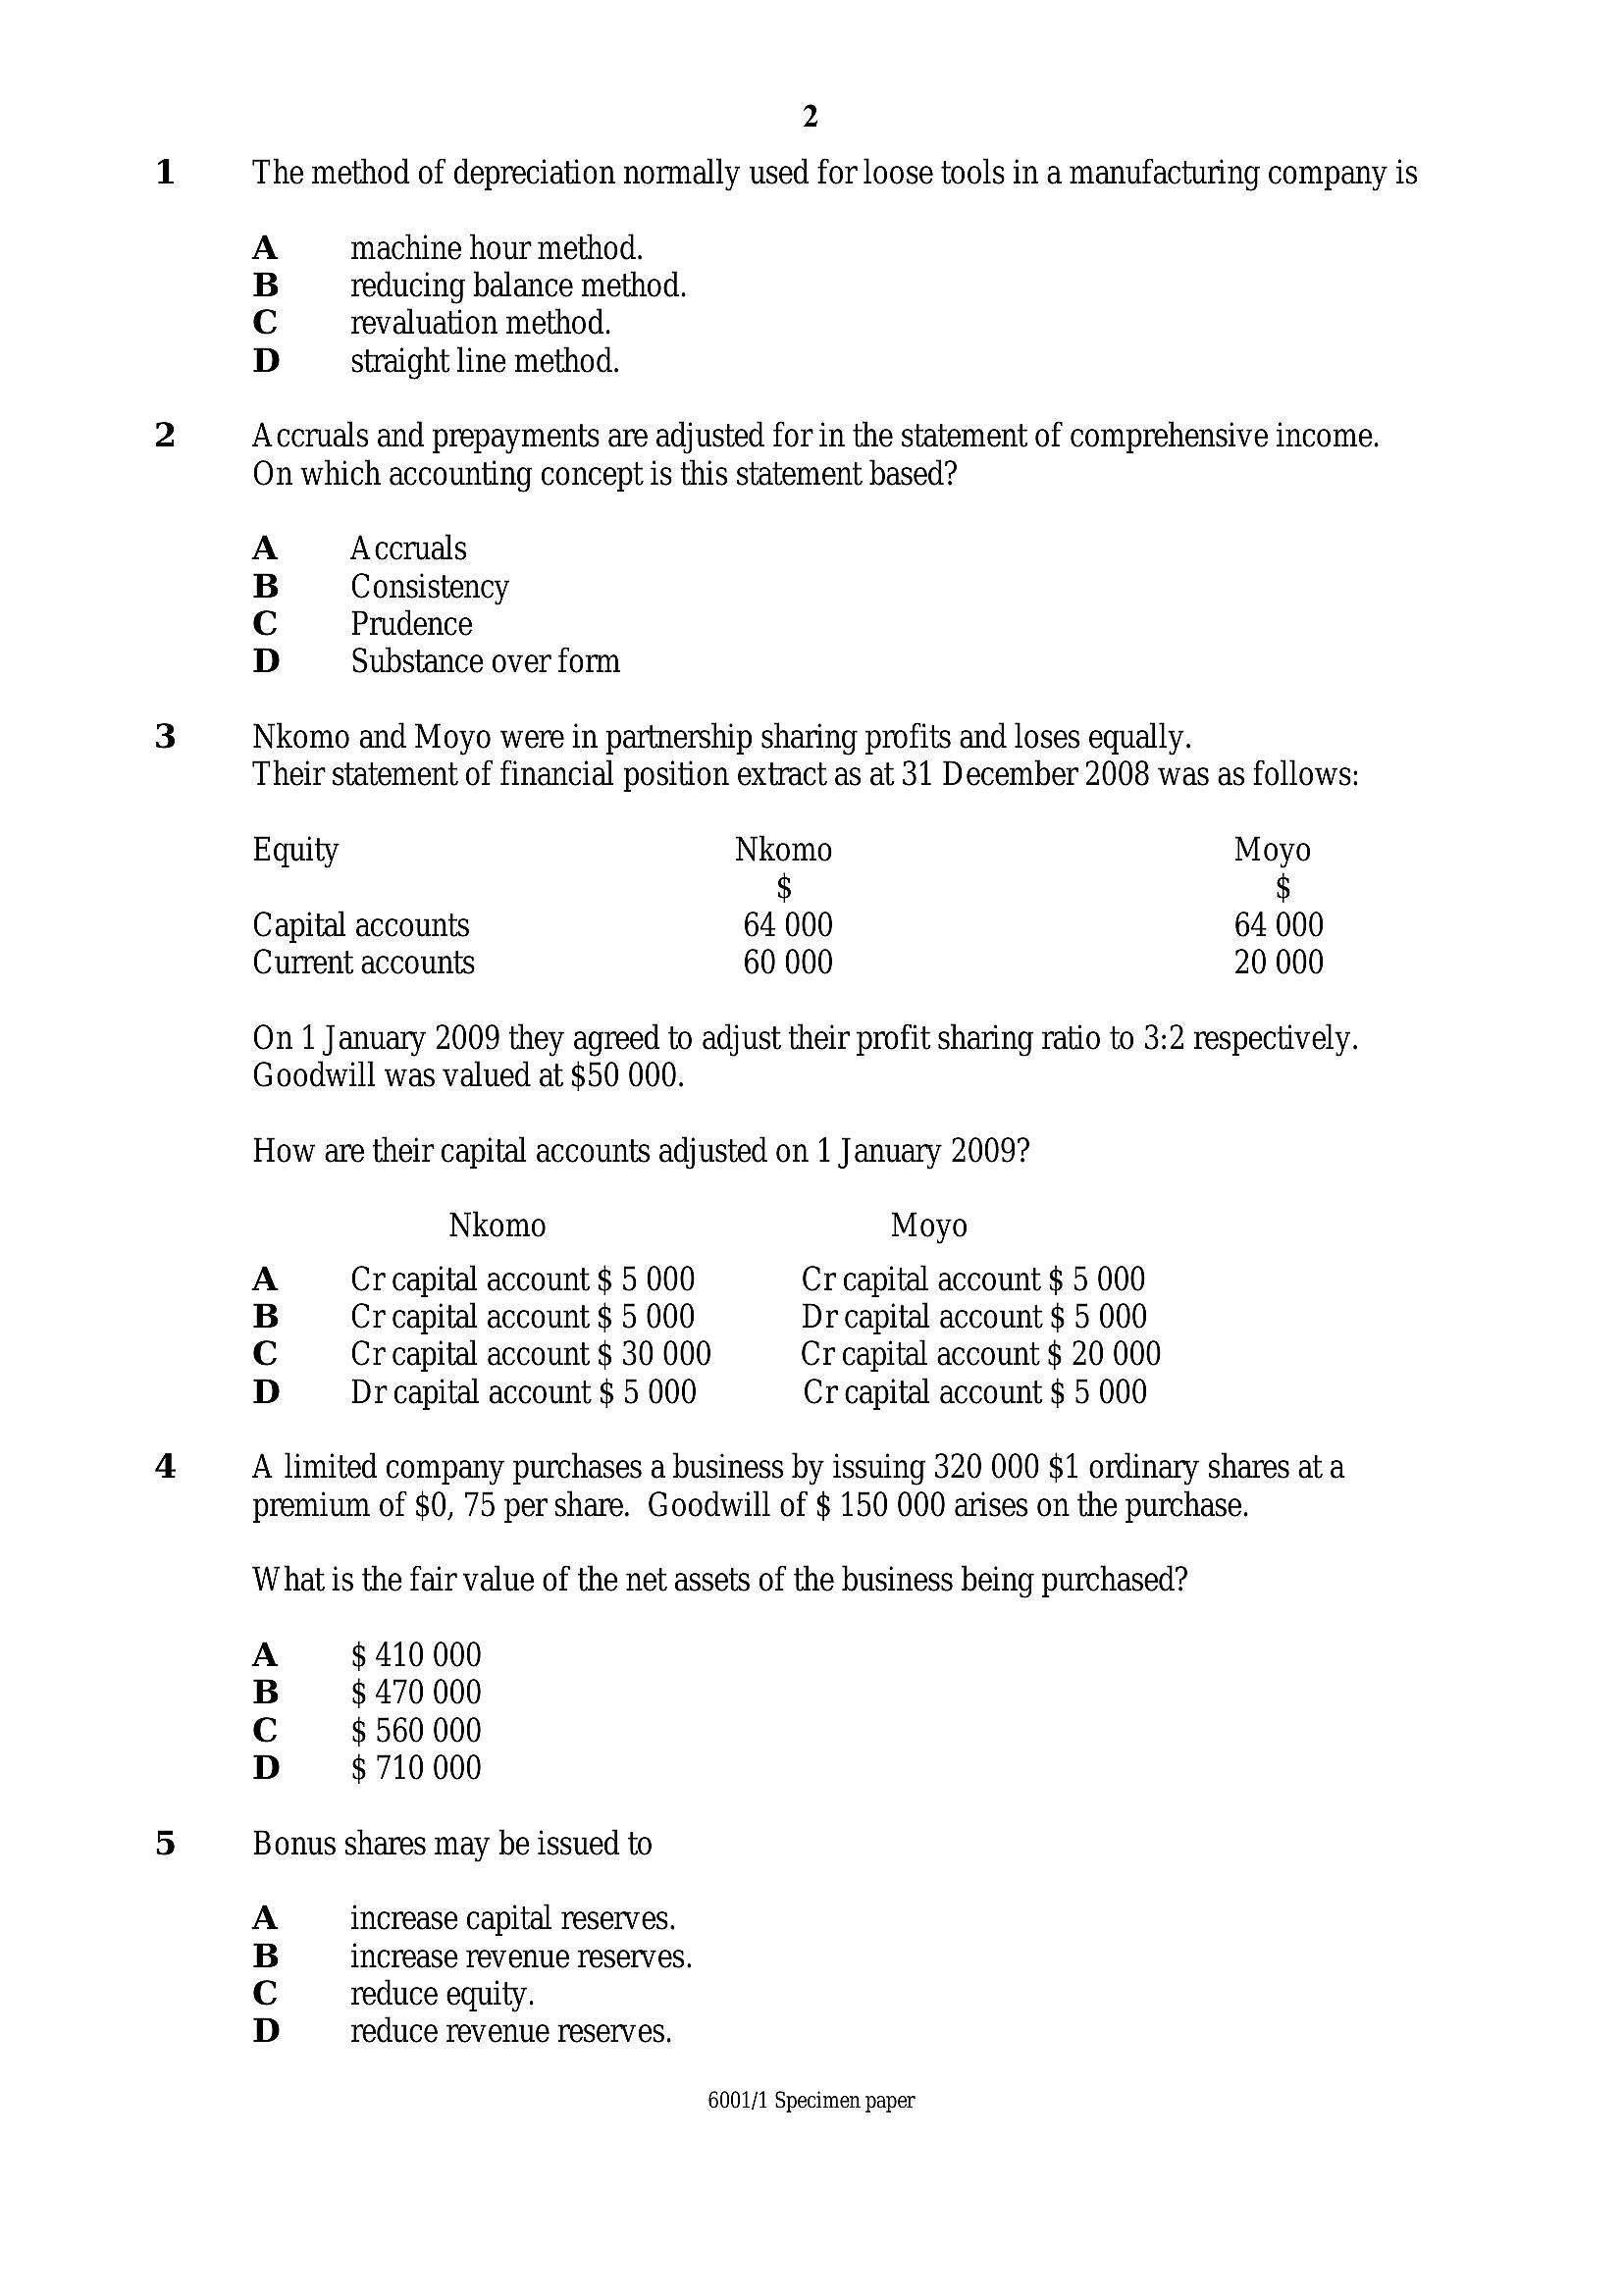
2The method of depreciation normally used for loose tools in a manufacturing company is
A machine hour method.
B reducing balance method.
Cc revaluation method.
D straight line method.
Accruals and prepayments are adjusted for in the statement of comprehensive income.
On which accounting concept is this statement based?
A Accruals
B Consistency
Cc Prudence
D Substance over form
Nkomo and Moyo were in partnership sharing profits and loses equally.
Their statement of financial position extract as at 31 December 2008 was as follows:
Equity Nkomo Moyo
$ $
Capital accounts 64 000 64 000
Current accounts 60 000 20 000
On 1 January 2009 they agreed to adjust their profit sharing ratio to 3:2 respectively.
Goodwill was valued at $50 000.
How are their capital accounts adjusted on 1 January 2009?
Nkomo Moyo
A Cr capital account $ 5 000 Cr capital account $ 5 000
B Cr capital account $ 5 000 Dr capital account $ 5 000
Cc Cr capital account $ 30 000 Cr capital account $ 20 000
D Dr capital account $ 5 000 Cr capital account $ 5 000
A limited company purchases a business by issuing 320 000 $1 ordinary shares at a
premium of $0, 75 per share. Goodwill of $ 150 000 arises on the purchase.
What is the fair value of the net assets of the business being purchased?
A $ 410 000
B $ 470 000
Cc $ 560 000
D $ 710 000
Bonus shares may be issued to
A increase capital reserves.
B increase revenue reserves.
Cc reduce equity.
D reduce revenue reserves.
6001/1 Specimen paper
---
Page 3
Extracted Text
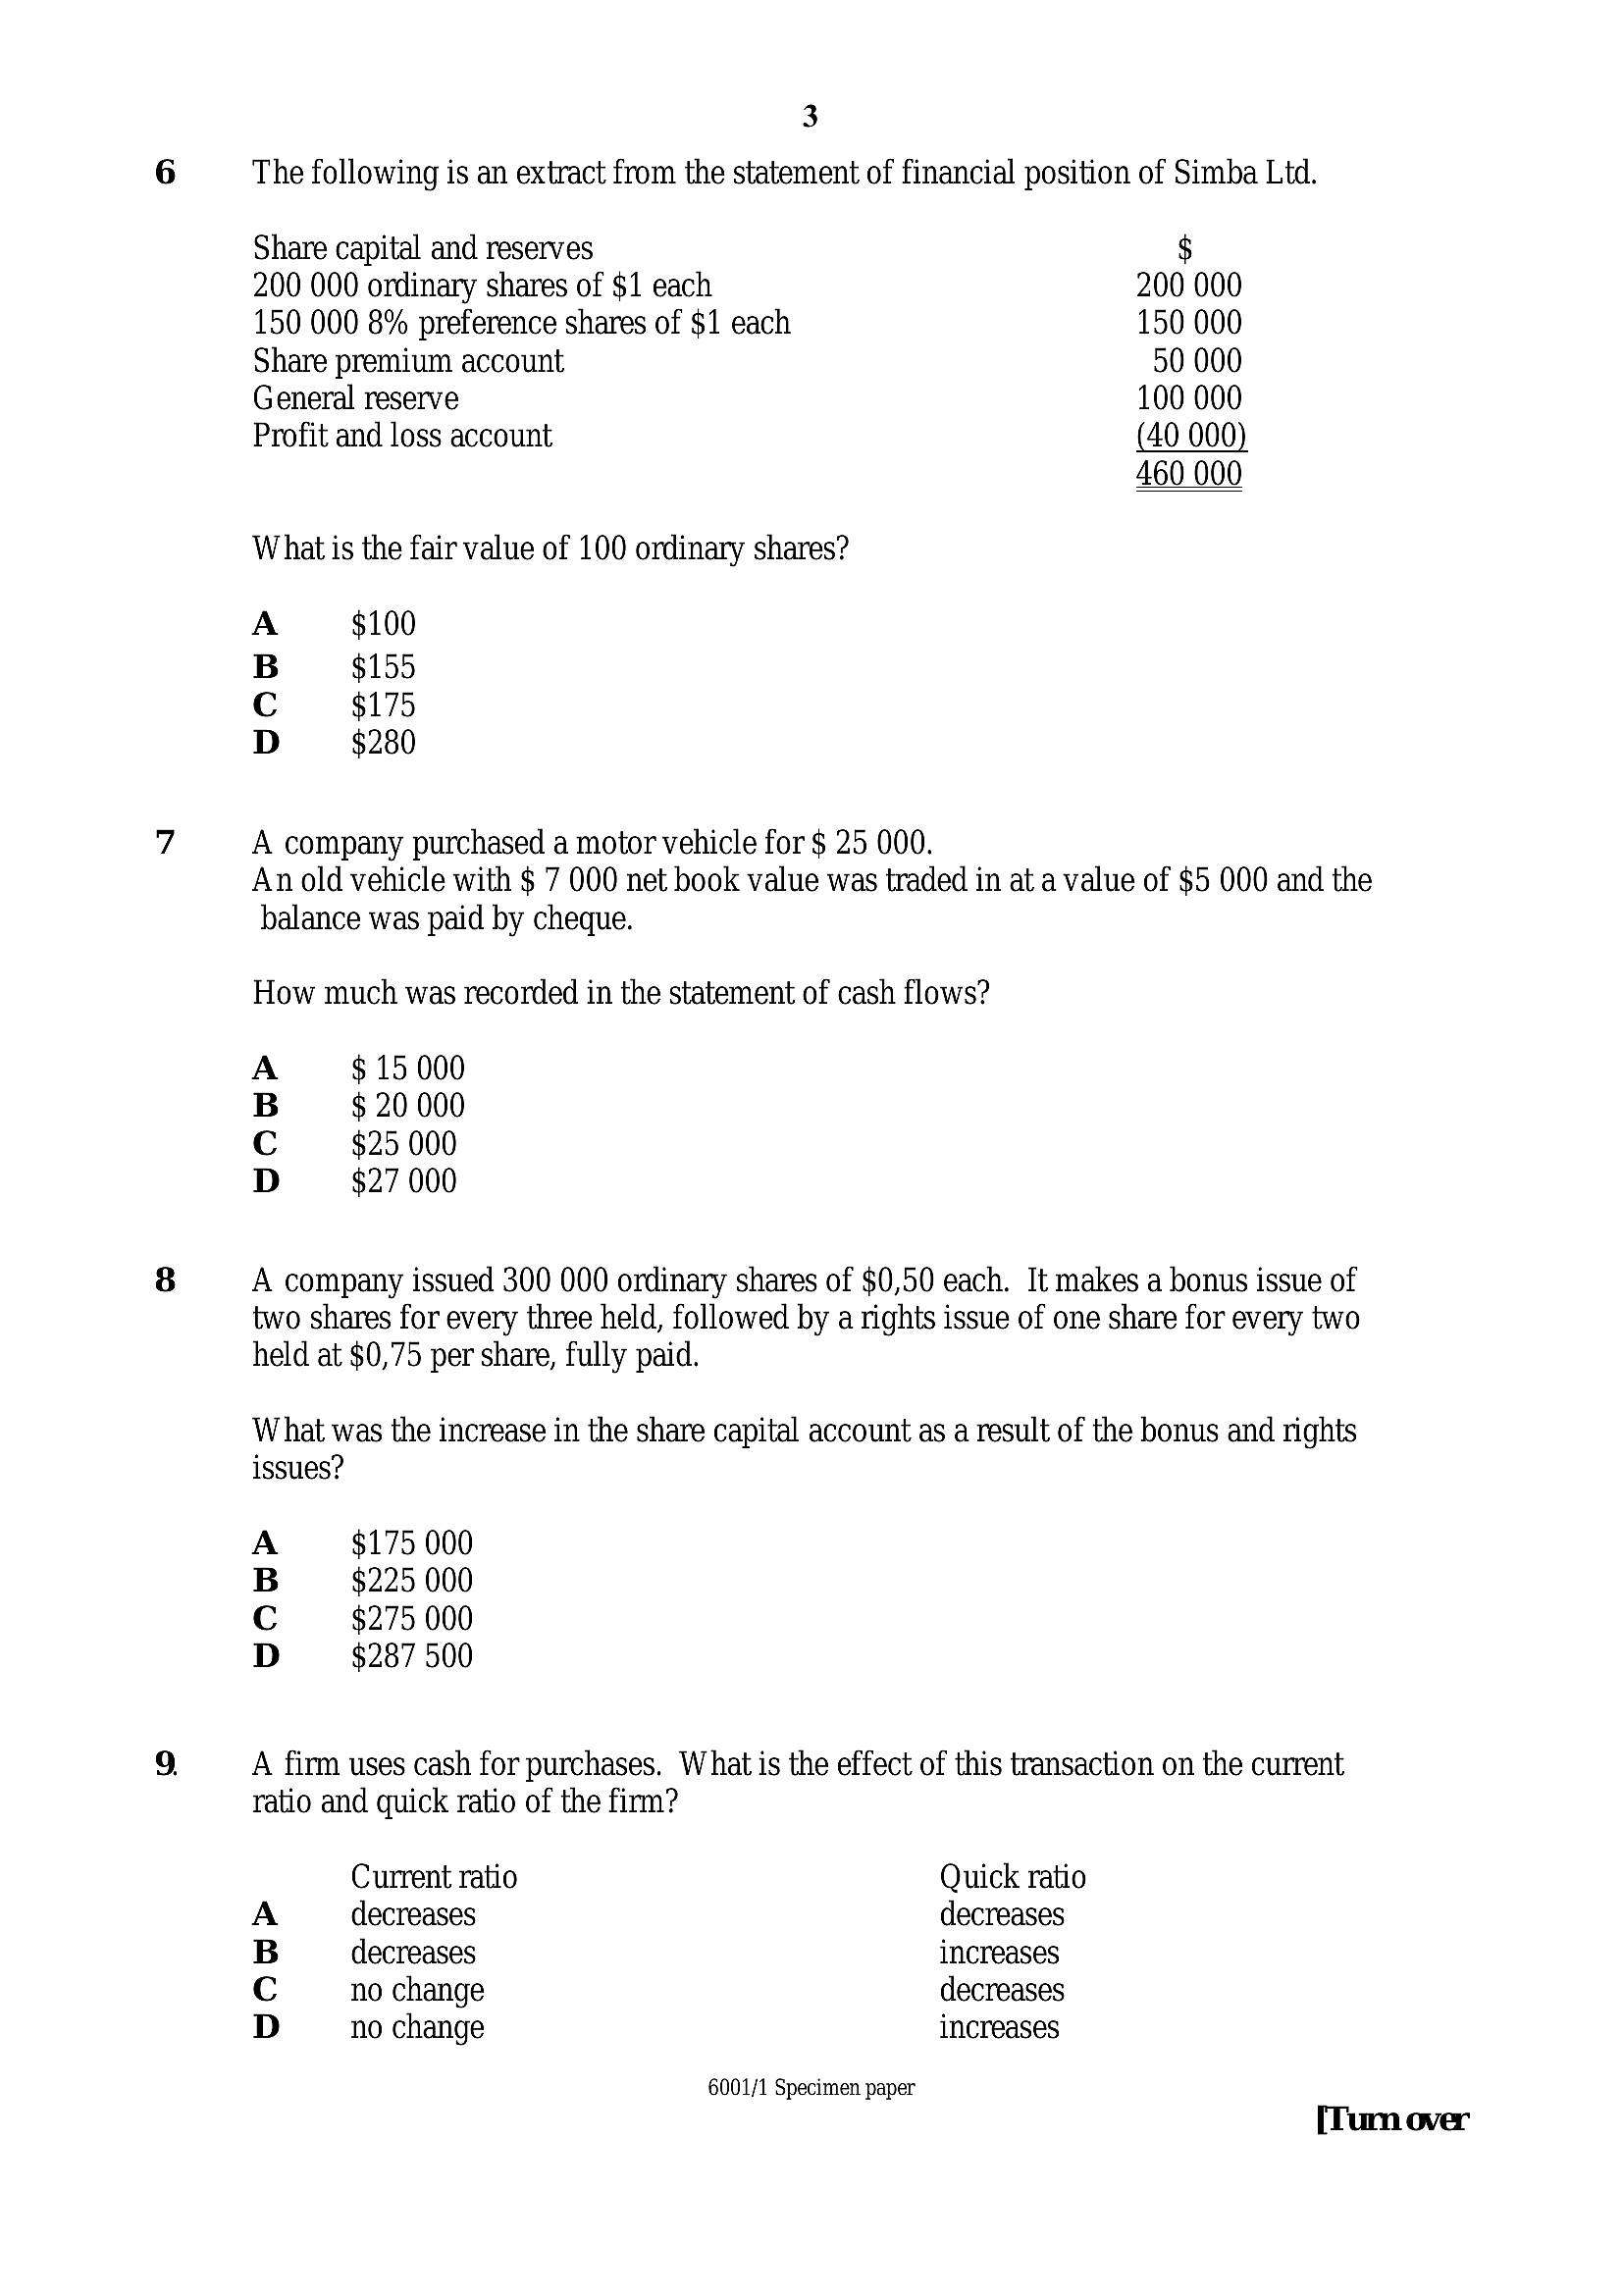
3The following is an extract from the statement of financial position of Simba Ltd.
Share capital and reserves $
200 000 ordinary shares of $1 each 200 000
150 000 8% preference shares of $1 each 150 000
Share premium account 50 000
General reserve 100 000
Profit and loss account (40 000)
460 000
What is the fair value of 100 ordinary shares?
A $100
B $155
Cc $175
D $280
A company purchased a motor vehicle for $ 25 000.
An old vehicle with $ 7 000 net book value was traded in at a value of $5 000 and the
balance was paid by cheque.
How much was recorded in the statement of cash flows?
A $ 15 000
B $ 20 000
Cc $25 000
D $27 000
A company issued 300 000 ordinary shares of $0,50 each. It makes a bonus issue of
two shares for every three held, followed by a rights issue of one share for every two
held at $0,75 per share, fully paid.
What was the increase in the share capital account as a result of the bonus and rights
issues?
A $175 000
B $225 000
Cc $275 000
D $287 500
A firm uses cash for purchases. W hat is the effect of this transaction on the current
ratio and quick ratio of the firm?
Current ratio Quick ratio
A decreases decreases
B decreases increases
Cc no change decreases
D no change increases
6001/1 Specimen paper
---
Page 4
Extracted Text
1011
4
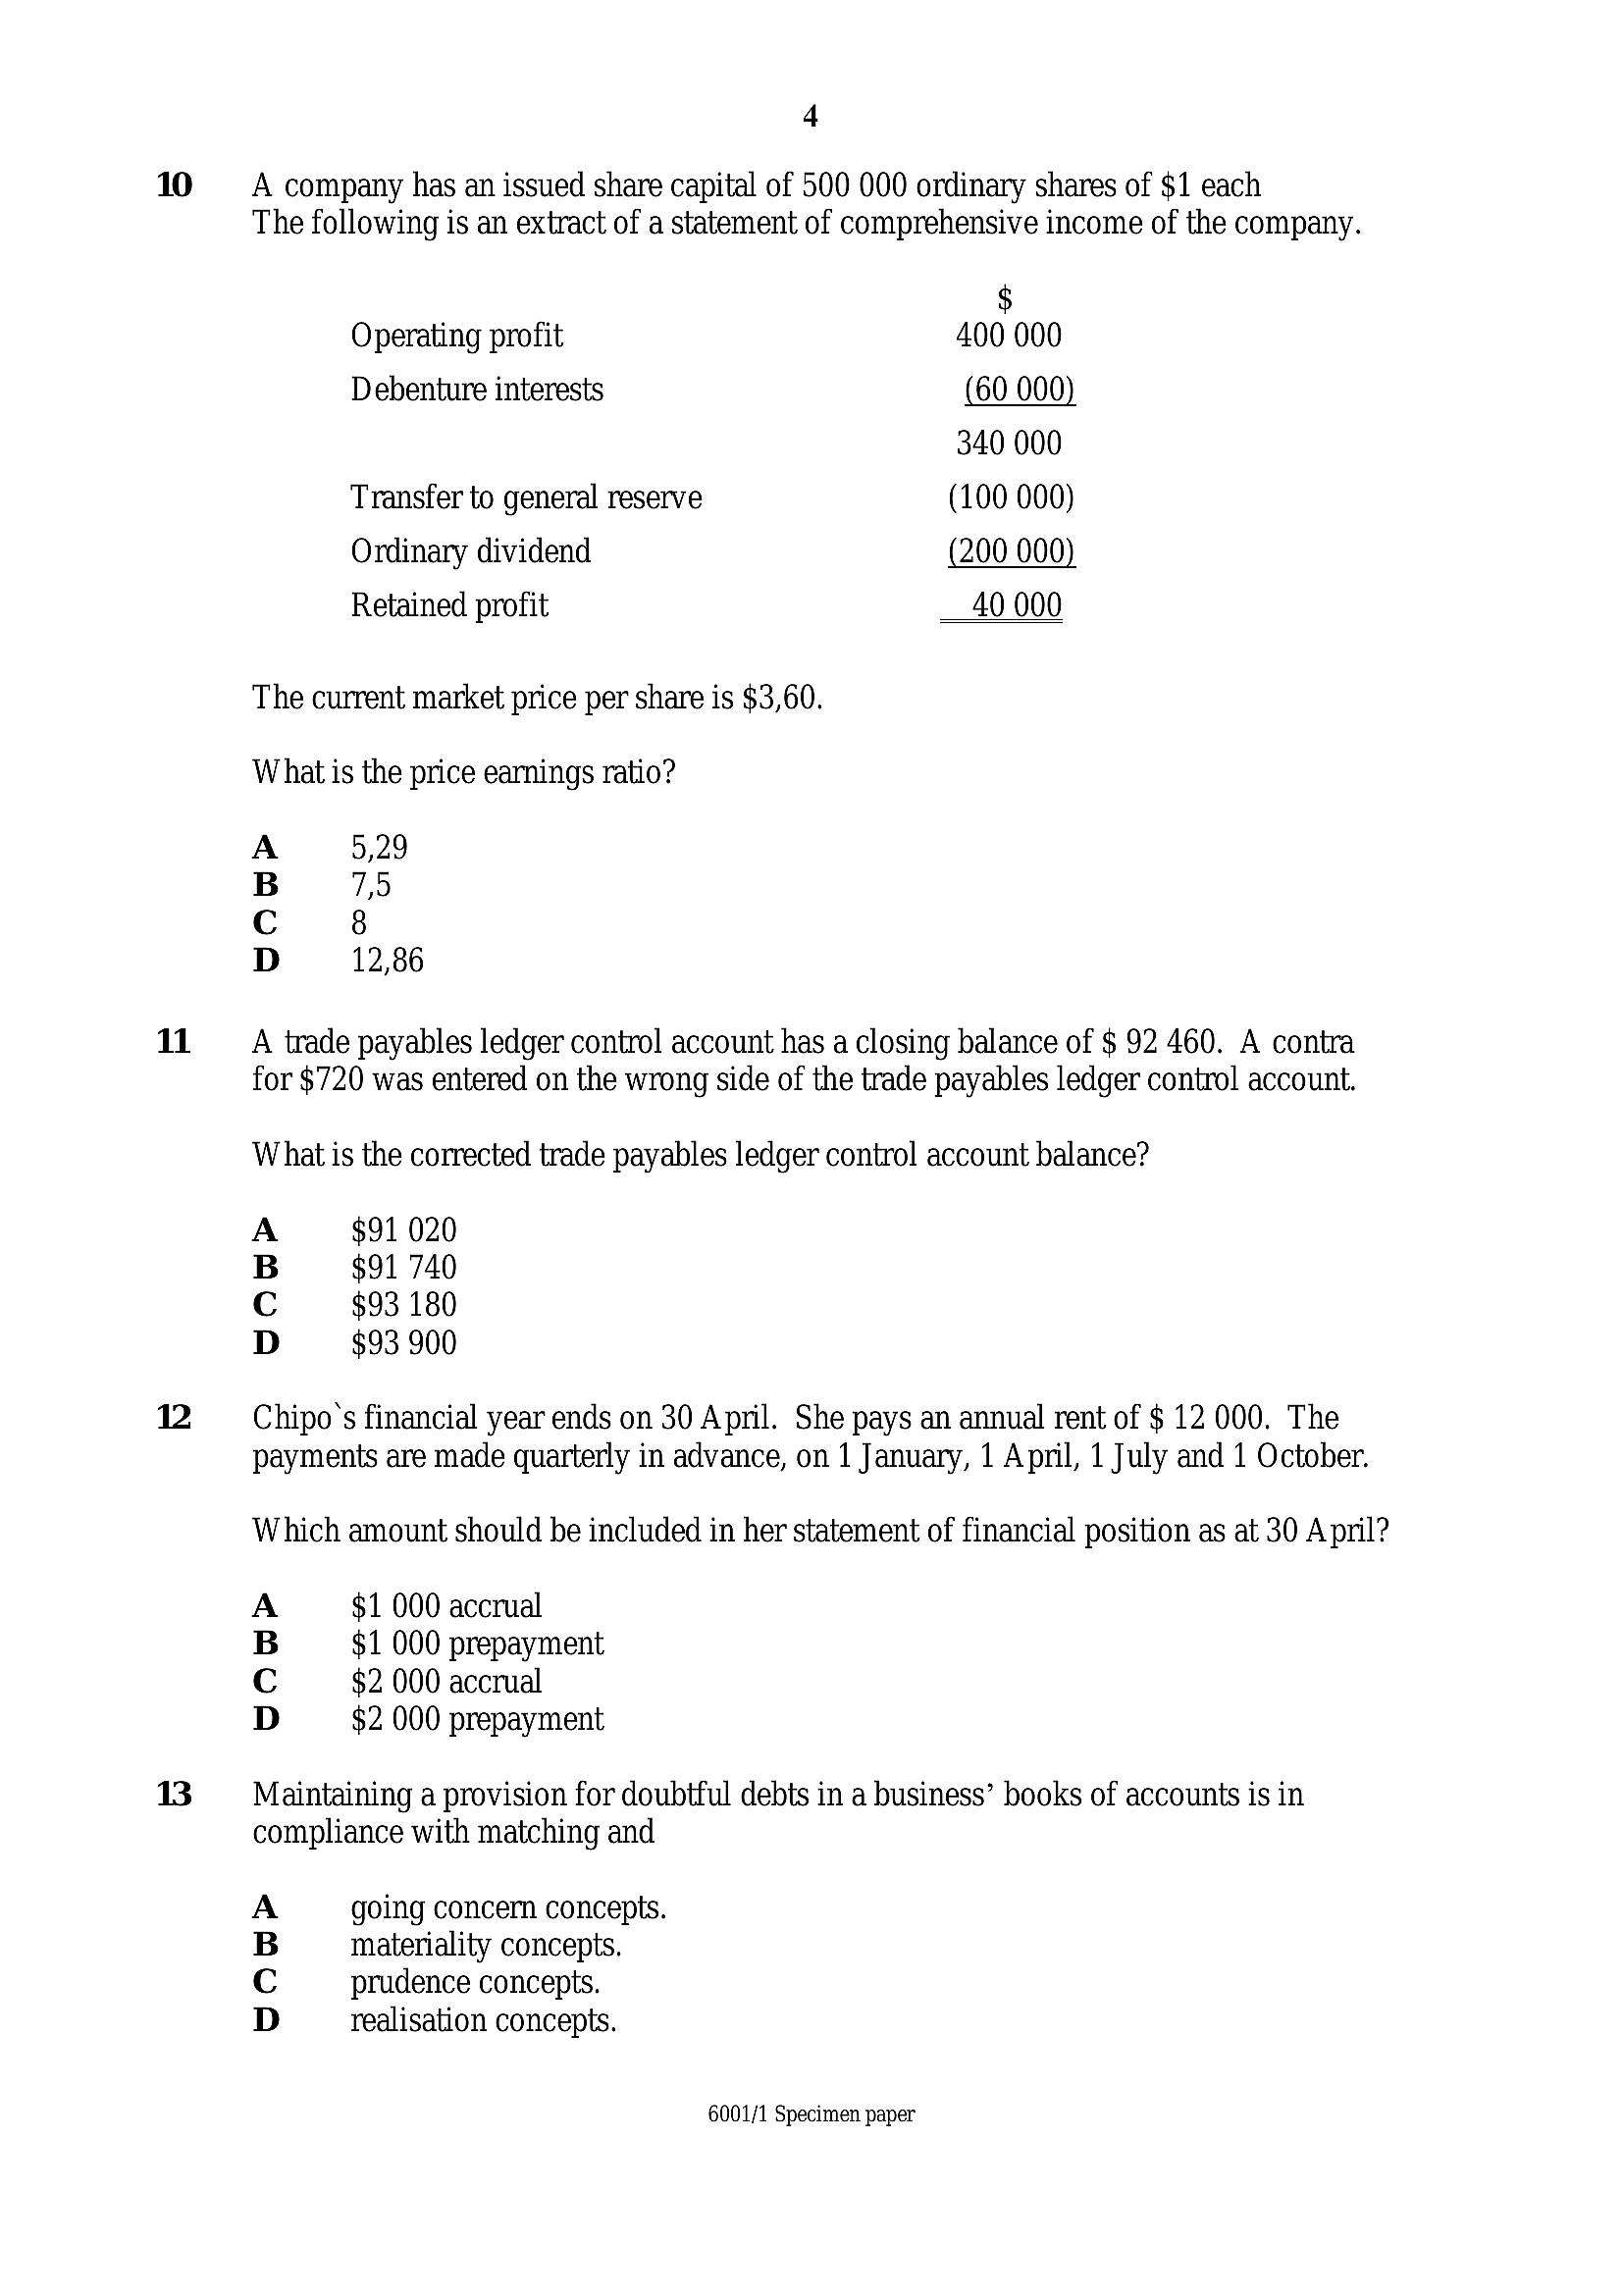
A company has an issued share capital of 500 000 ordinary shares of $1 each
The following is an extract of a statement of comprehensive income of the company.
Operating profit 400 000
Debenture interests (60 000)
340 000
Transfer to general reserve (100 000)
Ordinary dividend (200 000)
Retained profit 40 000
The current market price per share is $3,60.
What is the price earnings ratio?
A 5,29
B 7,5
Cc 8
D 12,86
A trade payables ledger control account has a closing balance of $ 92 460. A contra
for $720 was entered on the wrong side of the trade payables ledger control account.
What is the corrected trade payables ledger control account balance?
A $91 020
B $91 740
Cc $93 180
D $93 900
Chipo’s financial year ends on 30 April. She pays an annual rent of $ 12 000. The
payments are made quarterly in advance, on 1 January, 1 April, 1 July and 1 October.
Which amount should be included in her statement of financial position as at 30 April?
A $1 000 accrual
B $1 000 prepayment
Cc $2 000 accrual
D $2 000 prepayment
Maintaining a provision for doubtful debts in a business’ books of accounts is in
compliance with matching and
going concern concepts.
materiality concepts.
prudence concepts.
realisation concepts.
Soar
6001/1 Specimen paper
---
Page 5
Extracted Text
416
17
5
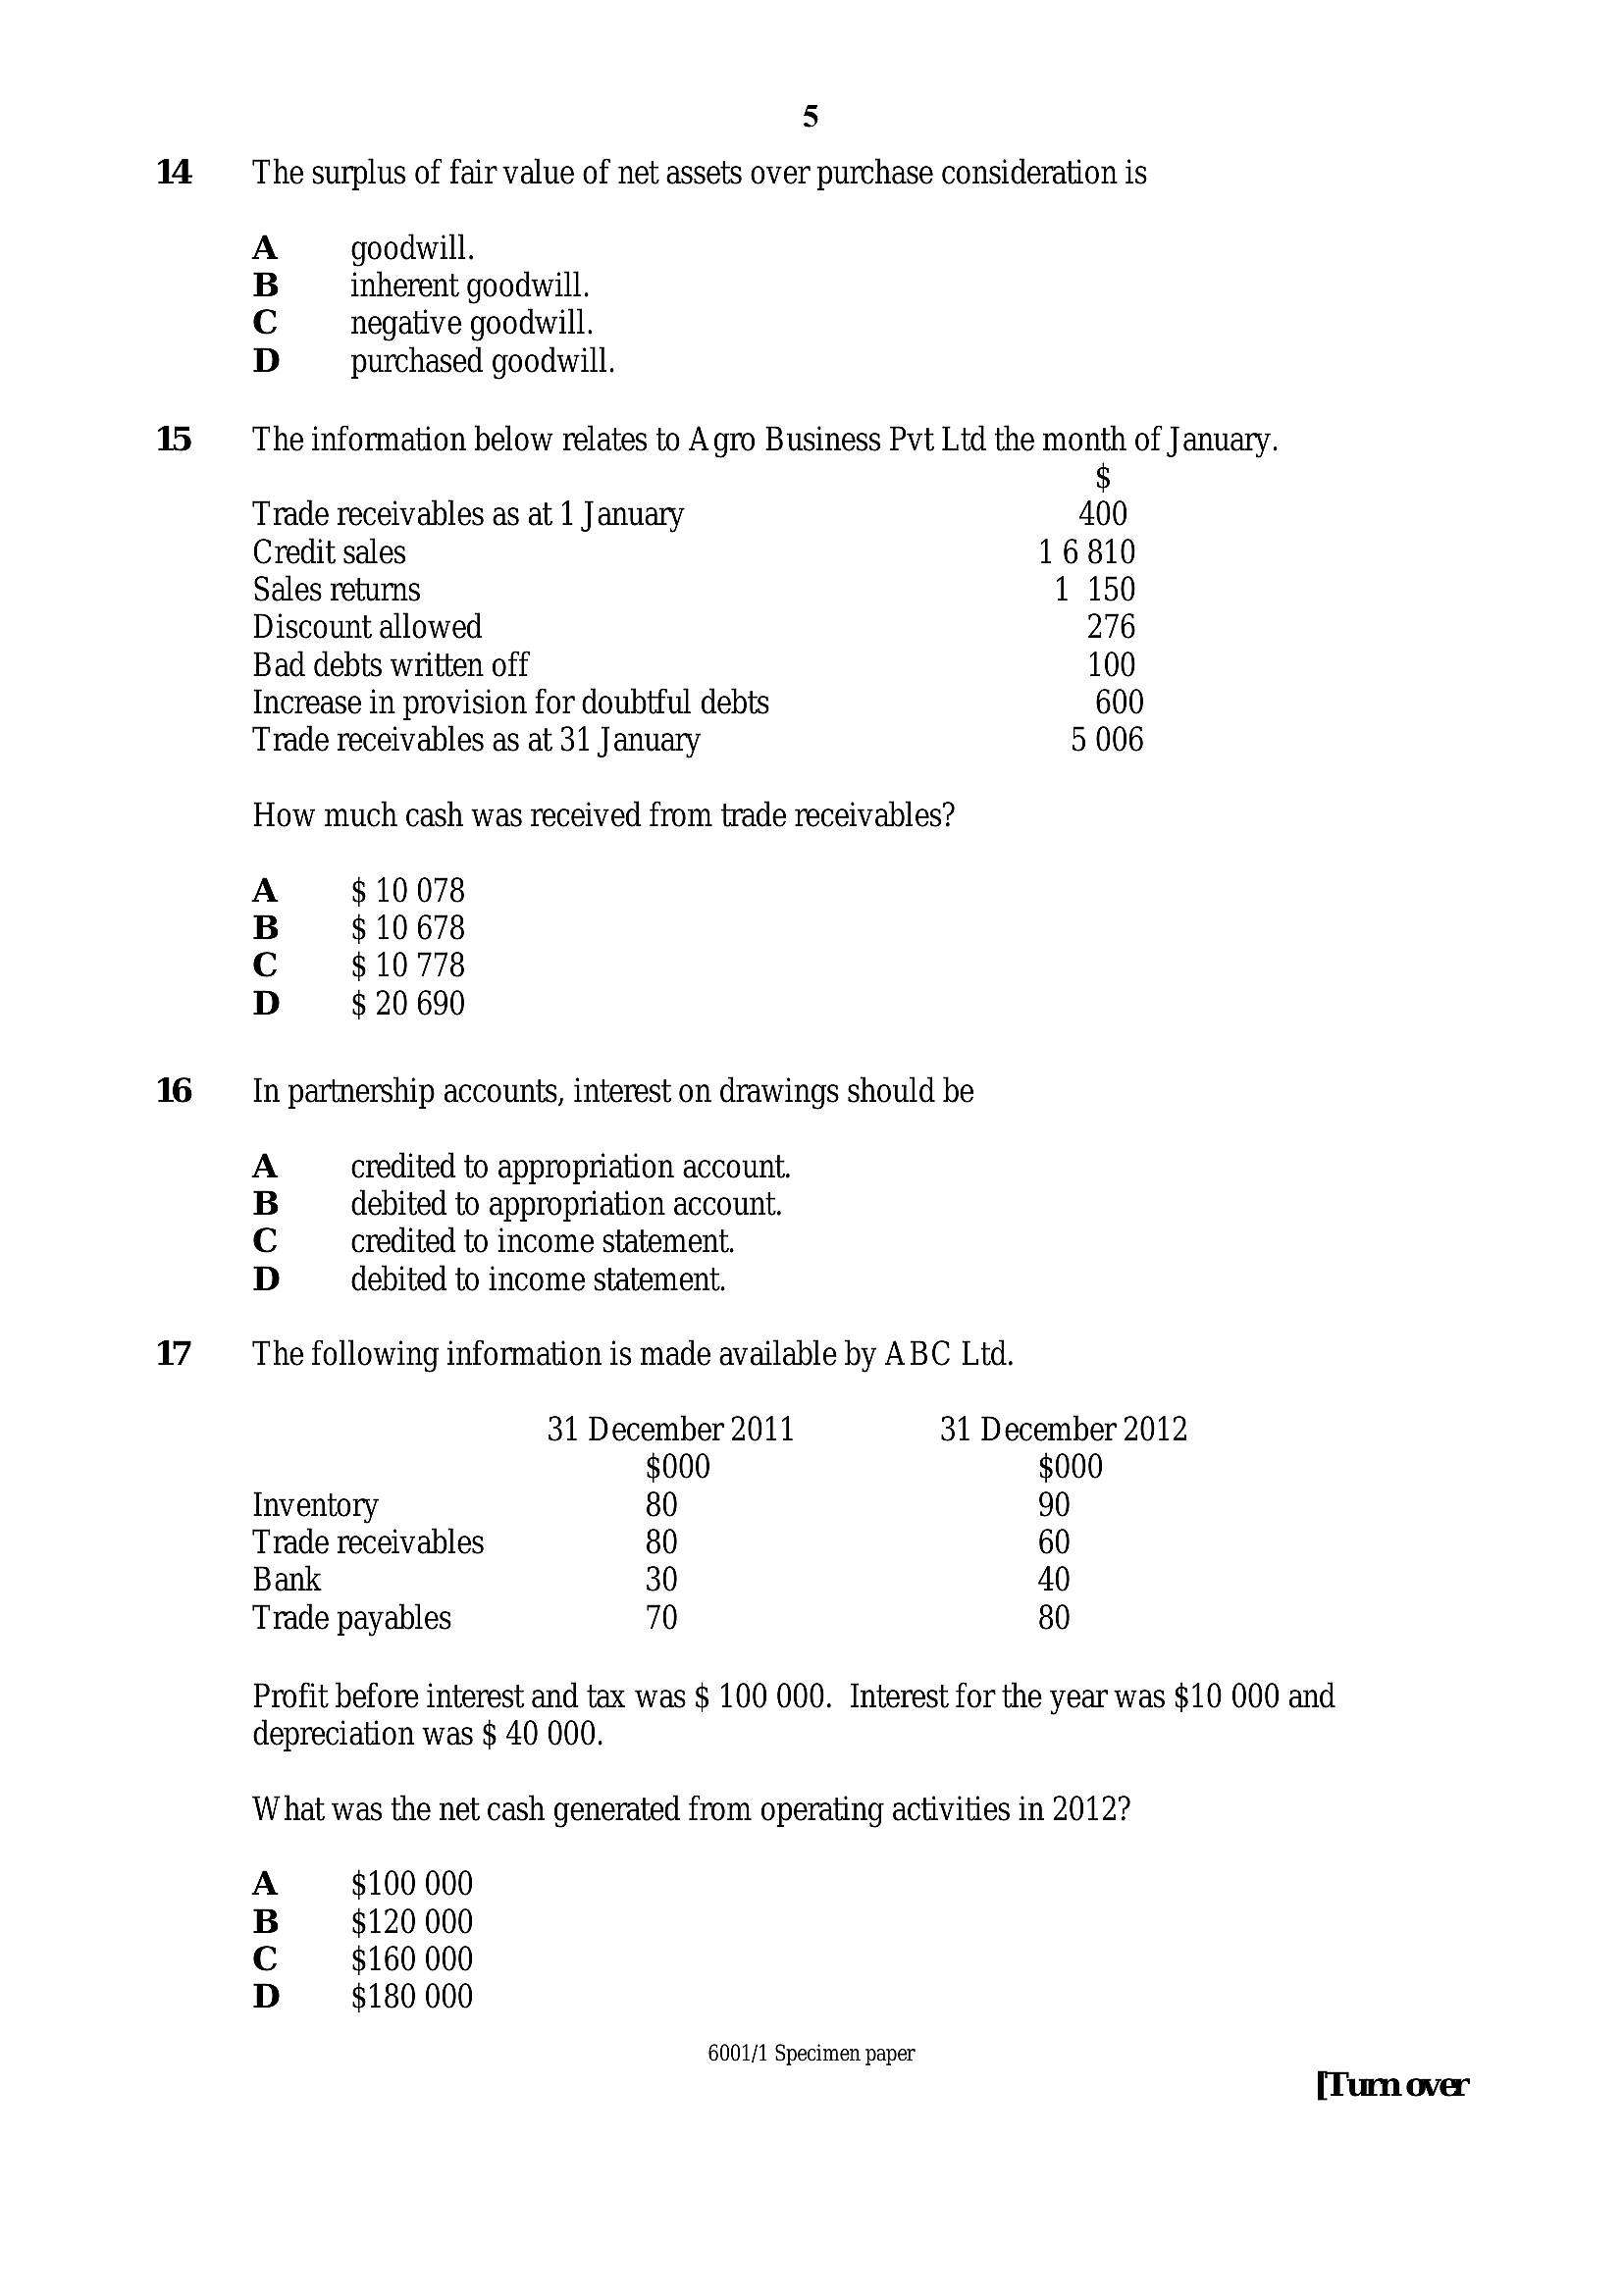
The surplus of fair value of net assets over purchase consideration is
A goodwill.
B inherent goodwill.
Cc negative goodwill.
D purchased goodwill.
The information below relates to Agro Business Pvt Ltd the month of January.
Trade receivables as at 1 January 400
Credit sales 16810
Sales returns 1 150
Discount allowed 276
Bad debts written off 100
Increase in provision for doubtful debts 600
Trade receivables as at 31 January 5 006
How much cash was received from trade receivables?
A $ 10078
B $ 10 678
Cc $ 10778
D $ 20 690
In partnership accounts, interest on drawings should be
A credited to appropriation account.
B debited to appropriation account.
Cc credited to income statement.
D debited to income statement.
The following information is made available by ABC Ltd.
31 December 2011 31 December 2012
$000 $000
Inventory 80 90
Trade receivables 80 60
Bank 30 40
Trade payables 70 80
Profit before interest and tax was $ 100 000. Interest for the year was $10 000 and
depreciation was $ 40 000.
What was the net cash generated from operating activities in 2012?
A $100 000
B $120 000
Cc $160 000
D $180 000
6001/1 Specimen paper
---
Page 6
Extracted Text
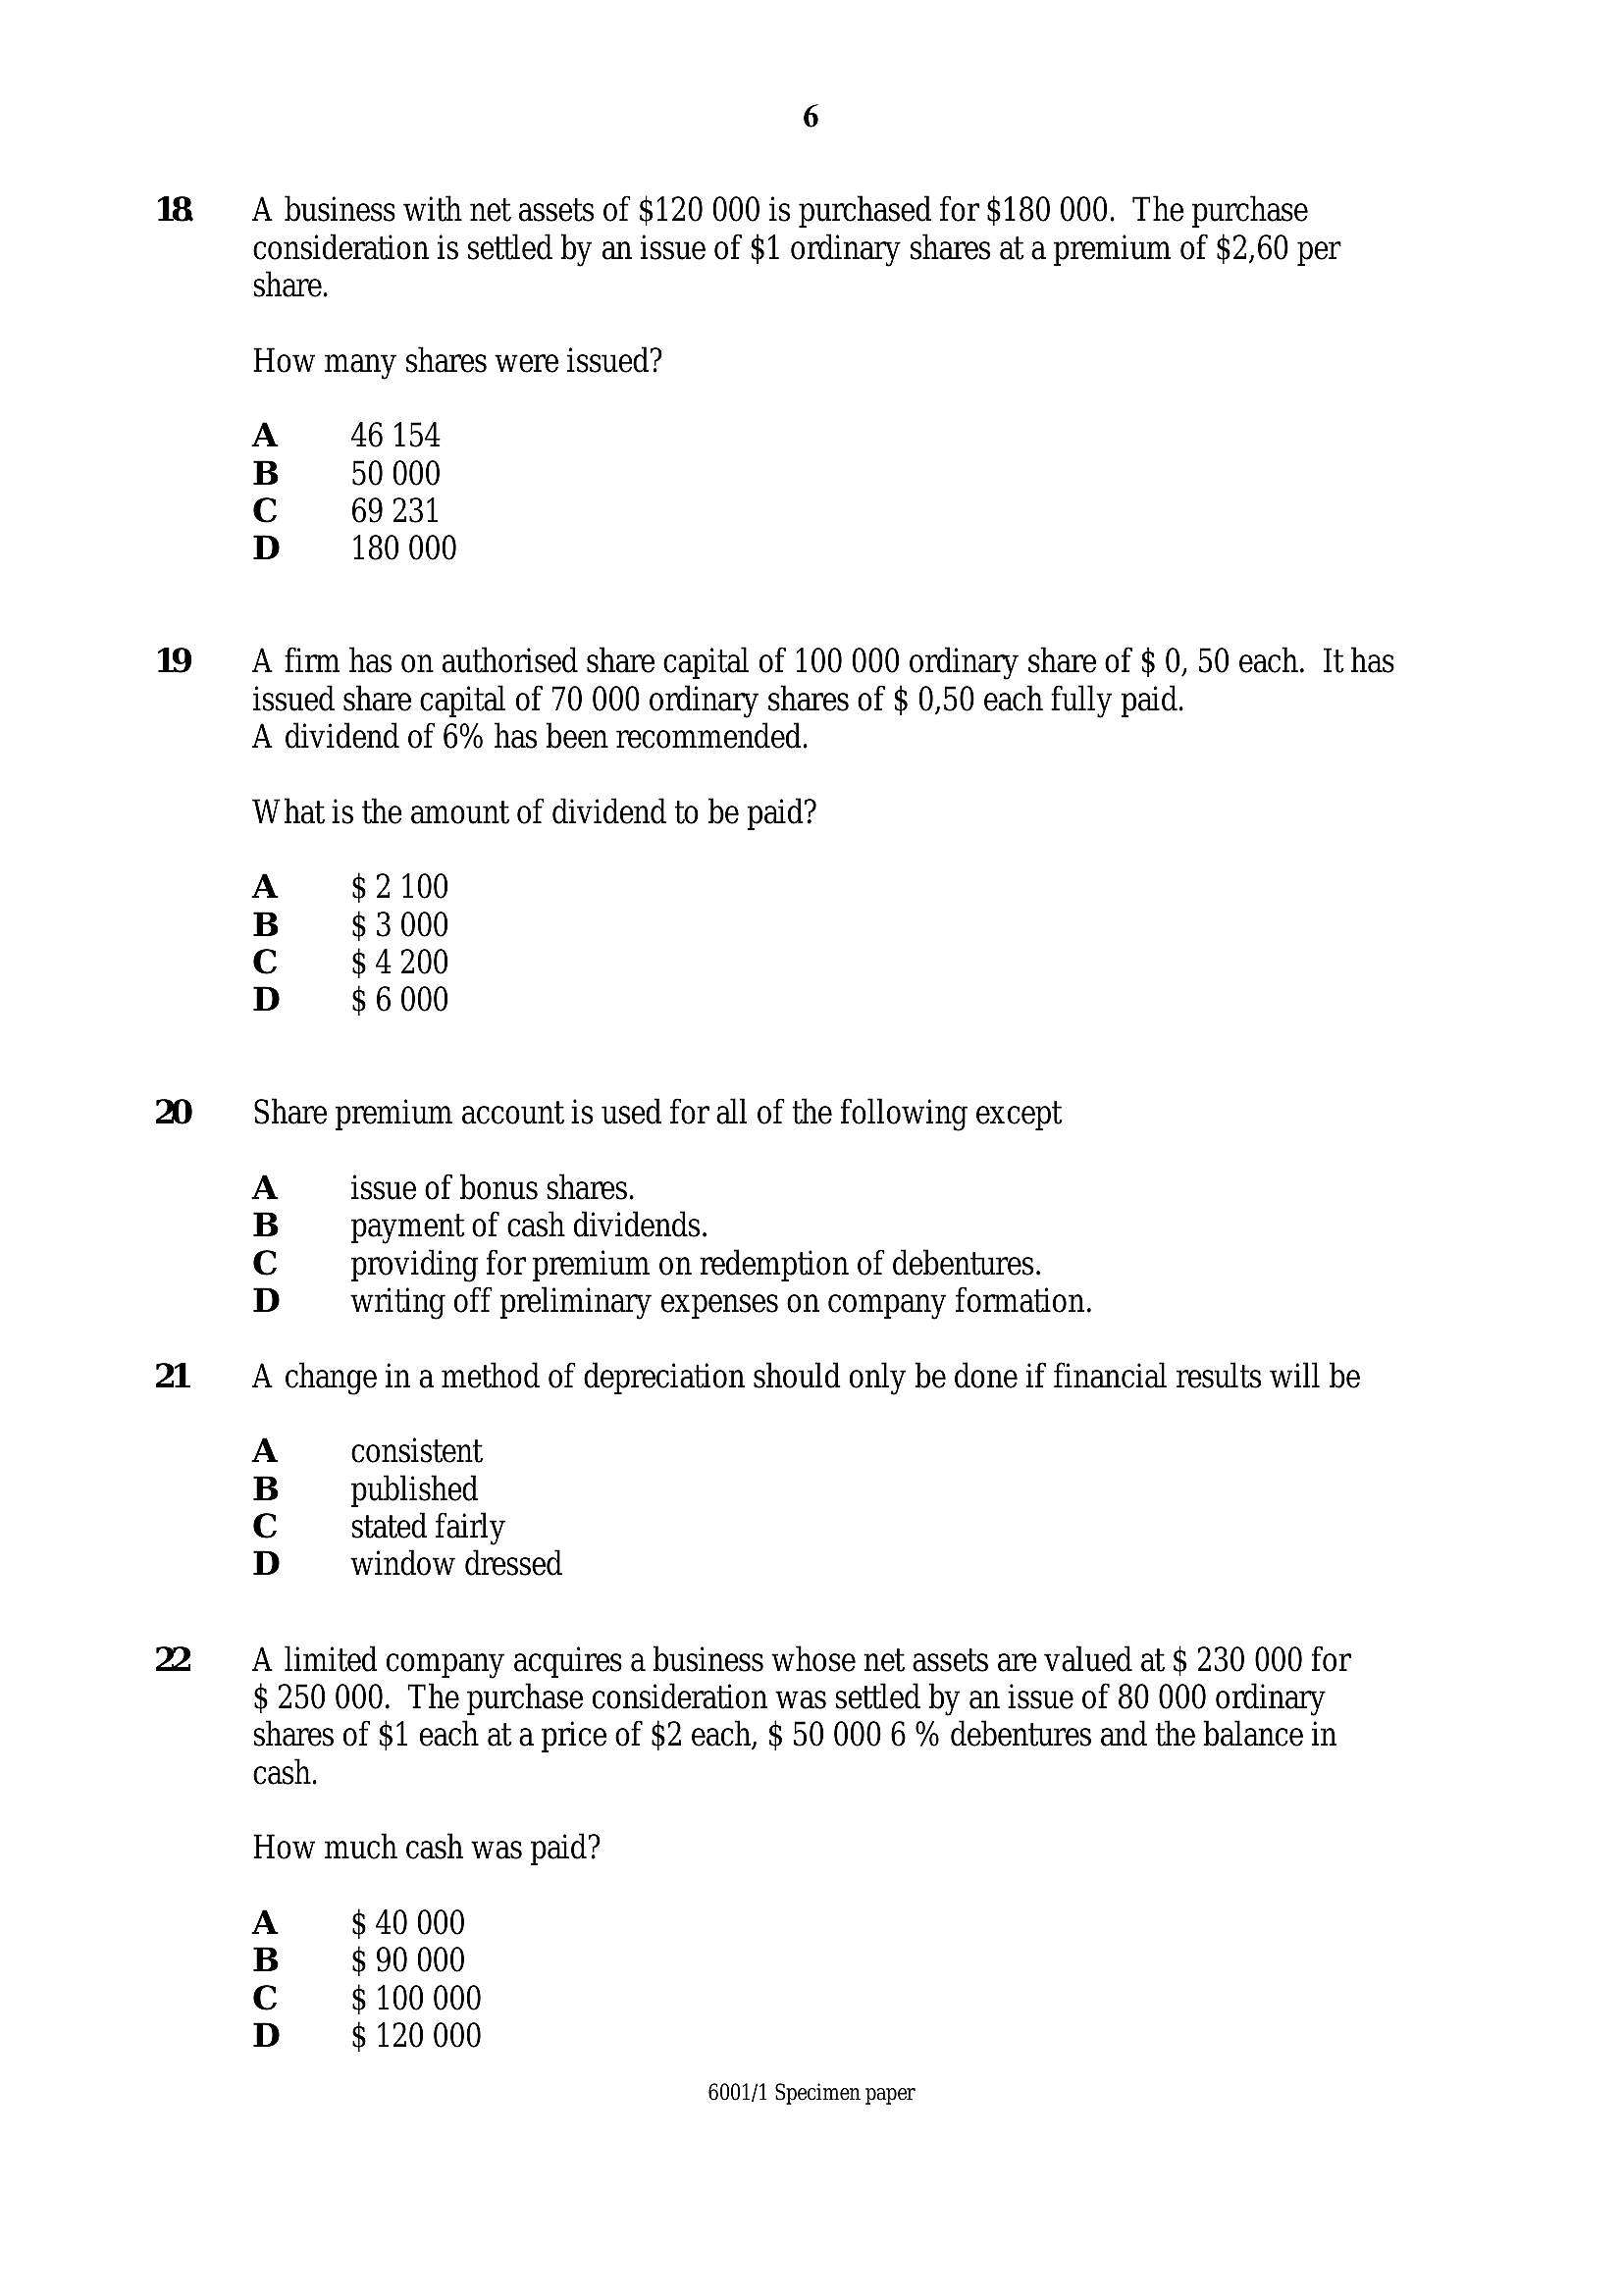
21A business with net assets of $120 000 is purchased for $180 000. The purchase
consideration is settled by an issue of $1 ordinary shares at a premium of $2,60 per
share.
How many shares were issued?
A 46 154
B 50 000
Cc 69 231
D 180 000
A firm has on authorised share capital of 100 000 ordinary share of $ 0, 50 each. It has
issued share capital of 70 000 ordinary shares of $ 0,50 each fully paid.
A dividend of 6% has been recommended.
What is the amount of dividend to be paid?
A $ 2 100
B $ 3 000
Cc $ 4 200
D $ 6 000
Share premium account is used for all of the following except
A issue of bonus shares.
B payment of cash dividends.
Cc providing for premium on redemption of debentures.
D writing off preliminary expenses on company formation.
A change in a method of depreciation should only be done if financial results will be
A consistent
B published
Cc stated fairly
D window dressed
A limited company acquires a business whose net assets are valued at $ 230 000 for
$ 250 000. The purchase consideration was settled by an issue of 80 000 ordinary
shares of $1 each at a price of $2 each, $ 50 000 6 % debentures and the balance in
cash.
How much cash was paid?
A $ 40 000
B $ 90 000
Cc $ 100 000
D $ 120 000
6001/1 Specimen paper
---
Page 7
Extracted Text
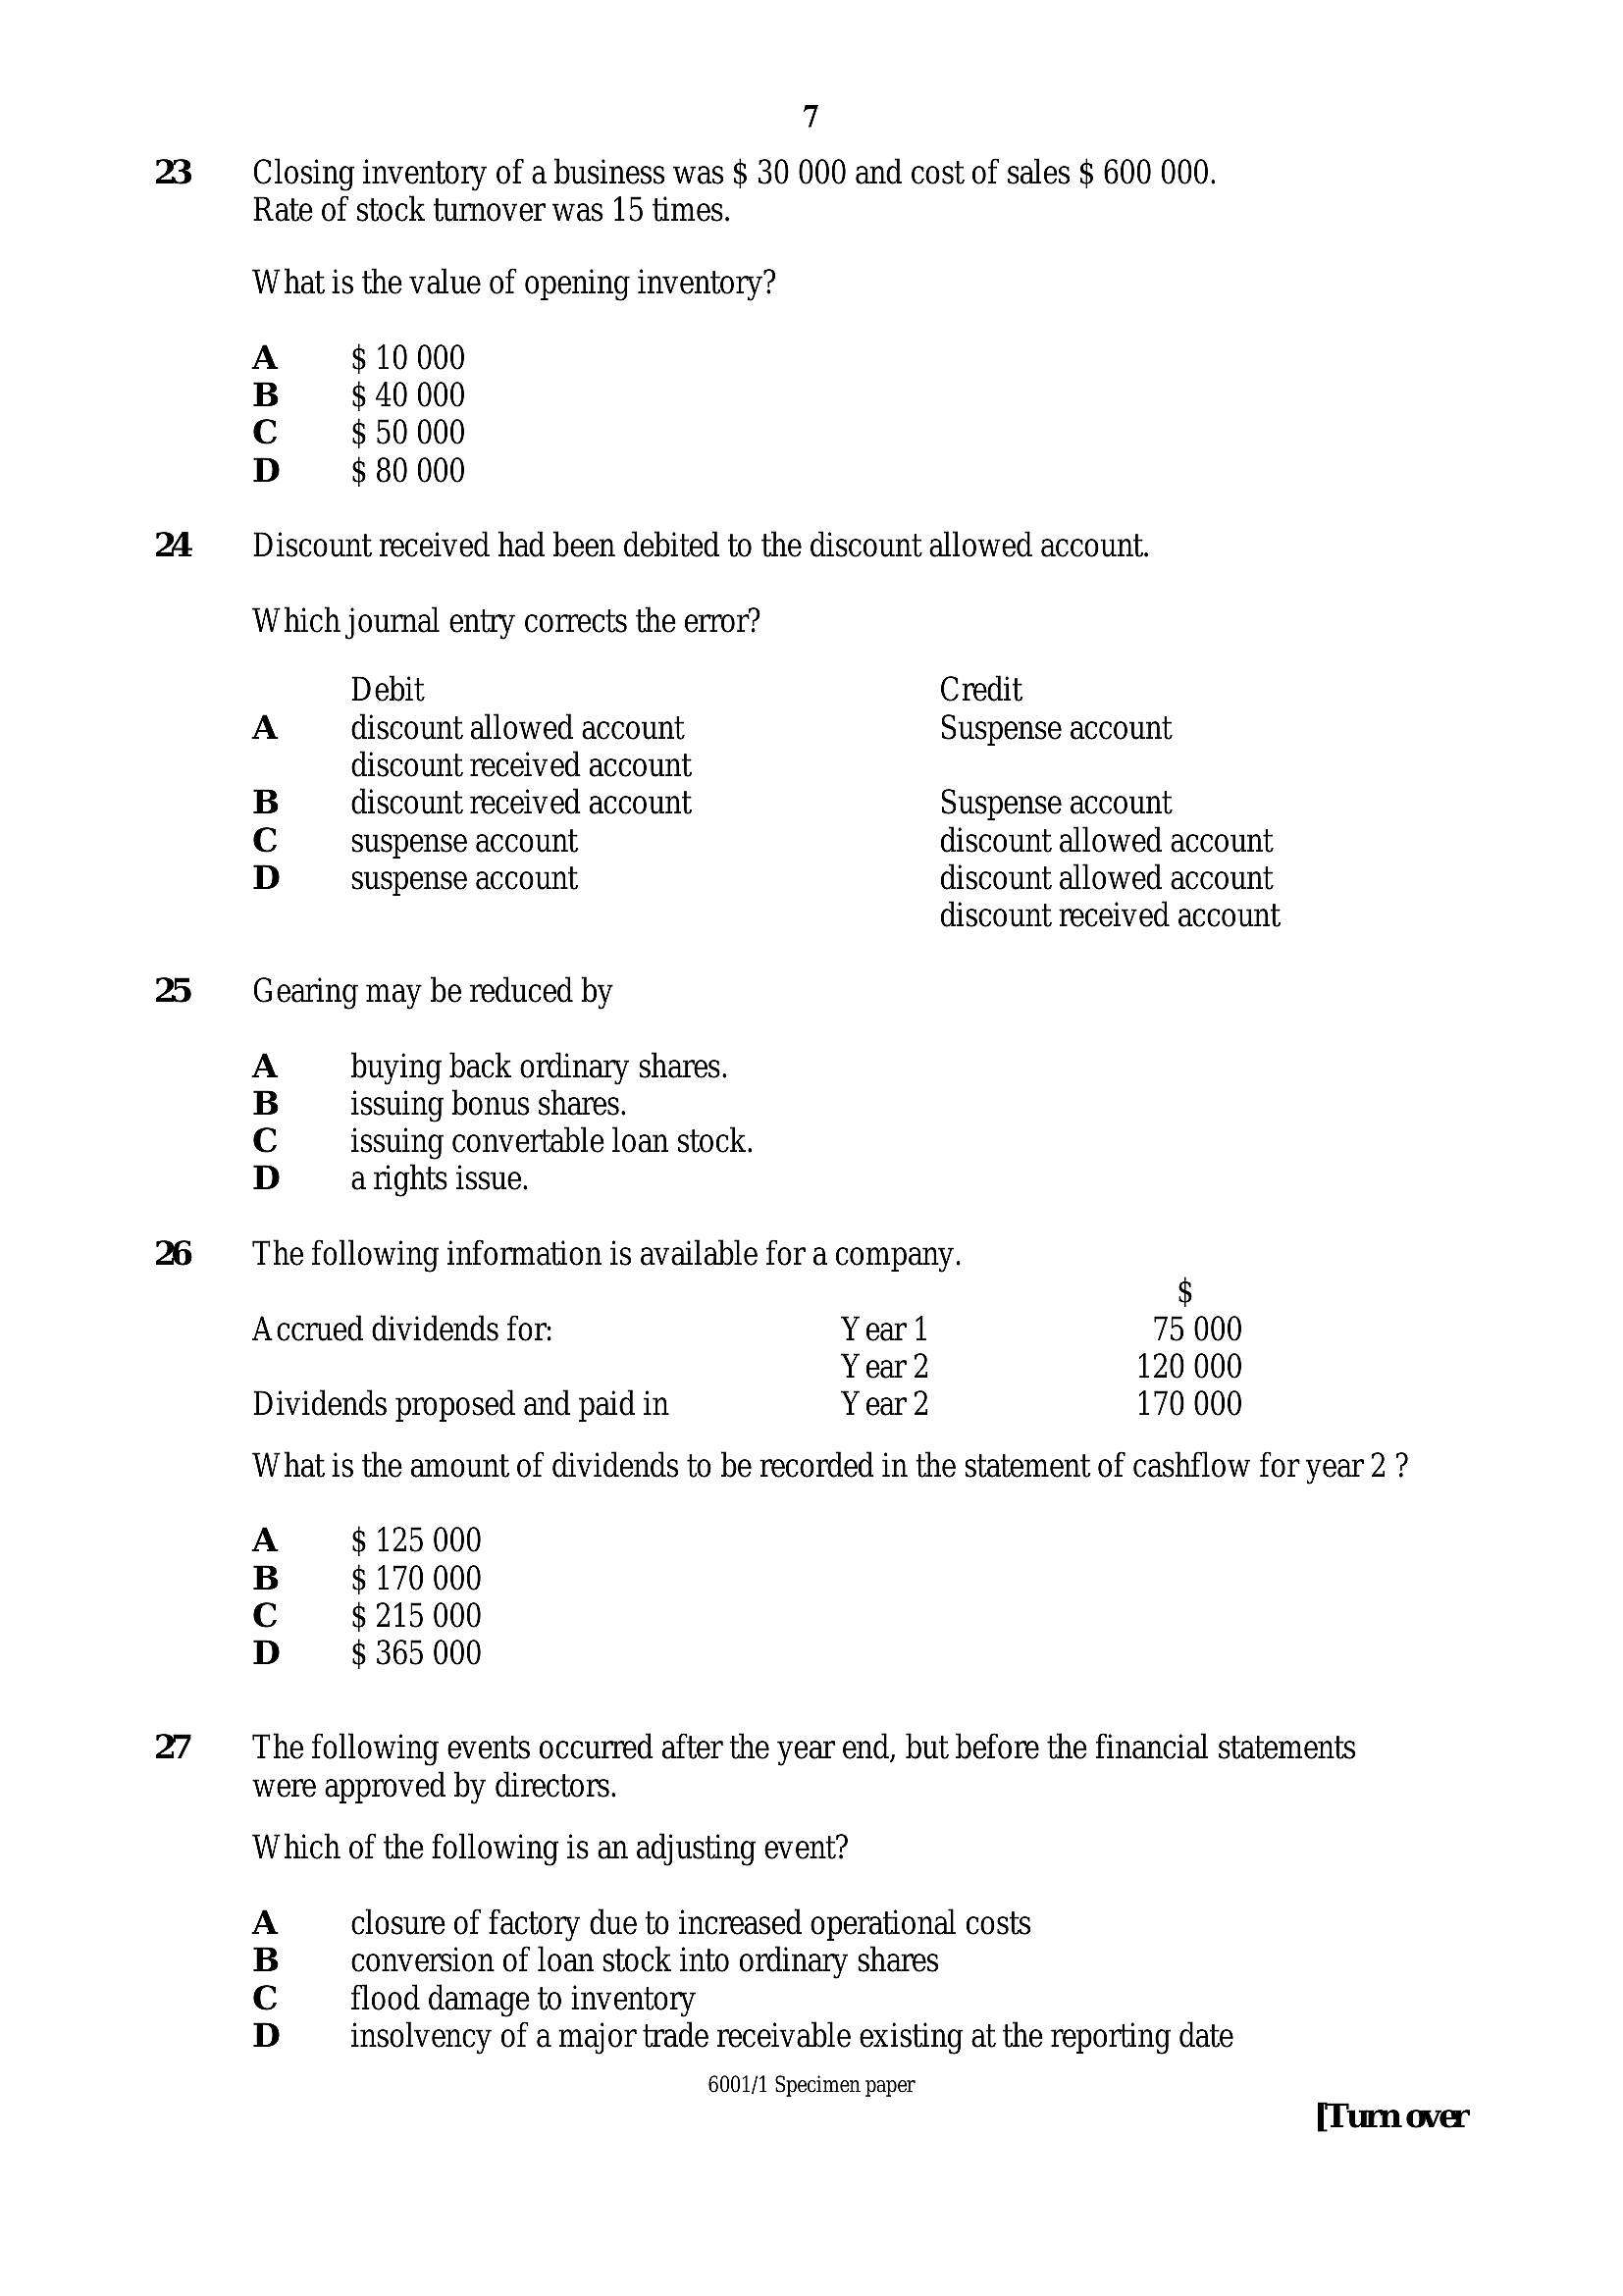
7Closing inventory of a business was $ 30 000 and cost of sales $ 600 000.
Rate of stock turnover was 15 times.
What is the value of opening inventory?
A $ 10 000
B $ 40 000
Cc $ 50 000
D $ 80 000
Discount received had been debited to the discount allowed account.
Which journal entry corrects the error?
Debit Credit
A discount allowed account Suspense account
discount received account
B discount received account Suspense account
Cc suspense account discount allowed account
D suspense account discount allowed account
discount received account
Gearing may be reduced by
A buying back ordinary shares.
B issuing bonus shares.
Cc issuing convertable loan stock.
D a rights issue.
The following information is available for a company.
$
Accrued dividends for: Year 1 75 000
Year 2 120 000
Dividends proposed and paid in Year 2 170 000
What is the amount of dividends to be recorded in the statement of cashflow for year 2 ?
A $ 125 000
B $ 170 000
Cc $ 215 000
D $ 365 000
The following events occurred after the year end, but before the financial statements
were approved by directors.
Which of the following is an adjusting event?
closure of factory due to increased operational costs
conversion of loan stock into ordinary shares
flood damage to inventory
insolvency of a major trade receivable existing at the reporting date
SanY
6001/1 Specimen paper
---
Page 8
Extracted Text
318
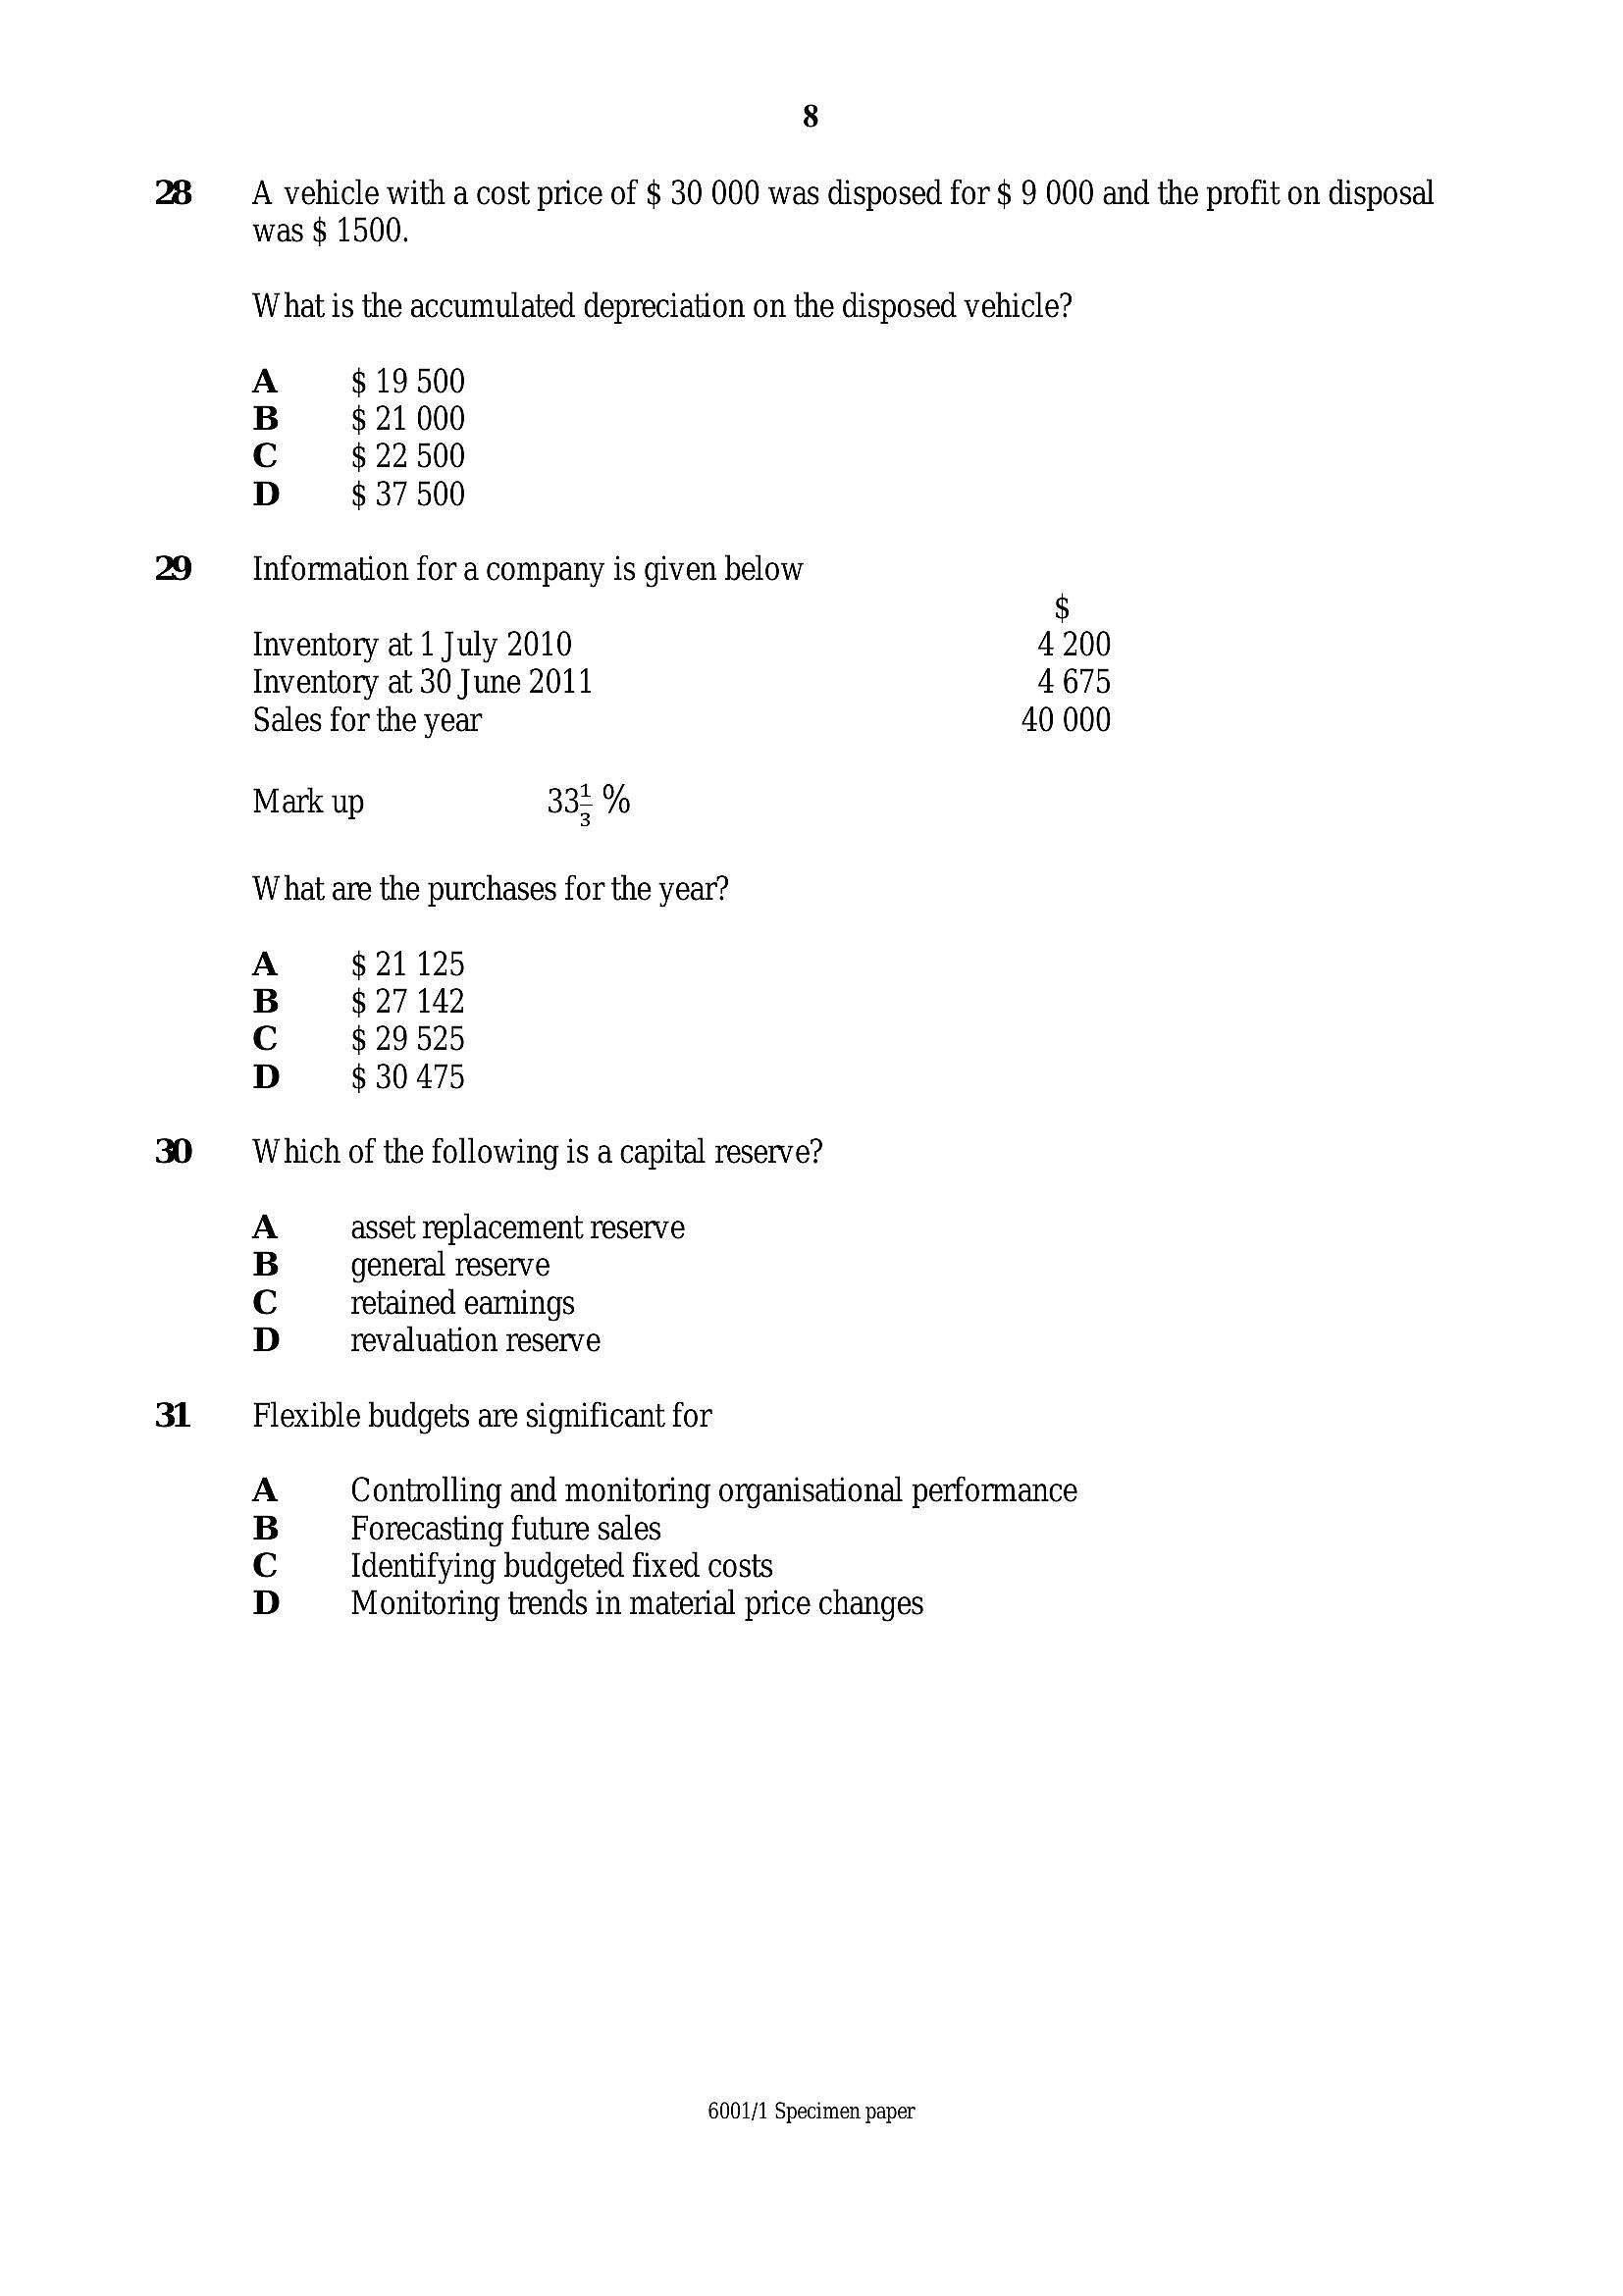
A vehicle with a cost price of $ 30 000 was disposed for $ 9 000 and the profit on disposal
was $ 1500.
What is the accumulated depreciation on the disposed vehicle?
A $ 19 500
B $ 21 000
Cc $ 22 500
D $ 37 500
Information for a company is given below
$
Inventory at 1 July 2010 4 200
Inventory at 30 June 2011 4675
Sales for the year 40 000
Mark up 33, %
What are the purchases for the year?
A $ 21125
B $ 27 142
Cc $ 29 525
D $ 30475
Which of the following is a capital reserve?
A asset replacement reserve
B general reserve
Cc retained earnings
D revaluation reserve
Flexible budgets are significant for
Controlling and monitoring organisational performance
Forecasting future sales
Identifying budgeted fixed costs
Monitoring trends in material price changes
Sanr
6001/1 Specimen paper
---
Page 9
Extracted Text
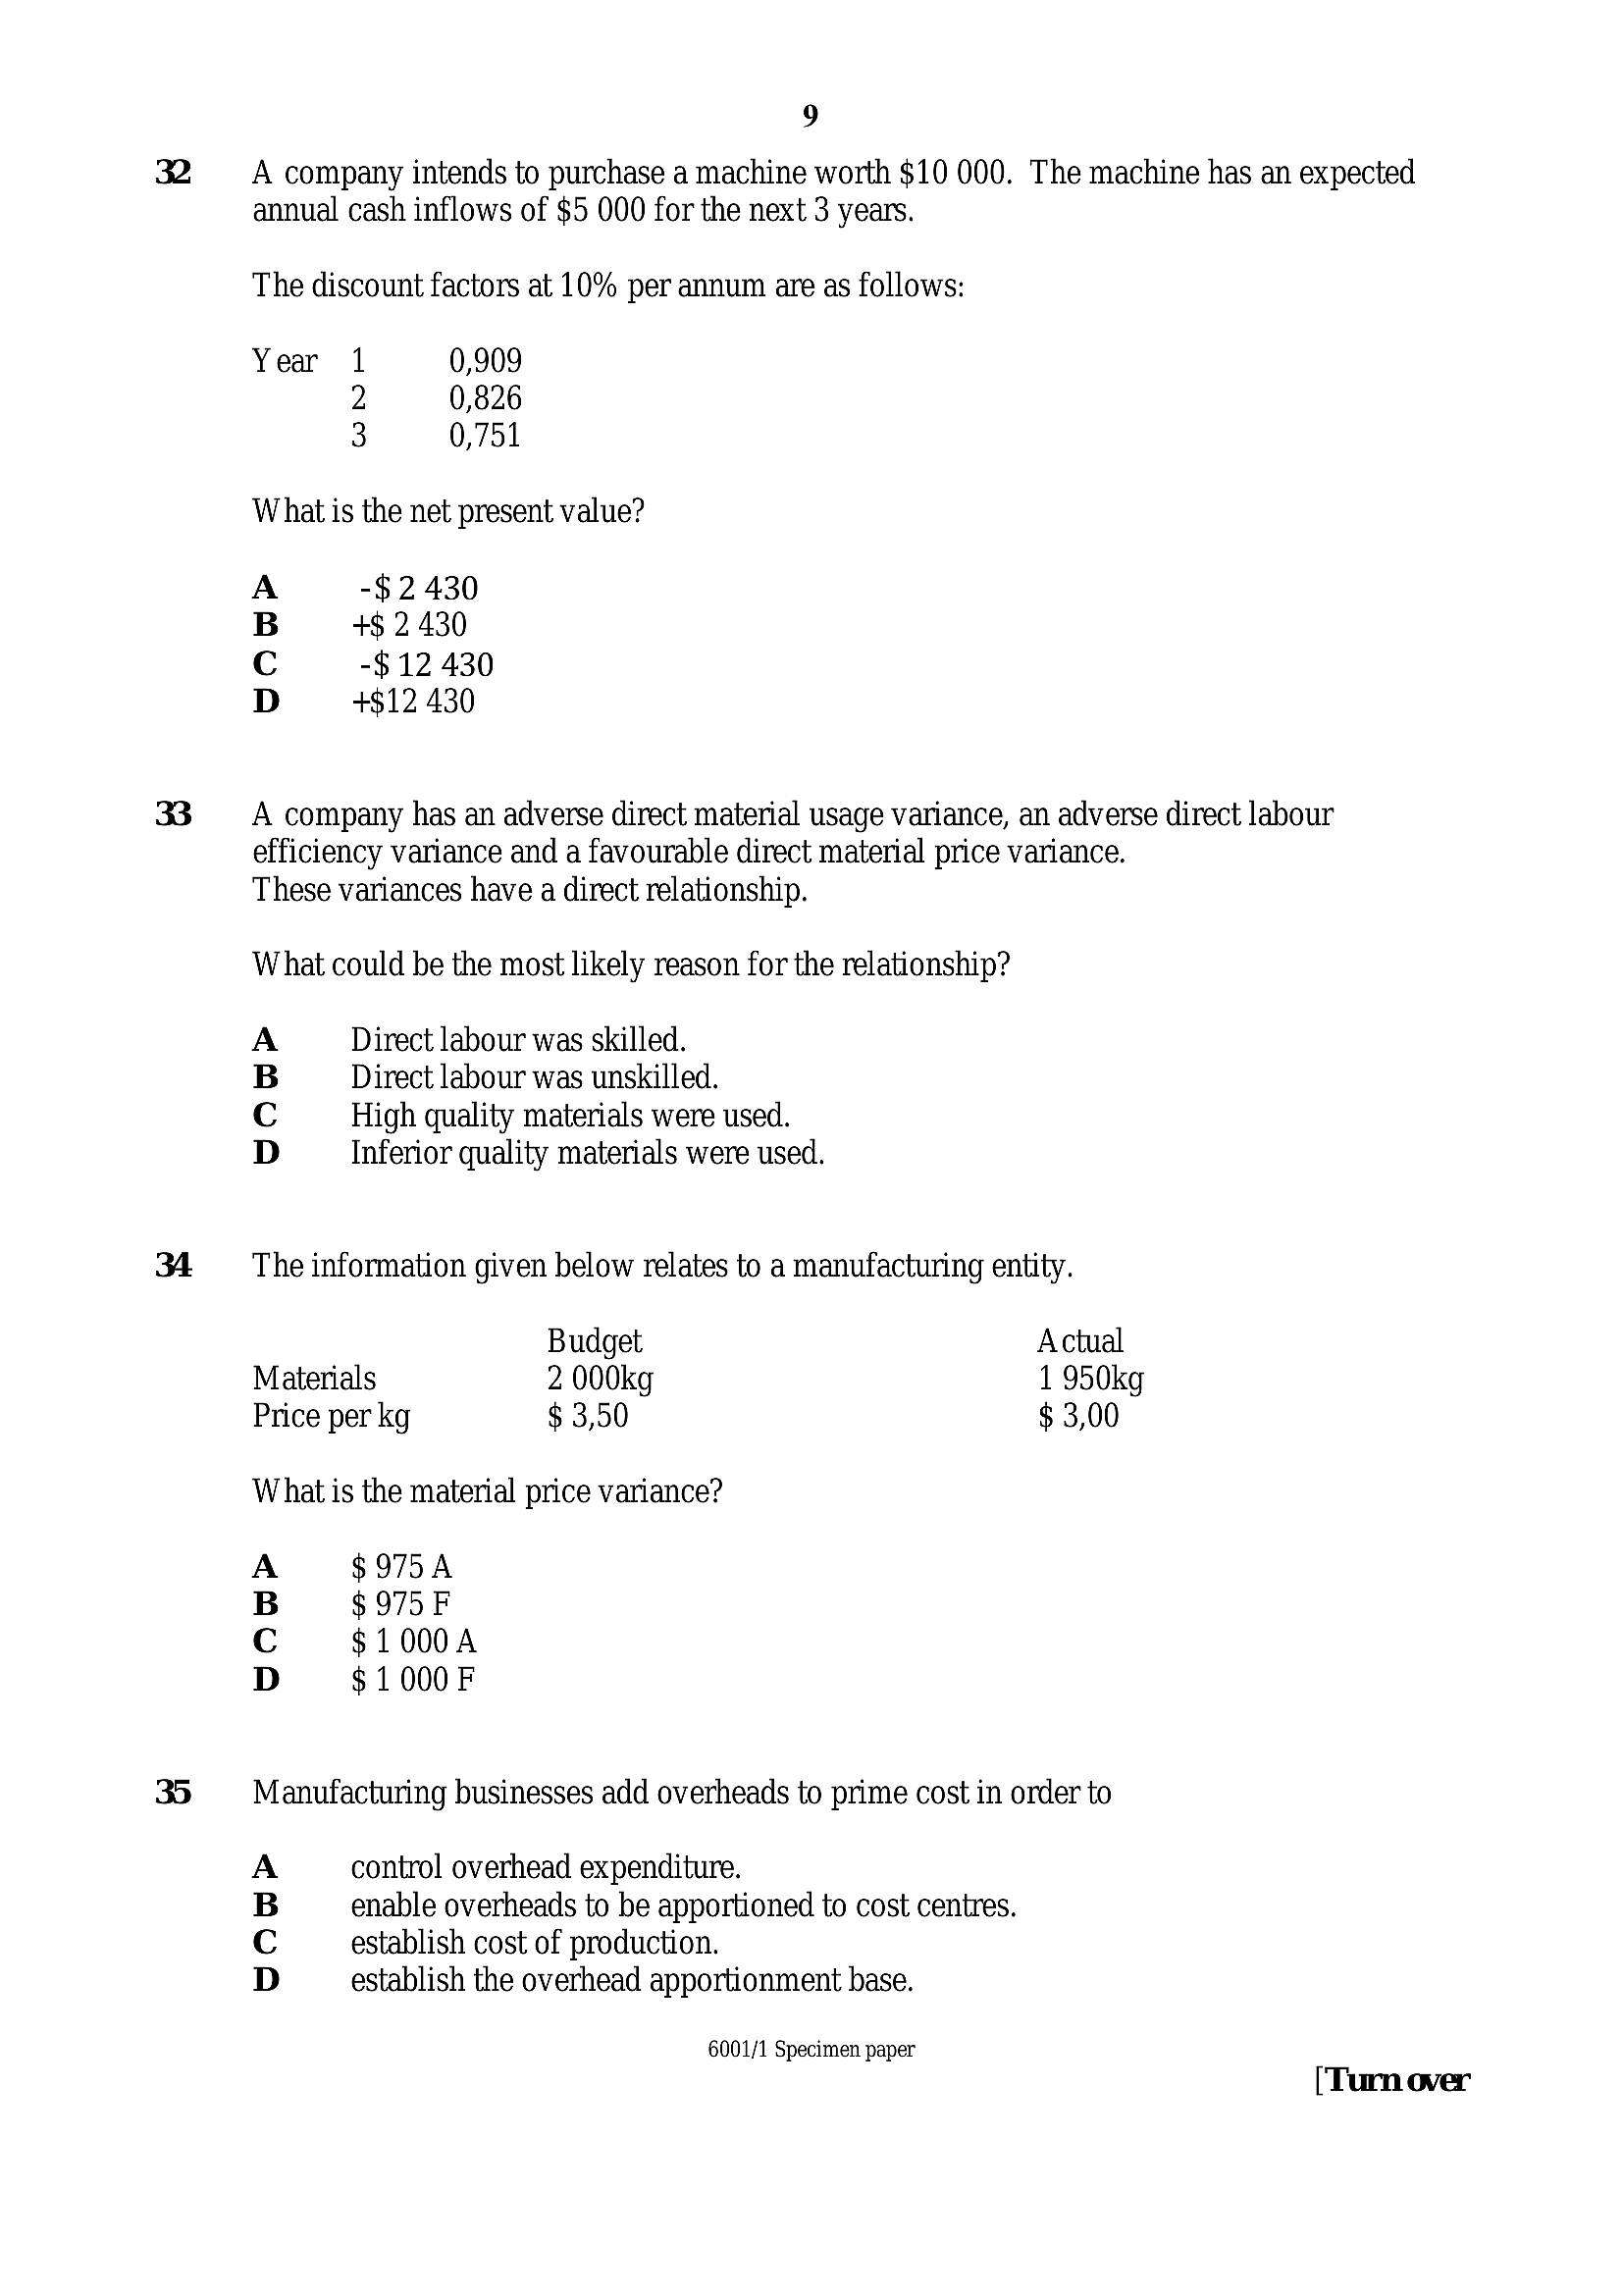
9A company intends to purchase a machine worth $10 000. The machine has an expected
annual cash inflows of $5 000 for the next 3 years.
The discount factors at 10% per annum are as follows:
Year 1 0,909
2 0,826
3 0,751
What is the net present value?
A -$ 2 430
B +$ 2 430
Cc -$ 12 430
D +$12 430
A company has an adverse direct material usage variance, an adverse direct labour
efficiency variance and a favourable direct material price variance.
These variances have a direct relationship.
What could be the most likely reason for the relationship?
Direct labour was skilled.
Direct labour was unskilled.
High quality materials were used.
Inferior quality materials were used.
SanY
The information given below relates to a manufacturing entity.
Budget Actual
Materials 2 000kg 1 950kg
Price per kg $ 3,50 $ 3,00
What is the material price variance?
A $975 A
B $975 F
Cc $1000A
D $1000F
Manufacturing businesses add overheads to prime cost in order to
control overhead expenditure.
enable overheads to be apportioned to cost centres.
establish cost of production.
establish the overhead apportionment base.
Sanr
6001/1 Specimen paper
[Turn over
---
Page 10
Extracted Text
10The information given below is for a manufacturing company
Production in units 6 000 12 000
Production overheads $ 33 000 $ 45 000
Administration overheads $ 27 000 $ 27 000
What are the total fixed costs?
A $ 21 000
B $ 27 000
Cc $ 48 000
D $ 60 000
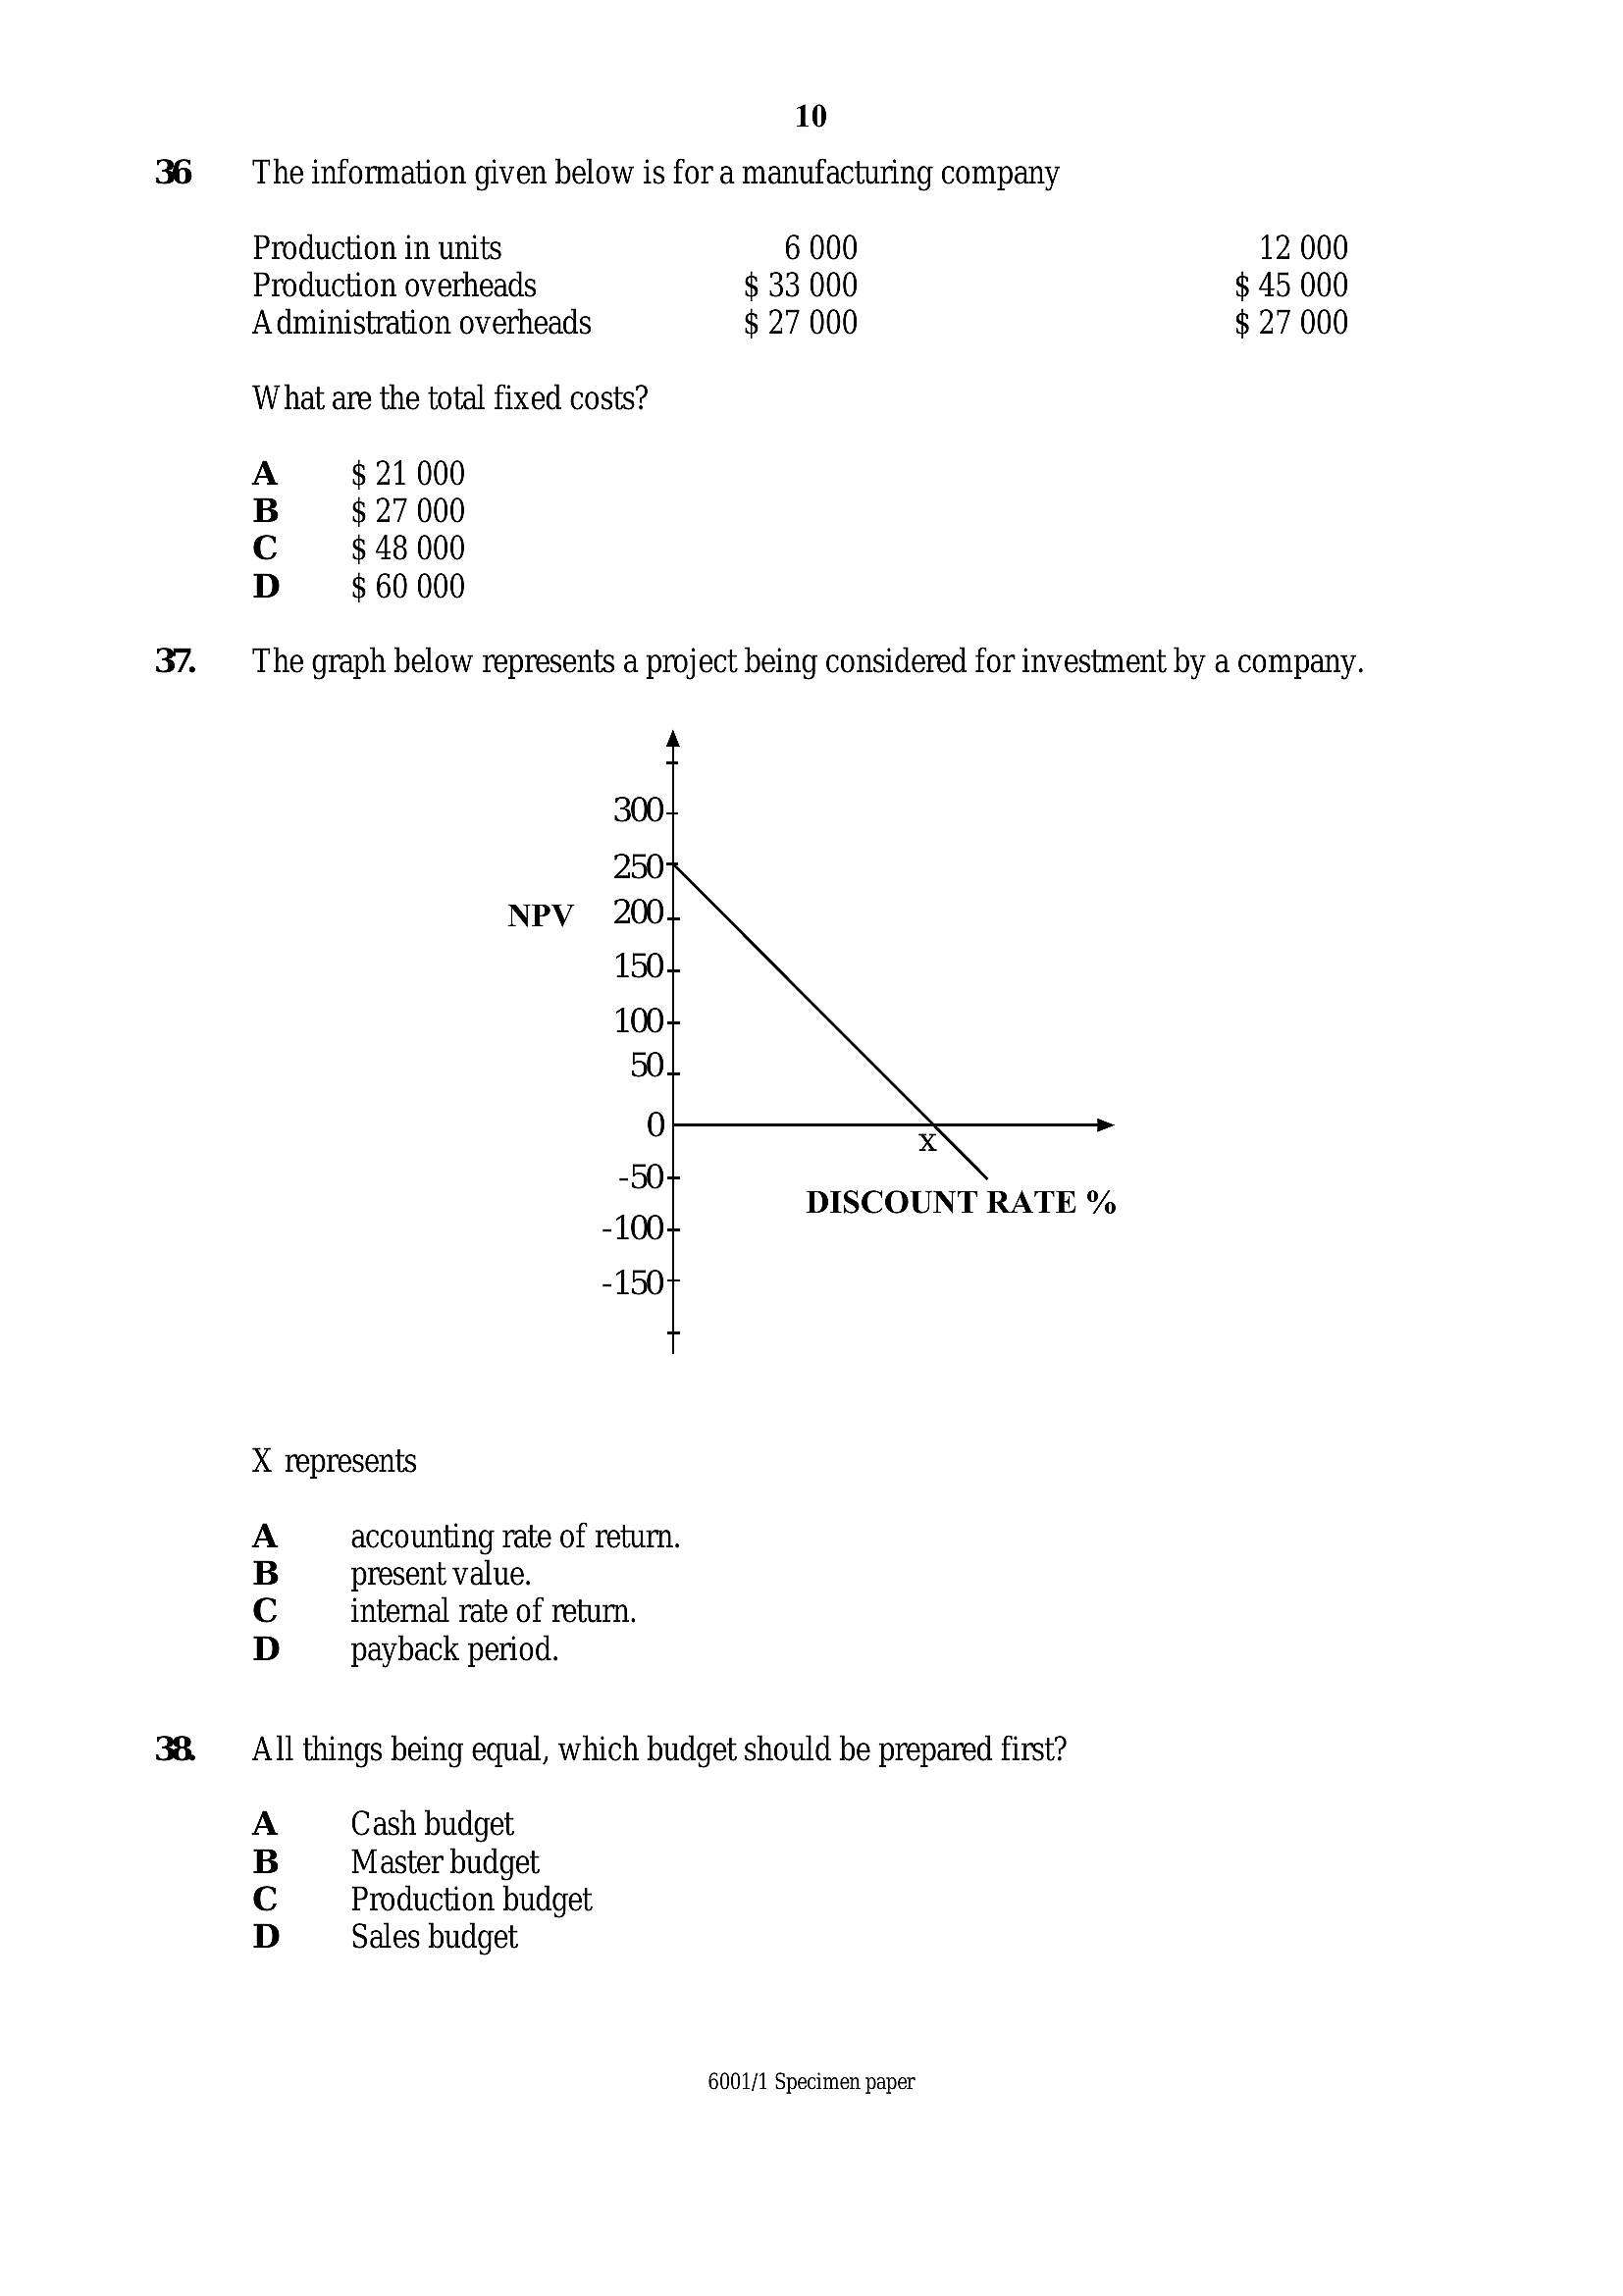
The graph below represents a project being considered for investment by a company.
4
300}
250
NPV 2001
150+
-50+
DISCOUNT RATE %
-100+
-1507
X represents
A accounting rate of return.
B present value.
Cc internal rate of return.
D payback period.
All things being equal, which budget should be prepared first?
A Cash budget
B Master budget
Cc Production budget
D Sales budget
6001/1 Specimen paper
---
Page 11
Extracted Text
11 The purpose of management accounting is to A calculate cost of production. determine the contribution made by employees.B
Cc give a true and fair view of a company’s financial situation.
D provide relevant information for decision making.
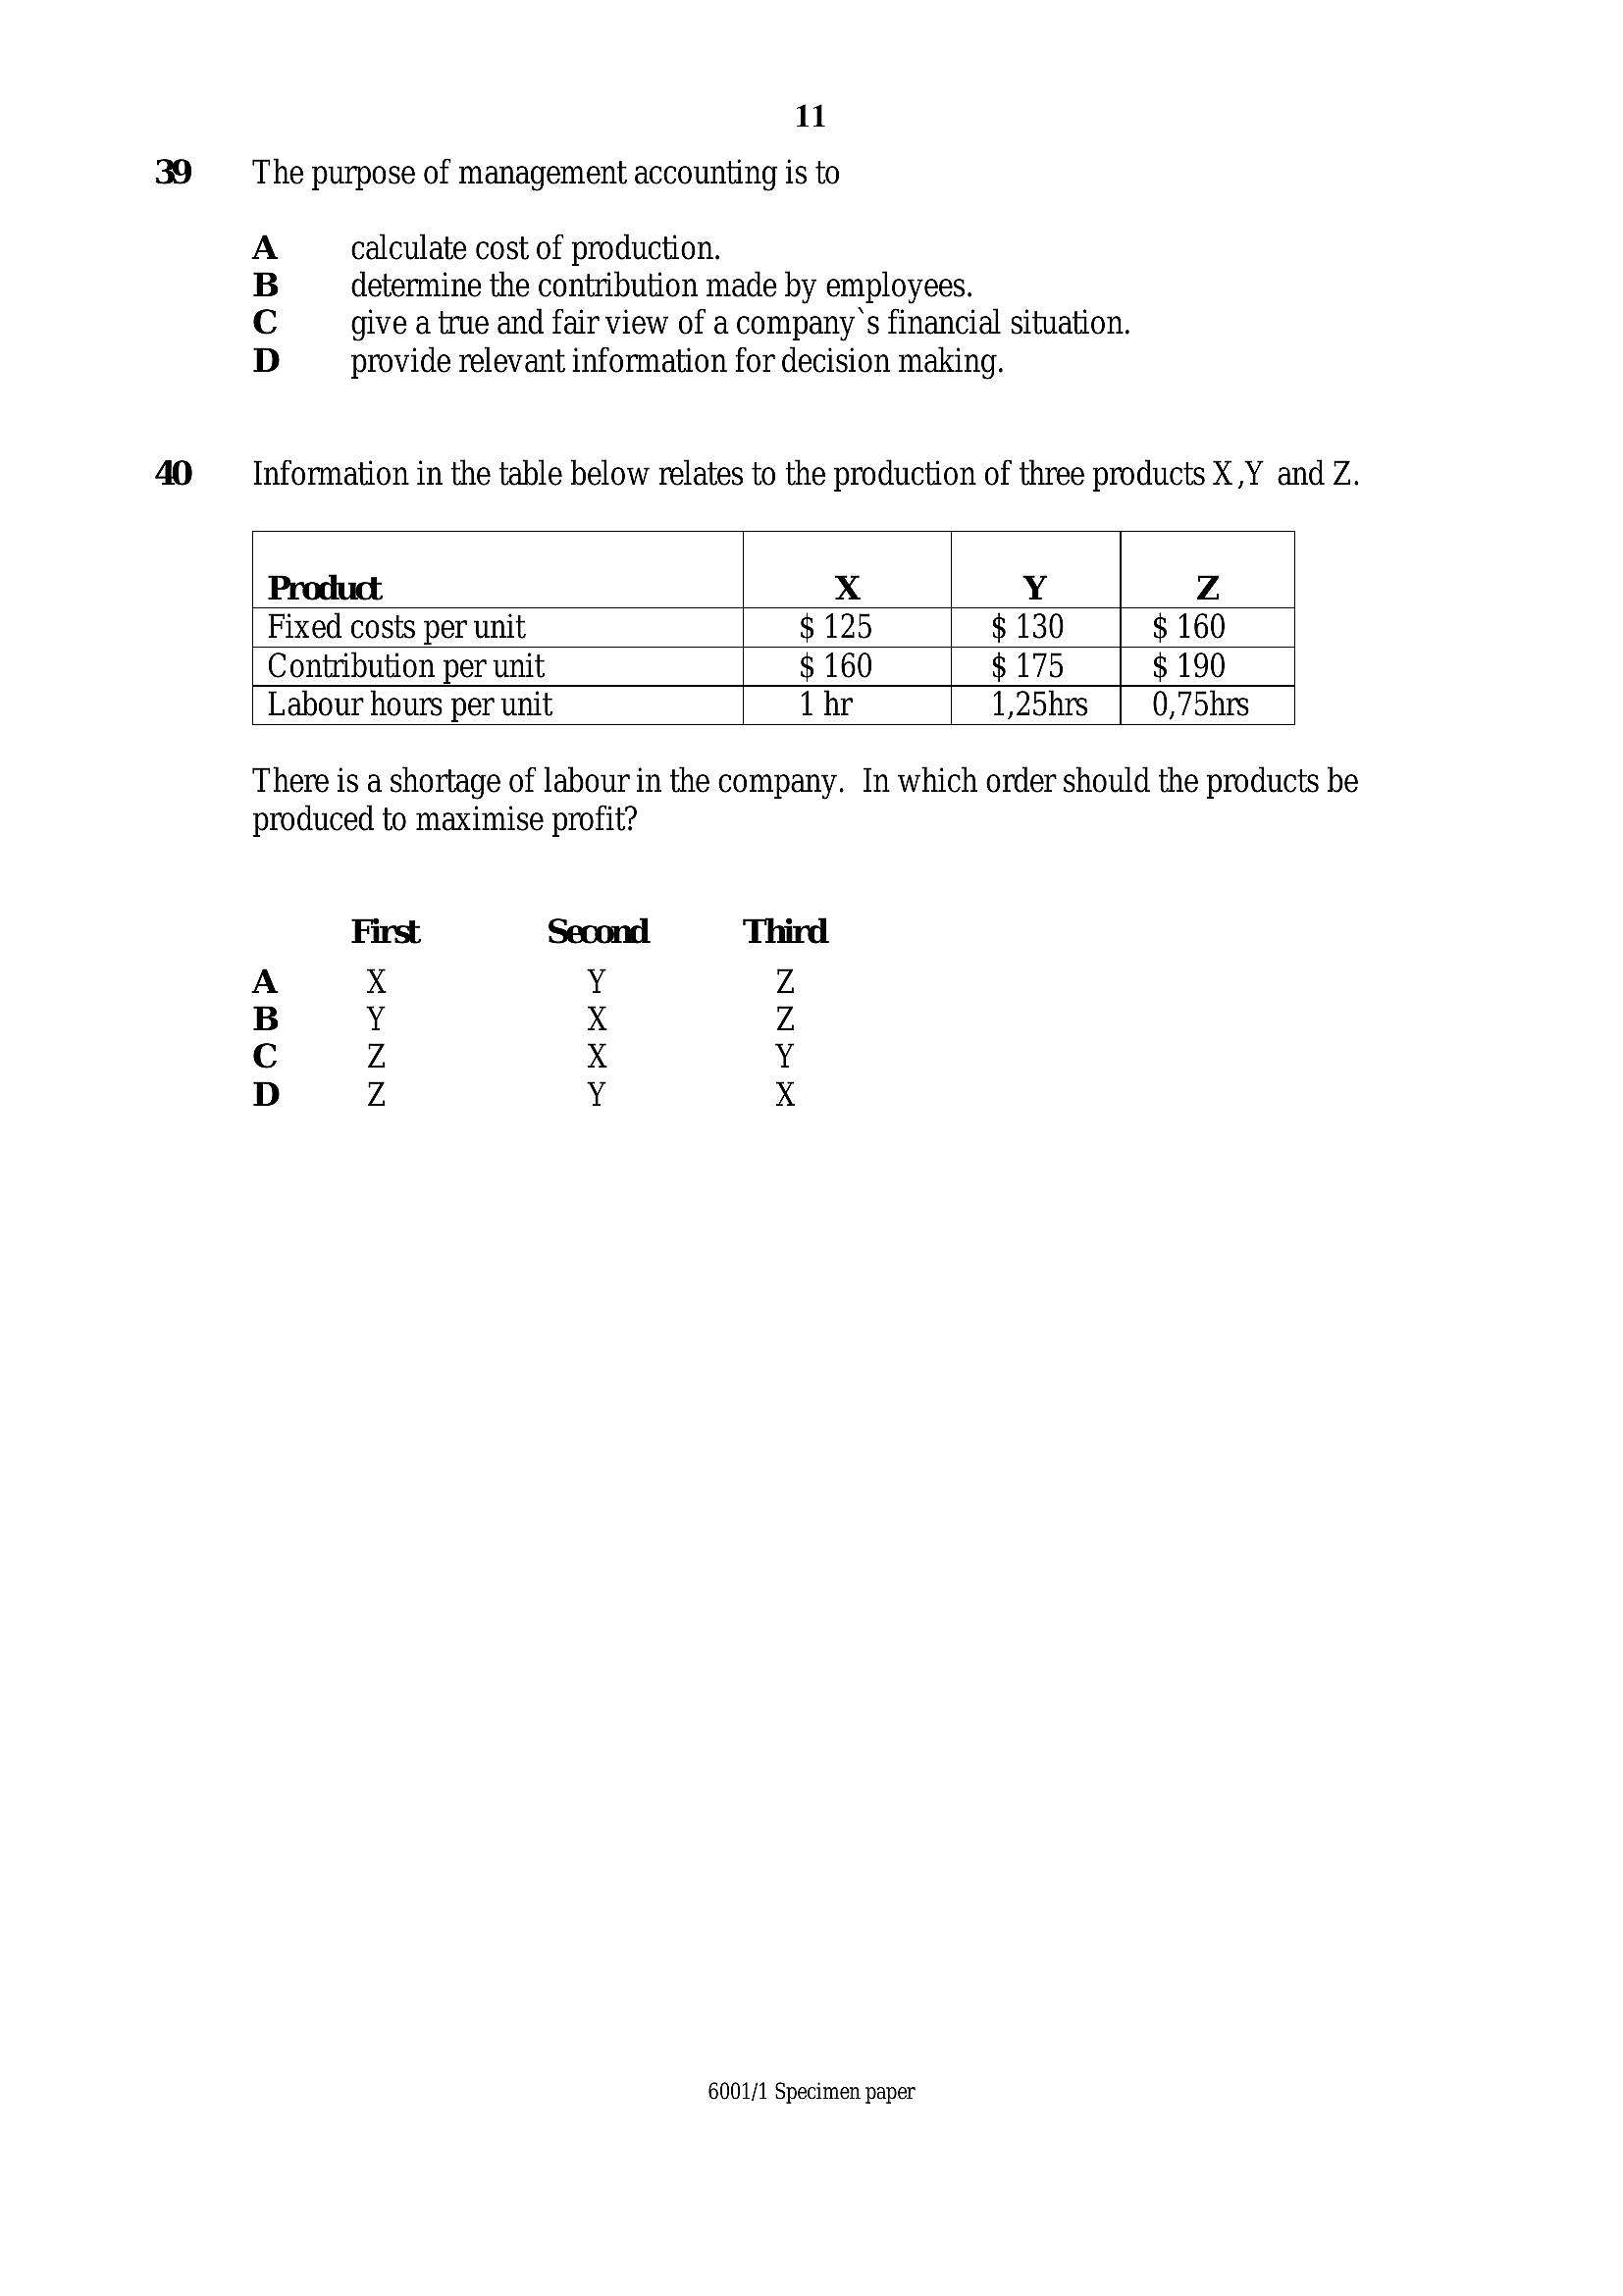
Information in the table below relates to the production of three products X,Y and Z.
Product Ȣ Y Z
Fixed costs per unit $125 $ 130 $ 160
Contribution per unit $ 160 $175 $ 190
Labour hours per unit 1hr 1,25hrs 0,75hrs
There is a shortage of labour in the company. In which order should the products be
produced to maximise profit?
First Second Third
Bae
NN < p<
bd bd
~<NN
6001/1 Specimen paper
---
Page 12
Extracted Text
12 BLANK PAGE6001/1 Specimen paper
---