📄 Exam Questions & Readable Text Transcript
Full OCR-extracted text of questions, syllabus codes, and exam instructions.
Extracted Content: 6001q02
Page 1
Extracted Text
Candidate Name Centre Number Candidate NumberZIMBABWE SCHOOL EXAMINATIONS COUNCIL
General Certificate of Education Advanced Level
ACCOUNTING 6001/2
PAPER 2: Structured Questions
SPECIMEN PAPER 1 hour 45 minutes
Candidates answer on the question paper
Additional materials:
No additional materials are required
TIME 1 hour 45 minutes
INSTRUCTIONS TO CANDIDATES
Write your name, Centre number and candidate number in the spaces at the top of this page.
Answer all questions.
Write your answers in the spaces provided on the question paper. If you require extra paper,
ask the supervisor for supplementary answer paper.
FOR EXAMINER’S USE
INFORMATION FOR CANDIDATES 1
The number of marks is given in brackets [ ] at the end of
each question or part question. 2
Y ou may use a calculator. 3
The businesses in this paper are intended to be fictitious. 4
TOTAL
This question paper consists of 14 printed pages and 2 blank pages.
Copyright: Zimbabwe School Examinations Council, Specimen paper.
@ZIMSEC Specimen paper [Turn over
---
Page 2
Extracted Text
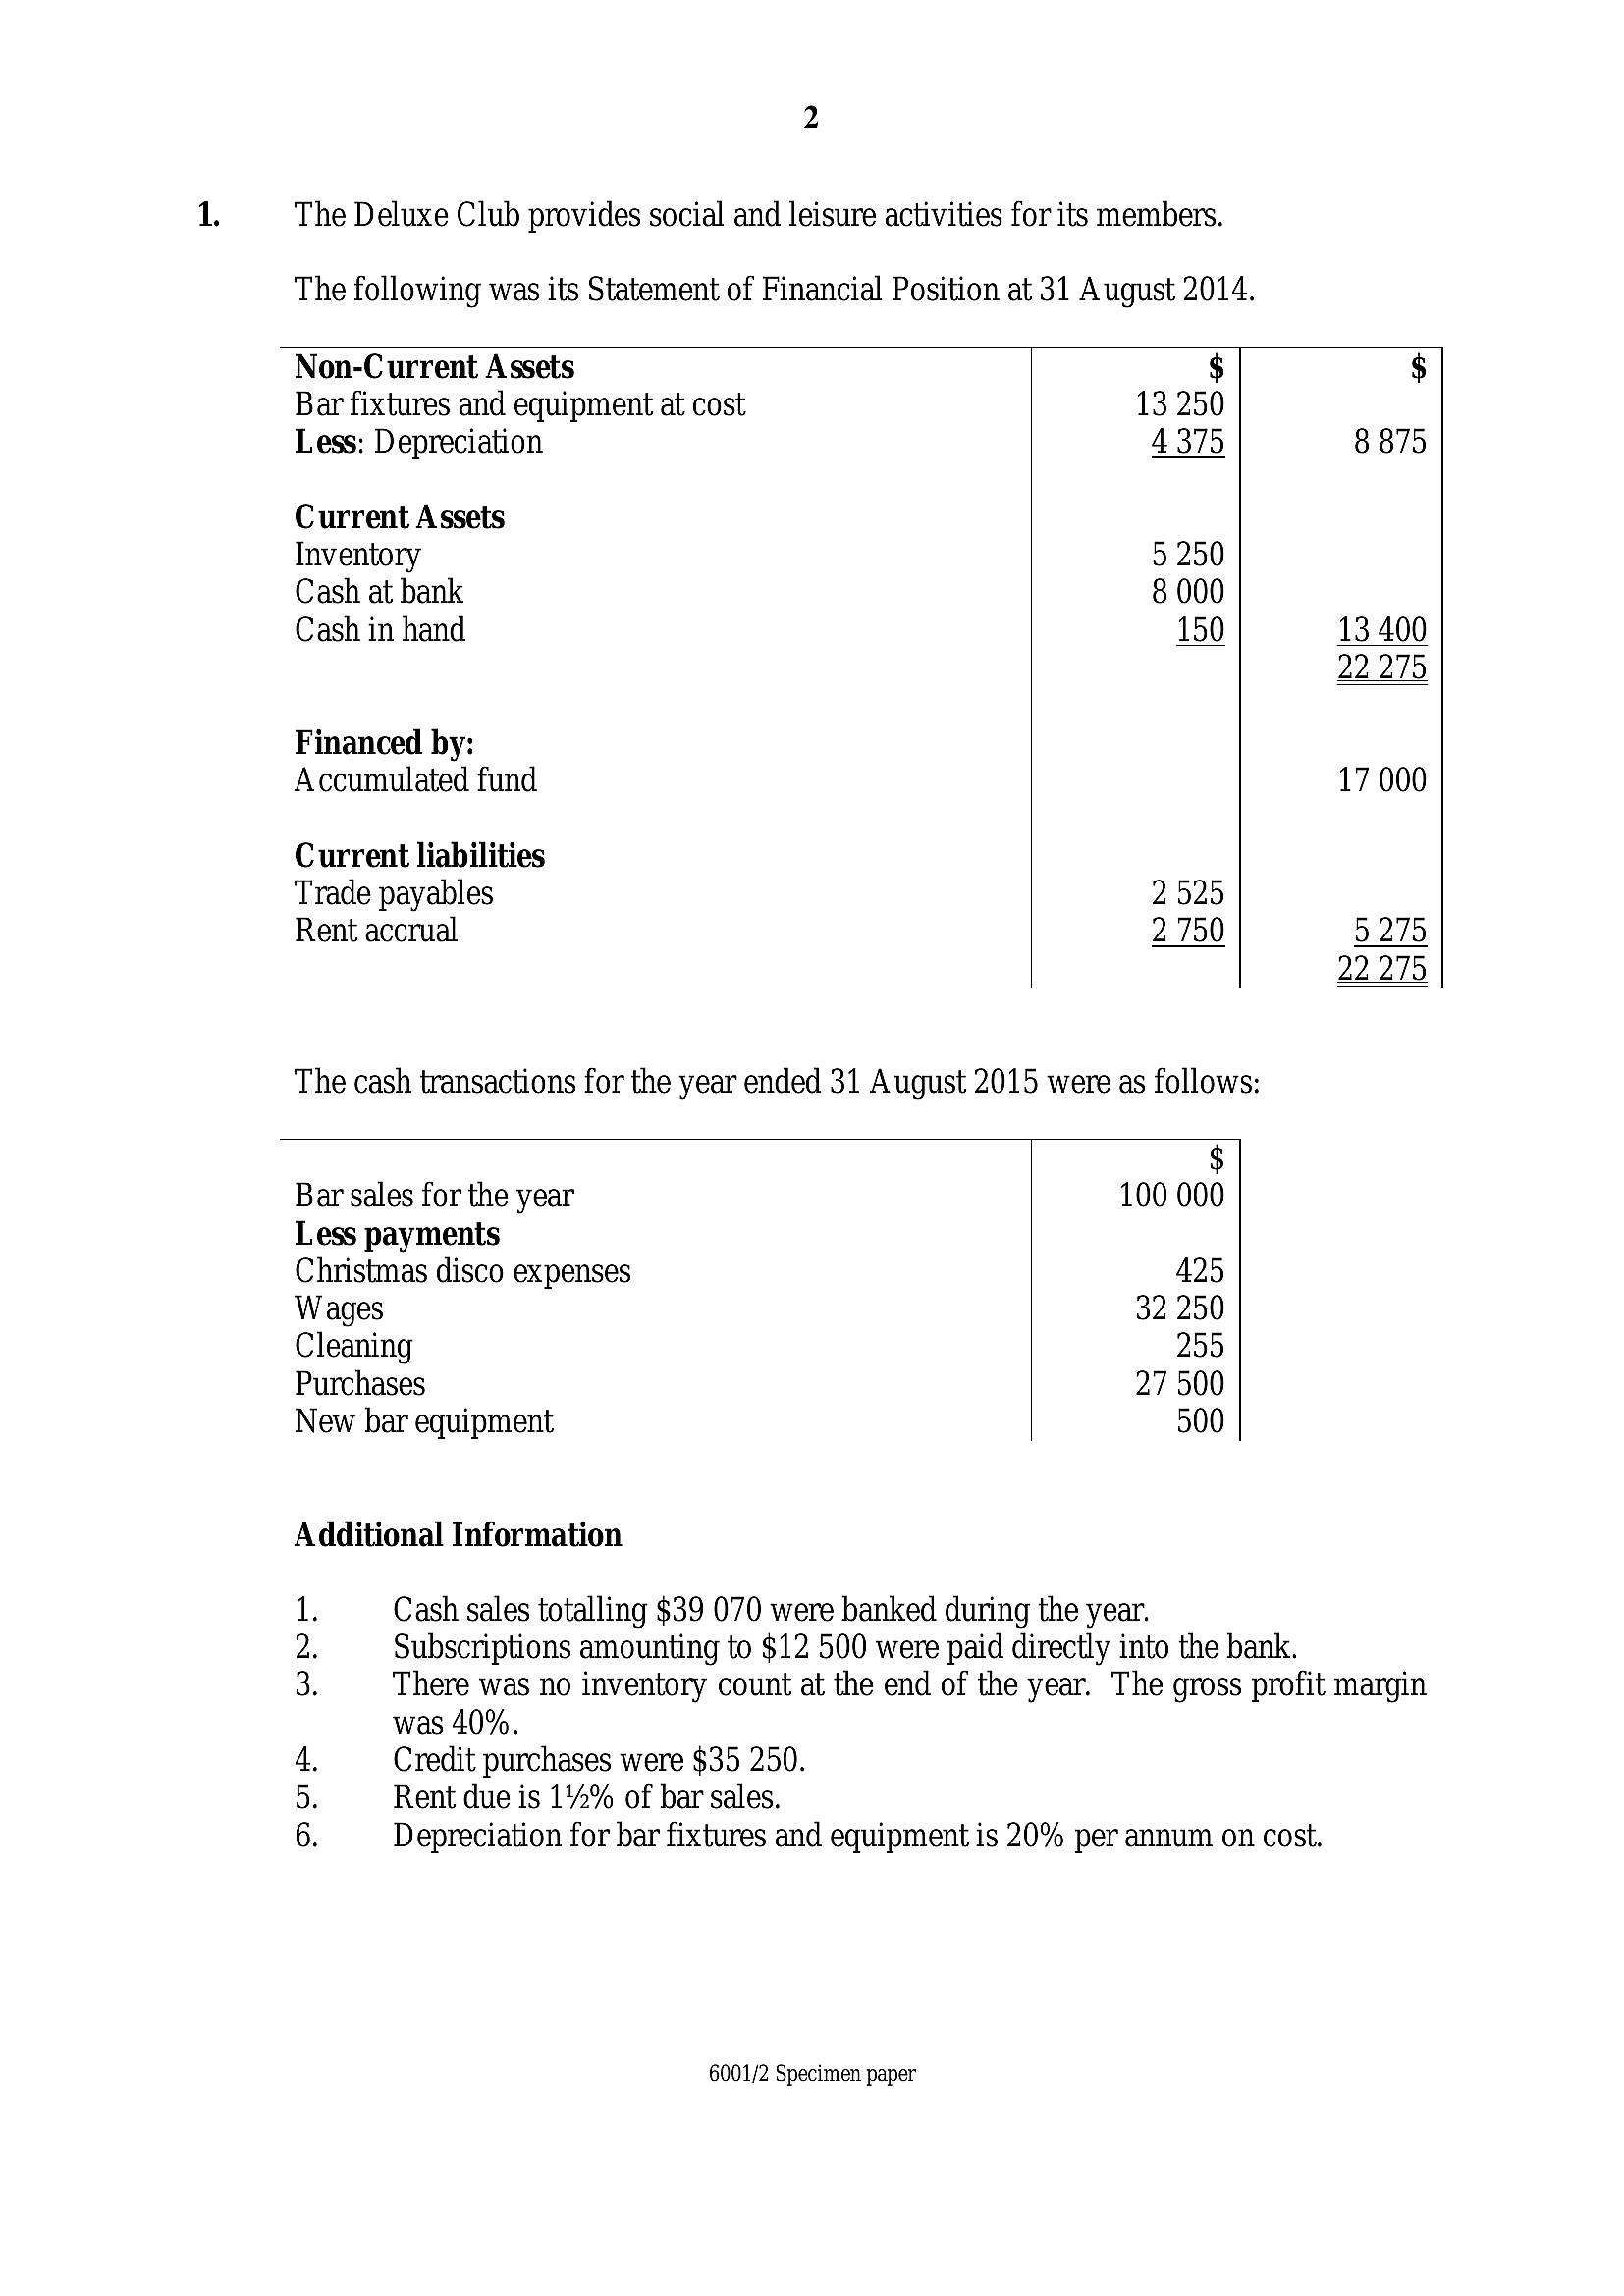
The Deluxe Club provides social and leisure activities for its members.[he following was its Statement of Financial Position at 31 August 2014.
Non-C urrent Assets
Bar fixtures and equipment at cost
Less: Depreciation
Current Assets
Inventory
Cash at bank
Cash in hand
Financed by:
Accumulated fund
Current liabilities
Trade payables
Rent accrual
The cash transactions for the year ended 31 August 2015 were as follows:
$
13 250
4375
5 250
8 000
150
2525
2750
Bar sales for the year
Less payments
Christmas disco expenses
Wages
Cleaning
Purchases
New bar equipment
Additional Information
$
100 000
425
32 250
255
27 500
500
Cash sales totalling $39 070 were banked during the year.
1.
2. Subscriptions amounting to $12 500 were paid directly into the bank.
3
There was no inventory count at the end of the year. The gross profit margin
was 40%.
4. Credit purchases were $35 250.
Rent due is 12% of bar sales.
go
6. Depreciation for bar fixtures and equipment is 20% per annum on cost.
6001/2 Specimen paper
---
Page 3
Extracted Text
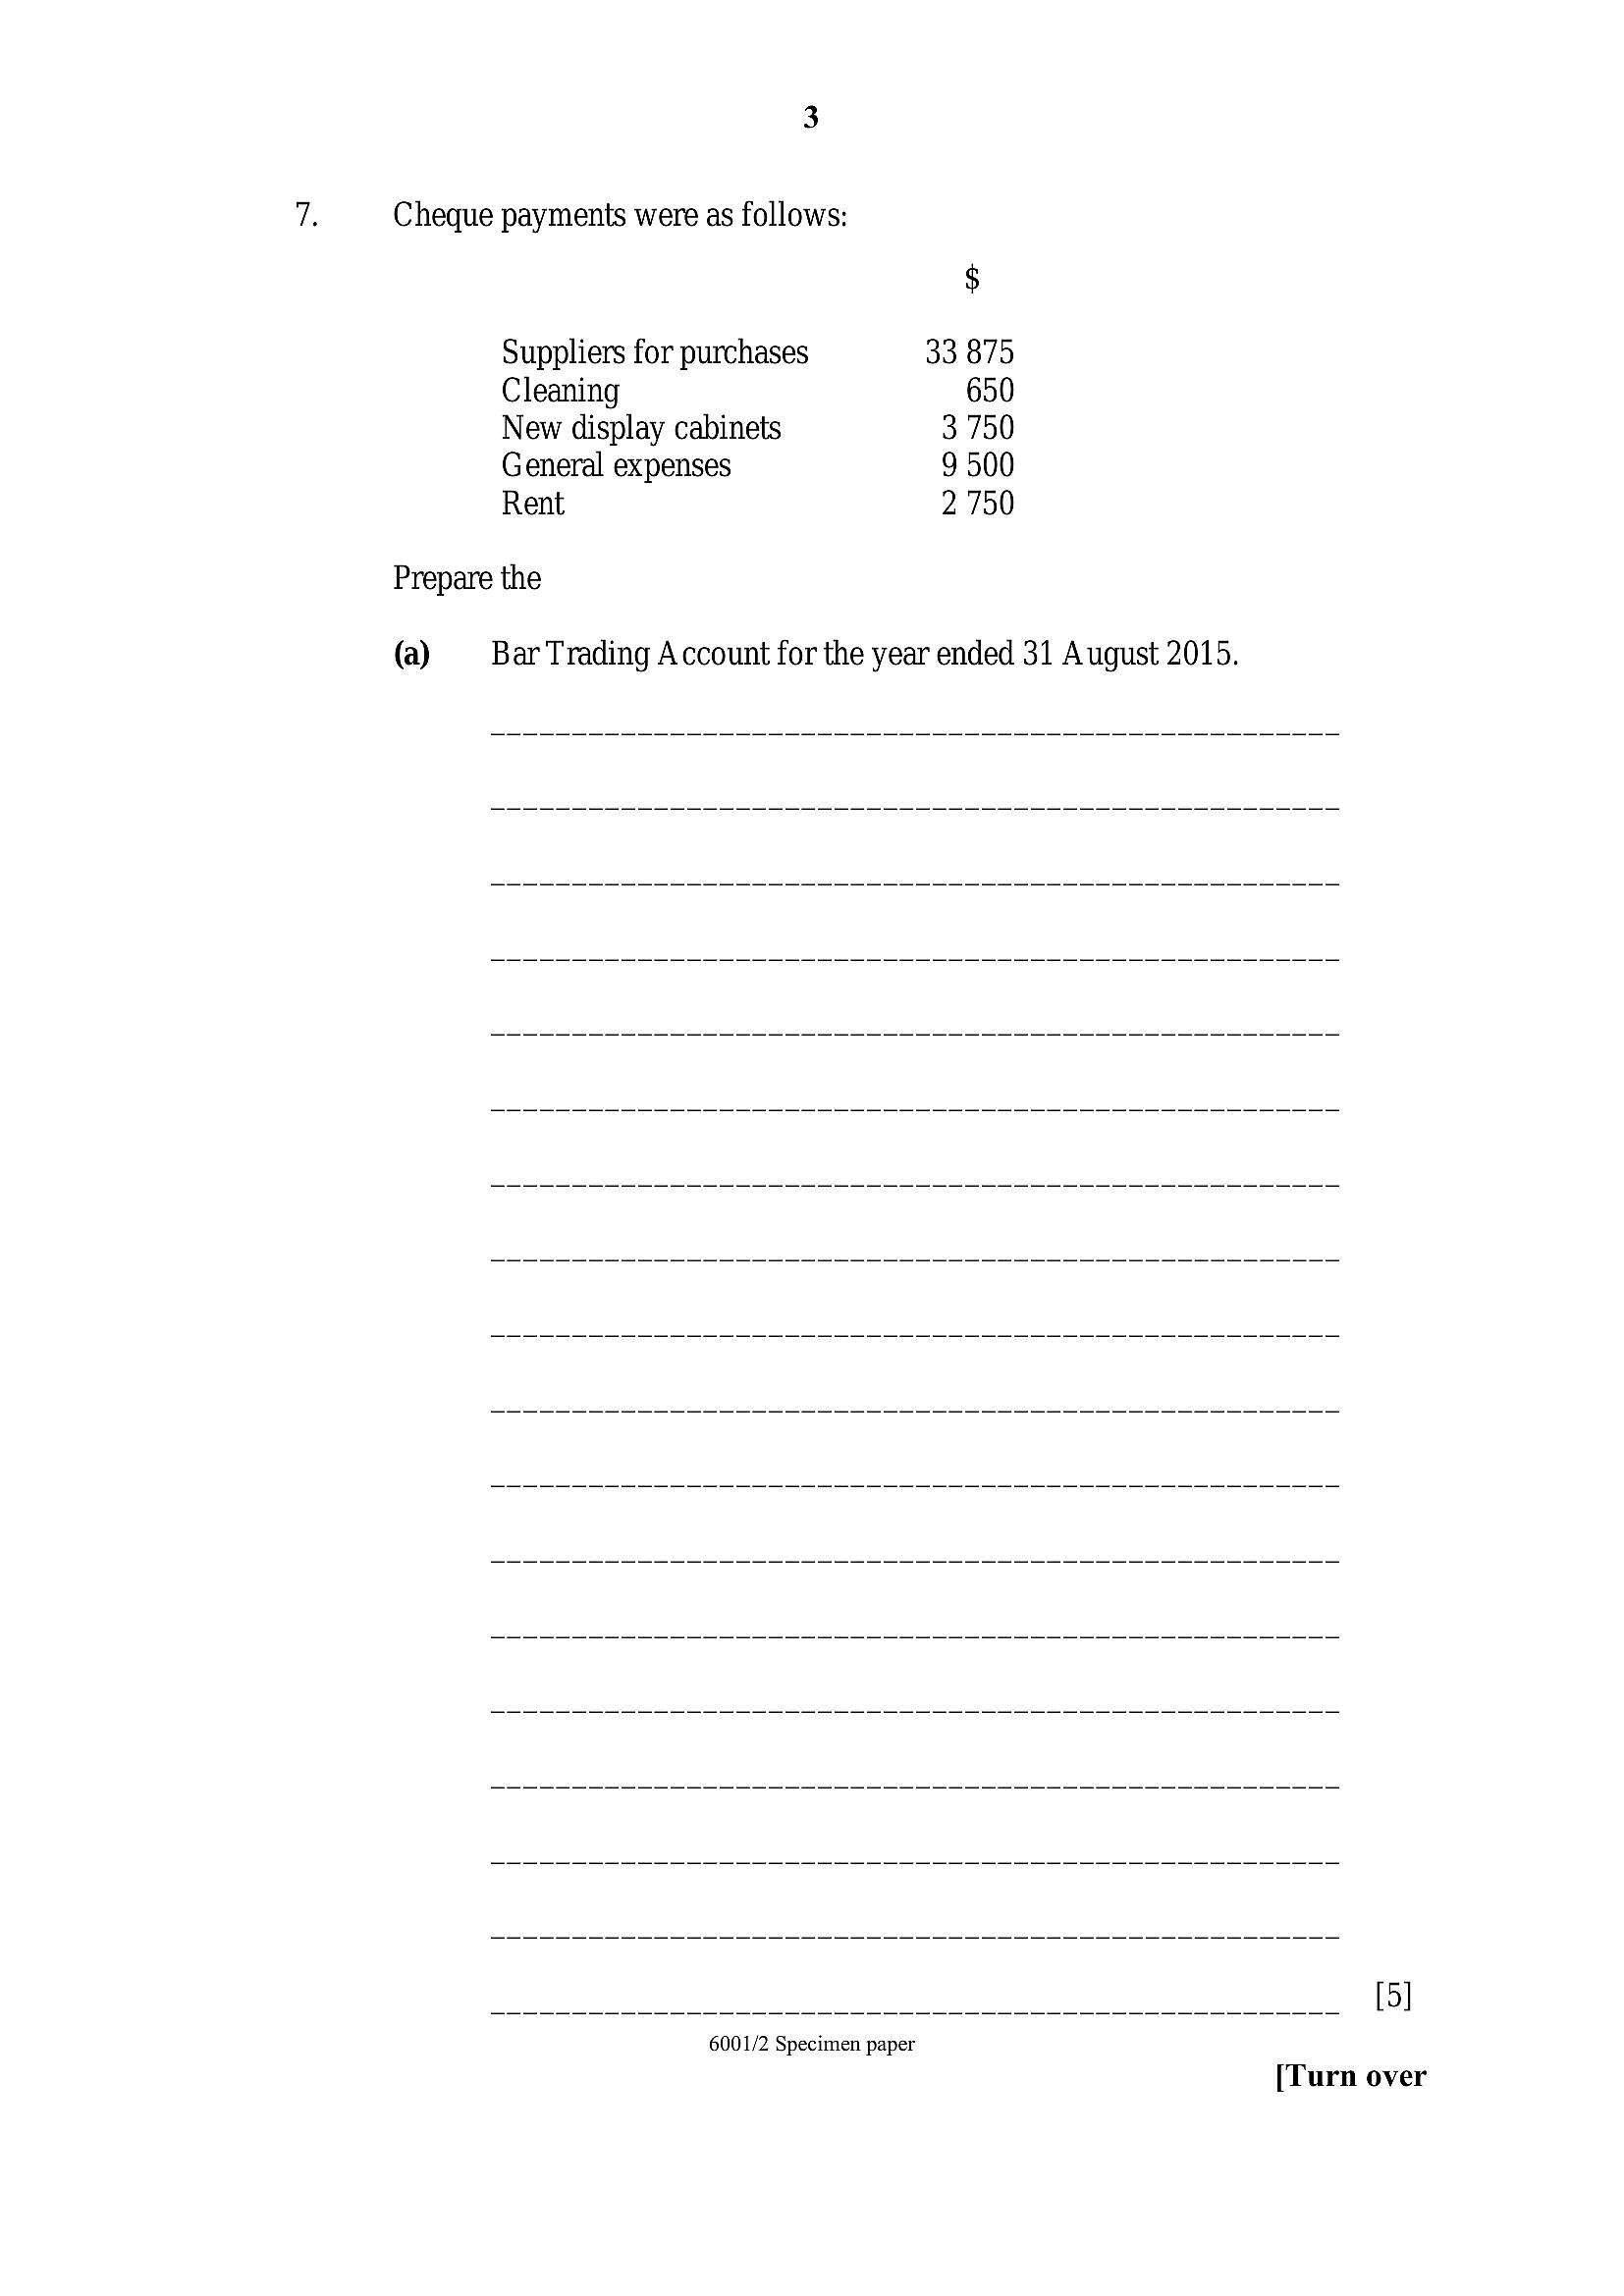
7. Cheque payments were as follows: $ Suppliers for purchases 33 875 Cleaning 650 New display cabinets 3 750 General expenses 9 500 Rent 2750 Prepare the(a) —‘BarTrading Account for the year ended 31 August 2015.
6001/2 Specimen paper
[Turn over
---
Page 4
Extracted Text
(b) =‘ Income and Expenditure Account for the year ended 31 August 2015.6001/2 Specimen paper
---
Page 5
Extracted Text
(© Statement of Financial Position as at 31 August 2015.6001/2 Specimen paper
[Turn over
---
Page 6
Extracted Text
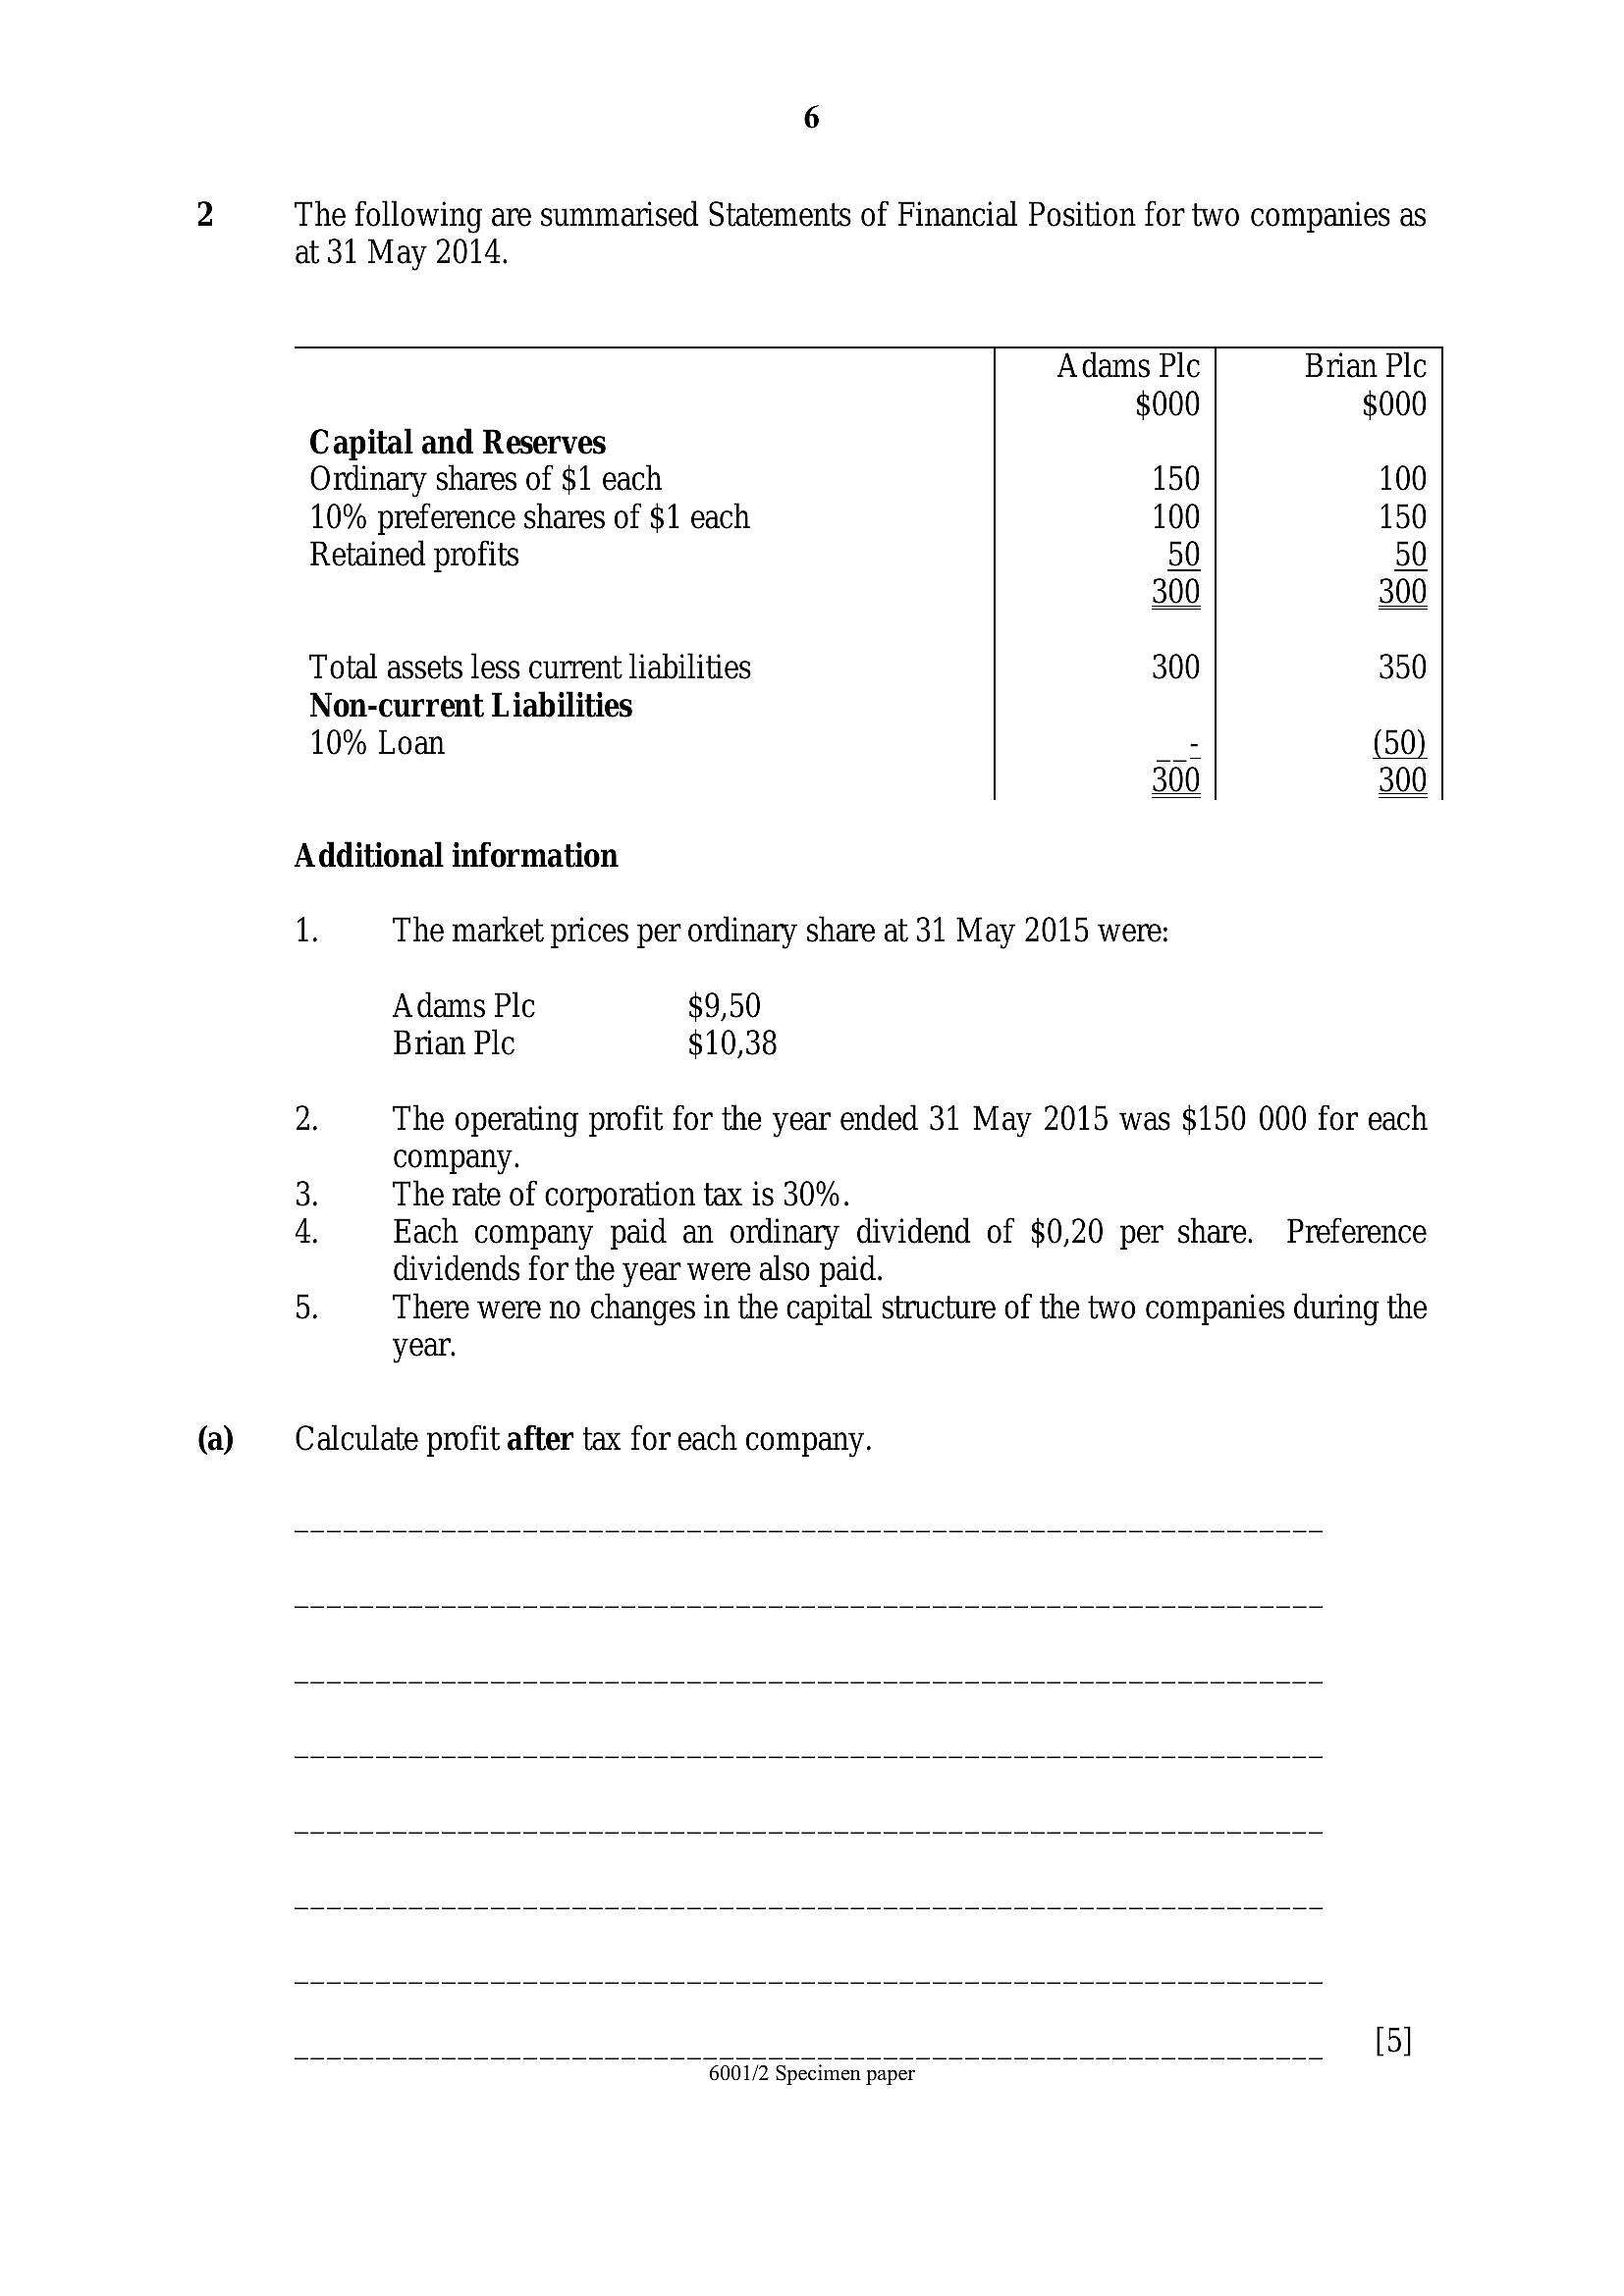
2(a)
The following are summarised Statements of Financial Position for two companies as
at 31 May 2014.
Adams Plc Brian Plc
$000 $000
Capital and Reserves
Ordinary shares of $1 each 150 100
10% preference shares of $1 each 100 150
Retained profits 50 50
300 300
Total assets less current liabilities 300 350
Non-current Liabilities
10% Loan _- (50)
300 300
Additional information
1. The market prices per ordinary share at 31 May 2015 were:
Adams Plc $9,50
Brian Plc $10,38
The operating profit for the year ended 31 May 2015 was $150 000 for each
company.
The rate of corporation tax is 30%.
Each company paid an ordinary dividend of $0,20 per share. Preference
dividends for the year were also paid.
There were no changes in the capital structure of the two companies during the
year.
Calculate profit after tax for each company.
6001/2 Specimen paper
---
Page 7
Extracted Text
(b) ~— Calculate the following accounting ratios for each company: (1) earnings per share, (ii) price earnings, (iii) gearing (taken as total borrowings to ordinary shareholders’ funds),6001/2 Specimen paper
[Turn over
---
Page 8
Extracted Text
©(iv) dividend yield,
6001/2 Specimen paper
---
Page 9
Extracted Text
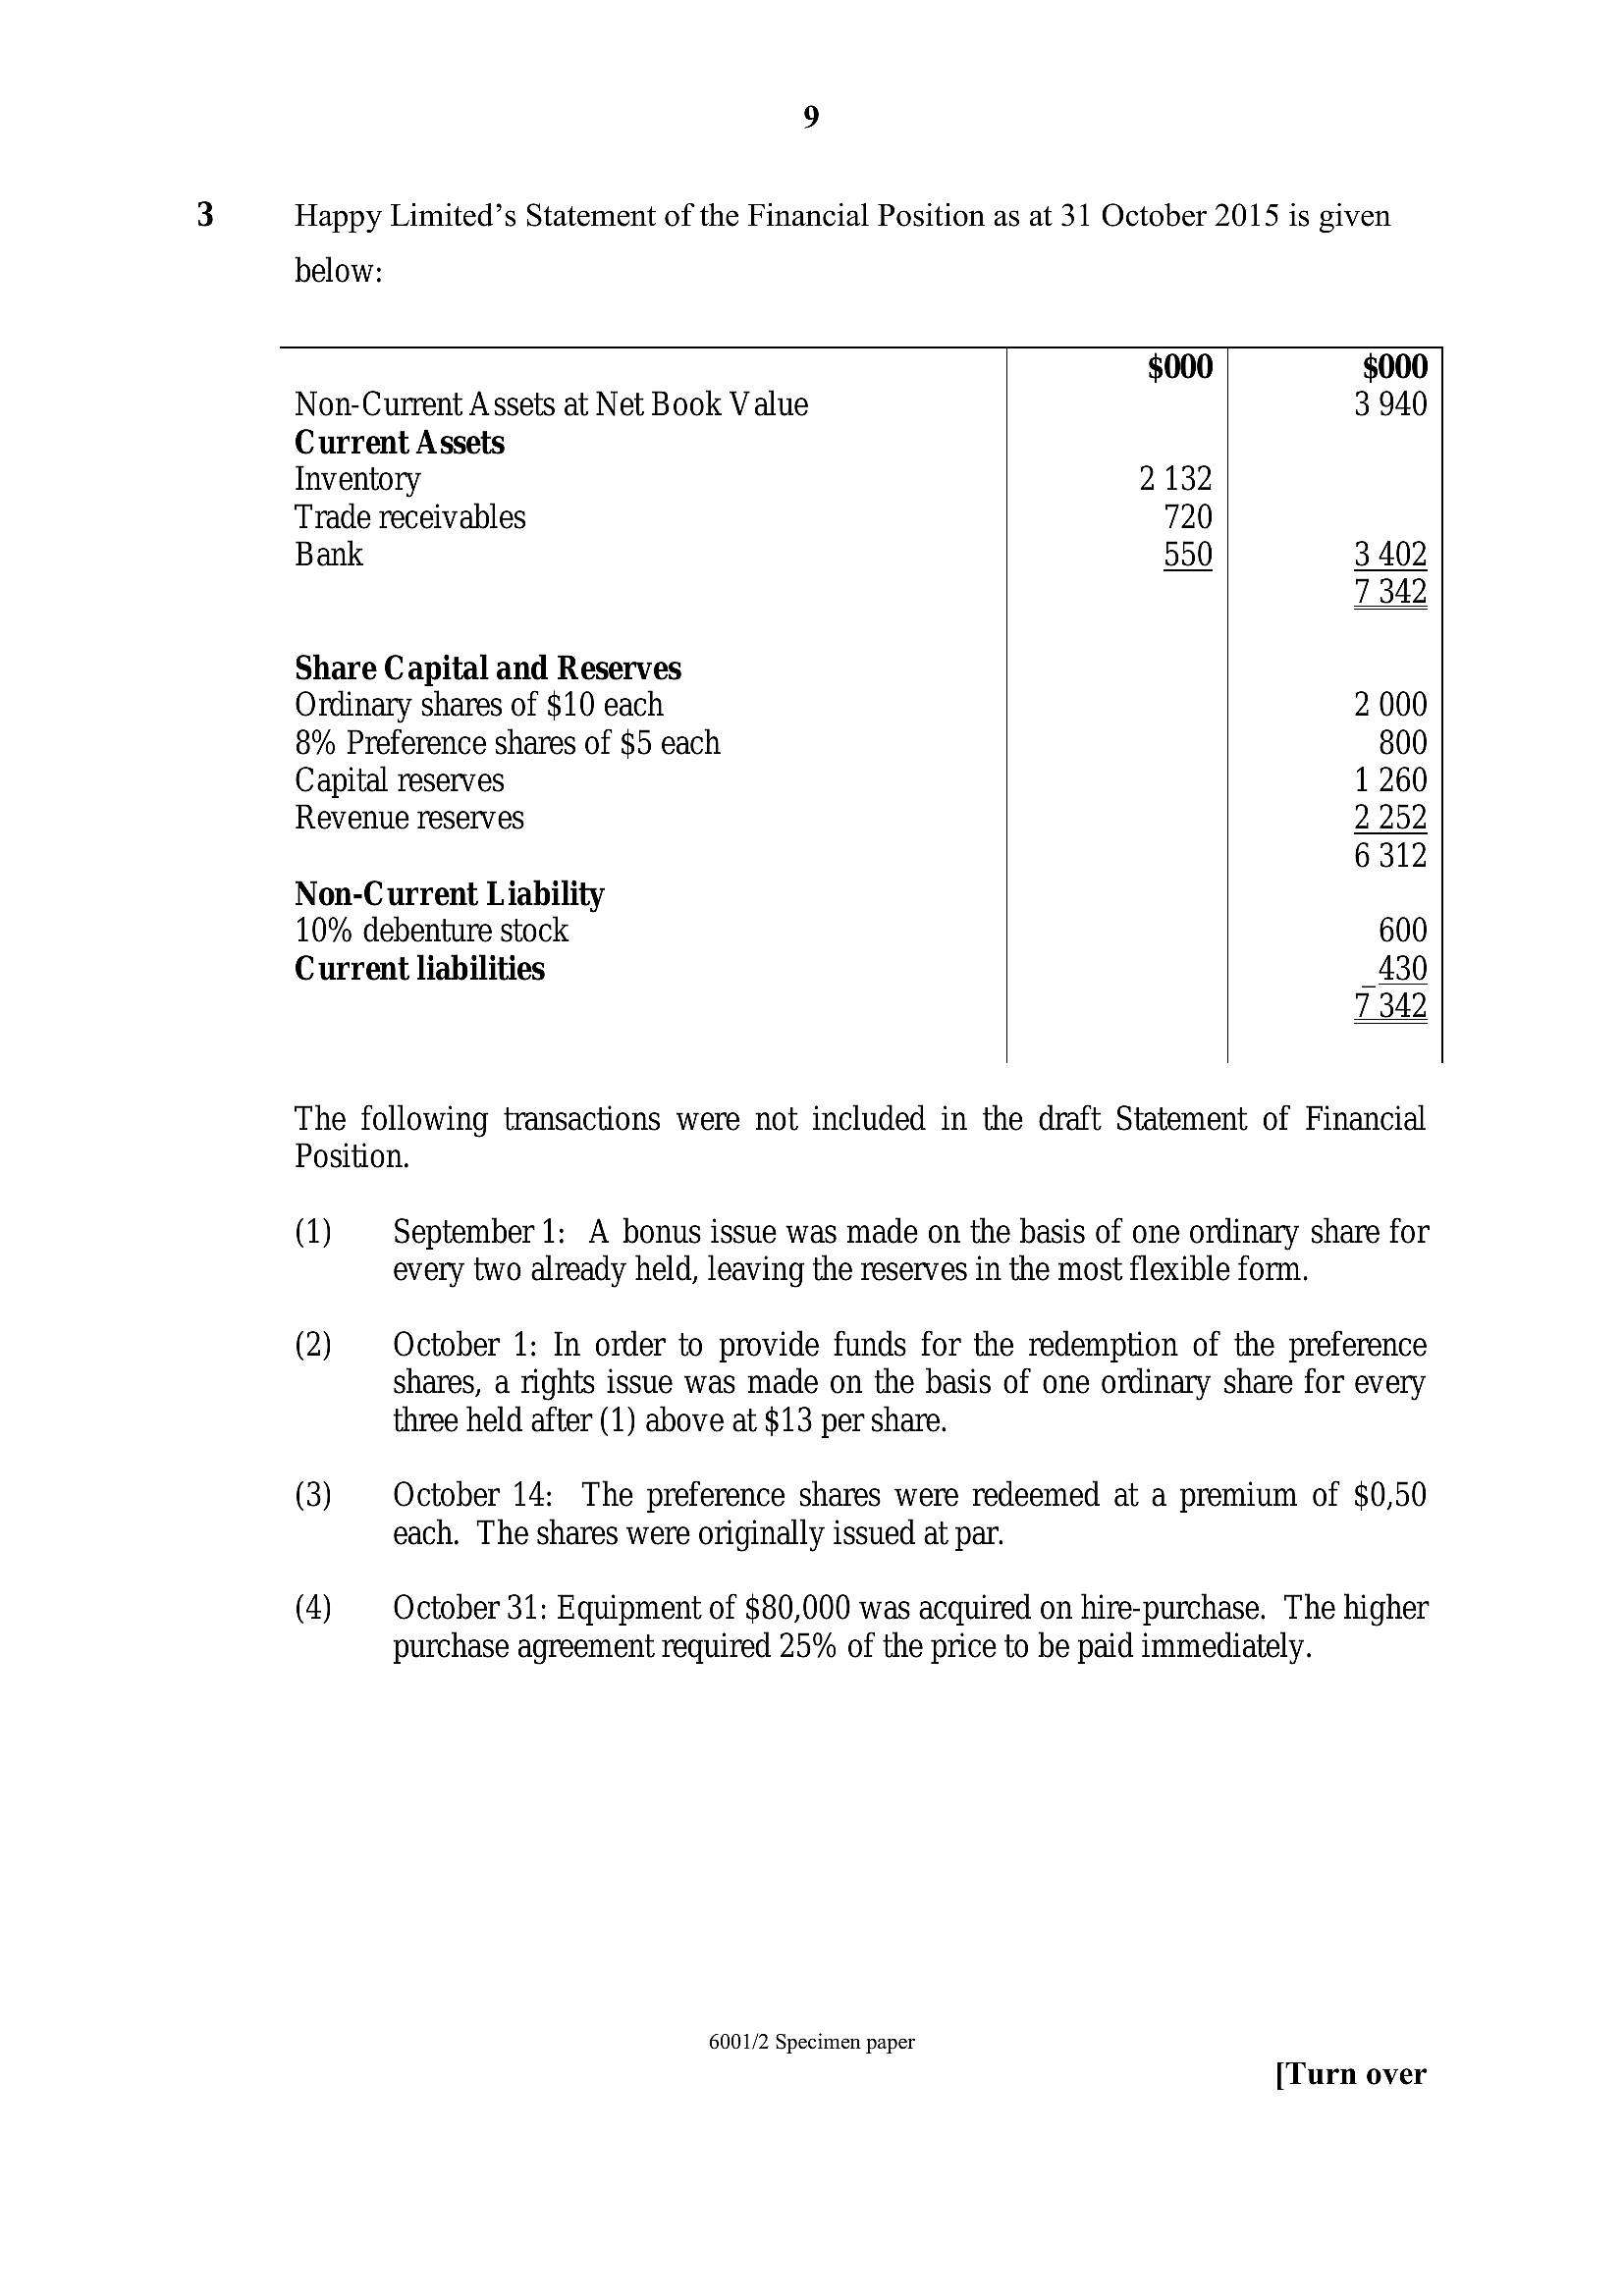
Happy Limited’s Statement of the Financial Position as at 31 October 2015 is givenbelow:
Non-Current Assets at Net Book Value
Current Assets
Inventory
Trade receivables
Bank
Share Capital and Reserves
Ordinary shares of $10 each
8% Preference shares of $5 each
Capital reserves
Revenue reserves
Non-C urrent Liability
10% debenture stock
Current liabilities
$000
2 132
720
550
$000
3 940
1 260
2.252
6 312
600
430
7.342
The following transactions were not included in the draft Statement of Financial
Position.
(1) September 1: A bonus issue was made on the basis of one ordinary share for
every two already held, leaving the reserves in the most flexible form.
(2) October 1: In order to provide funds for the redemption of the preference
shares, a rights issue was made on the basis of one ordinary share for every
three held after (1) above at $13 per share.
(3) October 14: The preference shares were redeemed at a premium of $0,50
each. The shares were originally issued at par.
(4) October 31: Equipment of $80,000 was acquired on hire-purchase. The higher
purchase agreement required 25% of the price to be paid immediately.
6001/2 Specimen paper
[Turn over
---
Page 10
Extracted Text
10(a) Redraft the Statement of Financial Position as at 31 October 2015 after
transaction 1 to 4 have been recorded.
6001/2 Specimen paper
---
Page 11
Extracted Text
11(b) Explain two advantages of a rights issue over a public issue of shares to a shareholder.
(©) Distinguish between ordinary shares and debentures.
6001/2 Specimen paper
[Turn over
---
Page 12
Extracted Text
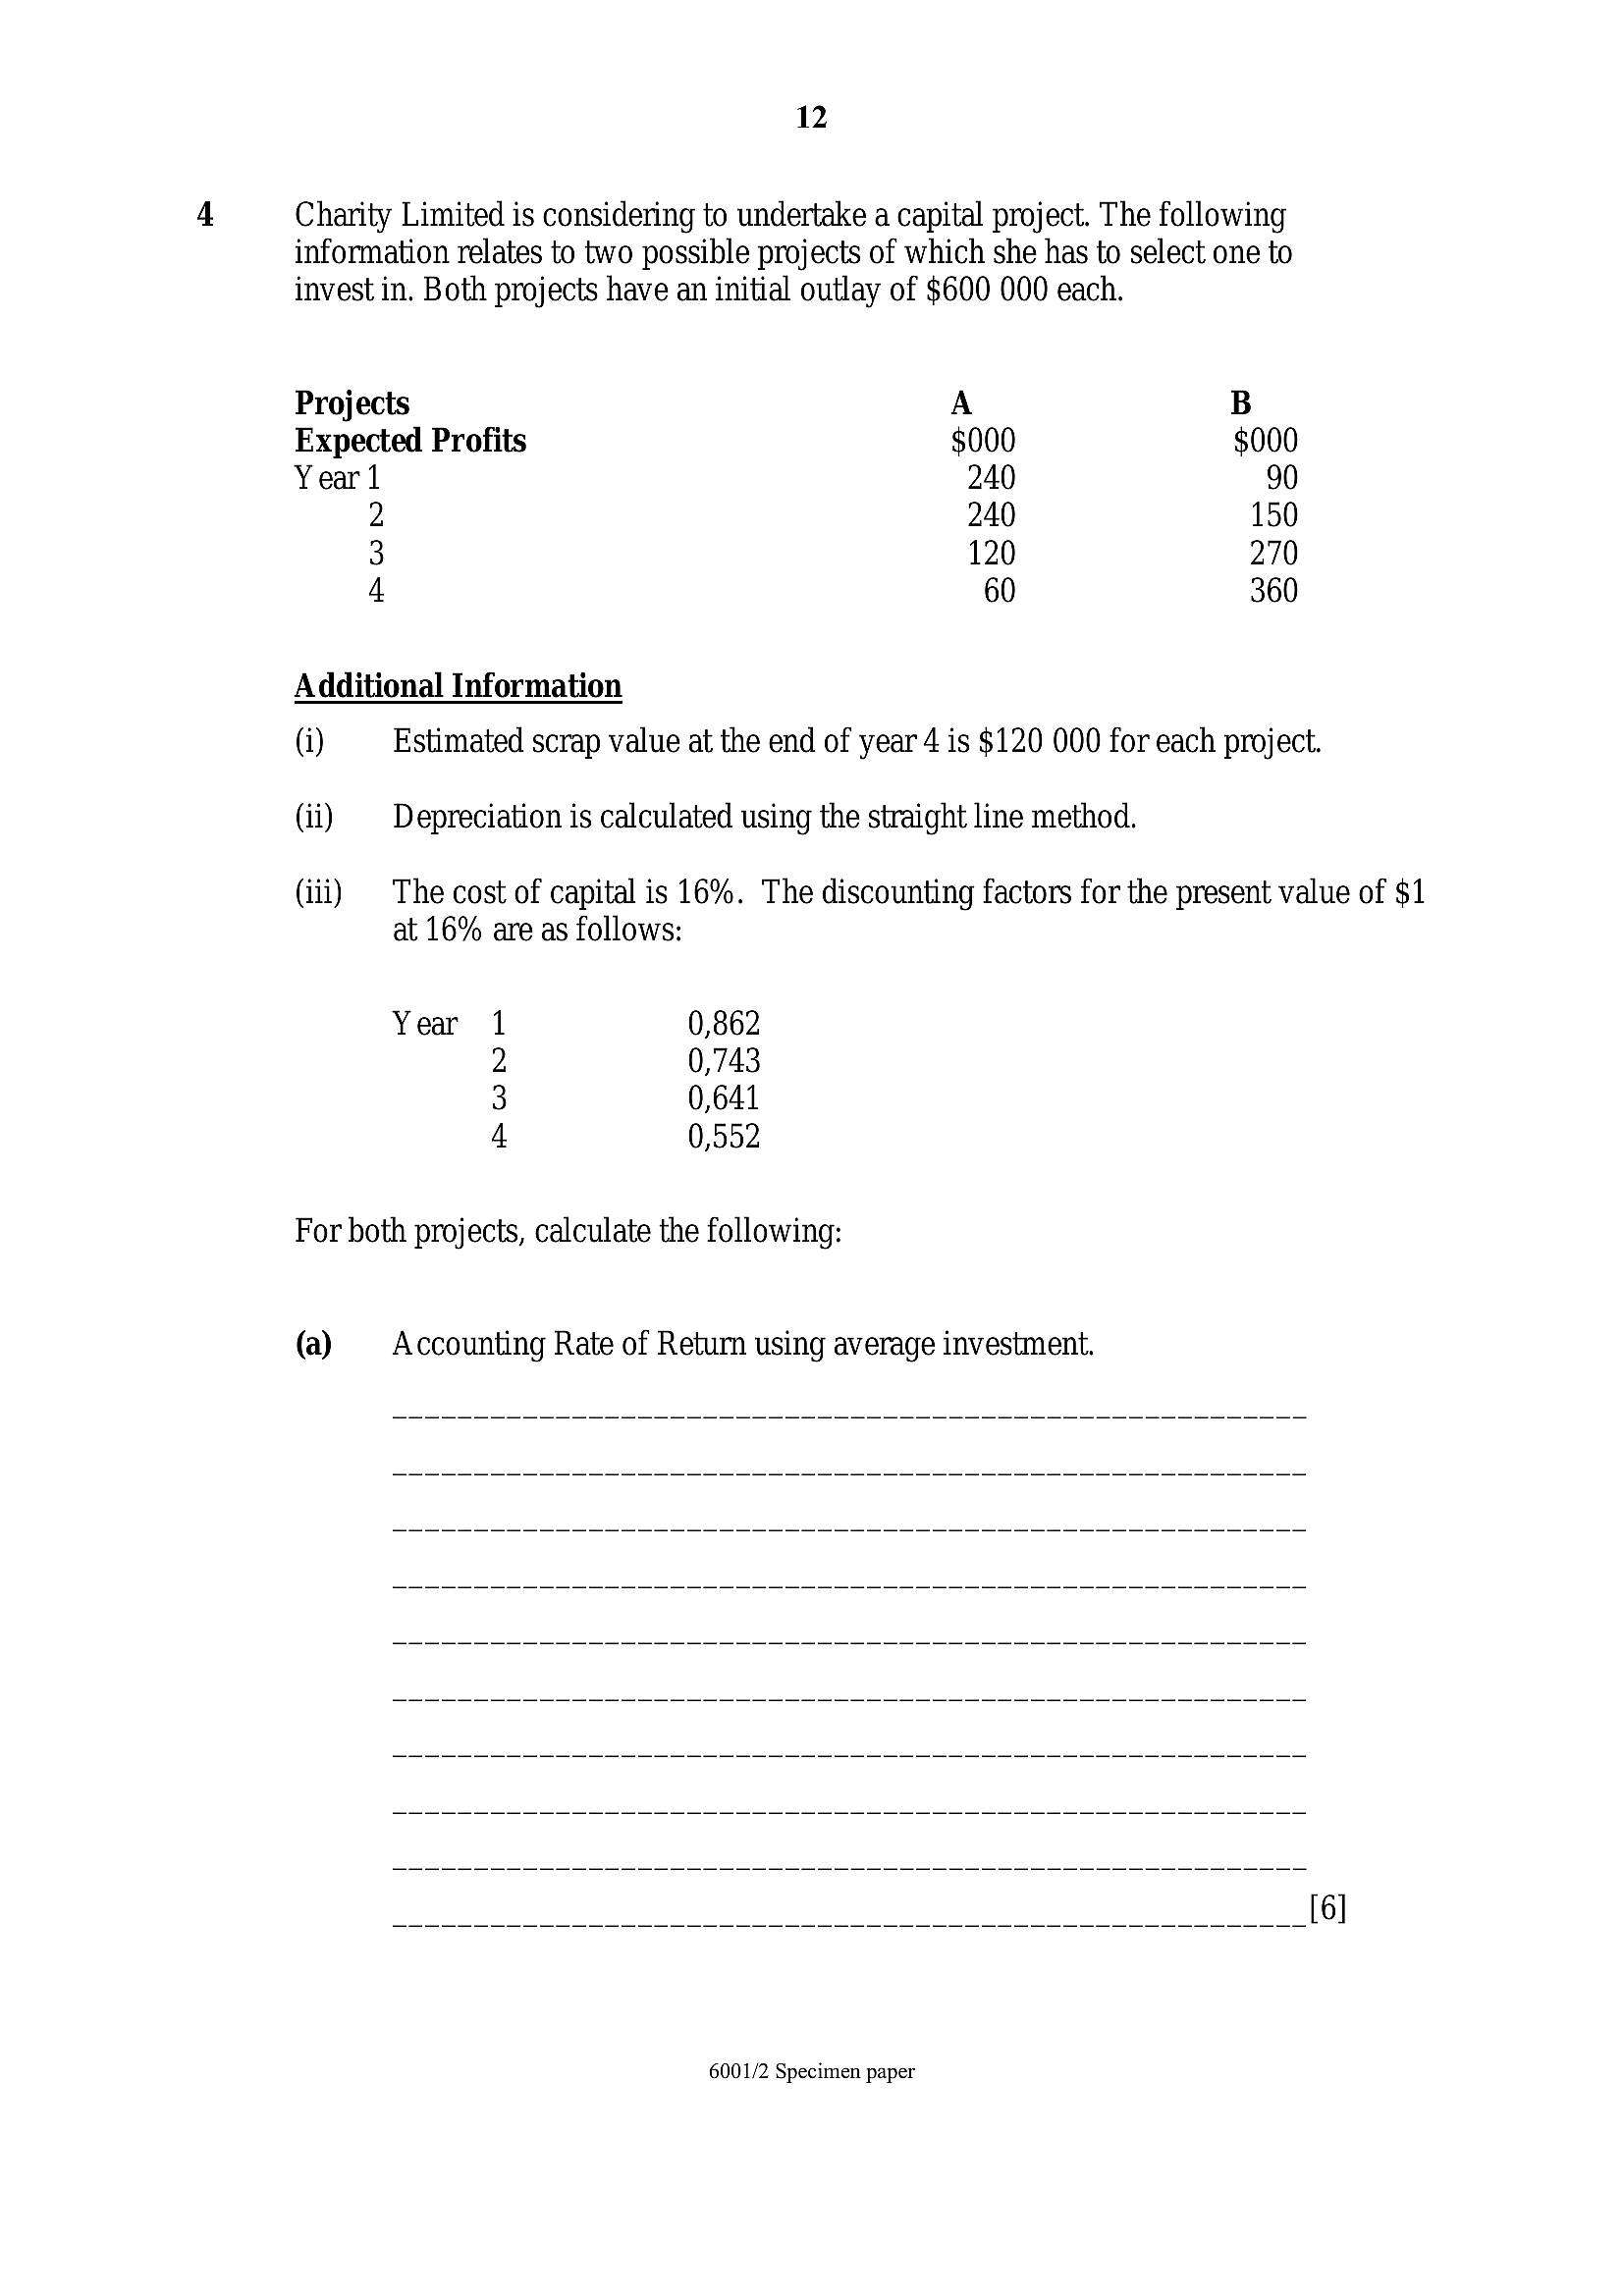
12Charity Limited is considering to undertake a capital project. The following
information relates to two possible projects of which she has to select one to
invest in. Both projects have an initial outlay of $600 000 each.
Projects A B
Expected Profits $000 $000
Year 1 240 90
2 240 150
3 120 270
4 60 360
Additional Information
(i) Estimated scrap value at the end of year 4 is $120 000 for each project.
(ii) | Depreciation is calculated using the straight line method.
(iii) | The cost of capital is 16%. The discounting factors for the present value of $1
at 16% are as follows:
Year 1 0,862
2 0,743
3 0,641
4 0,552
For both projects, calculate the following:
(a) Accounting Rate of Return using average investment.
6001/2 Specimen paper
---
Page 13
Extracted Text
13(b) Payback period.
(©) Net Present Value.
6001/2 Specimen paper
[Turn over
---
Page 14
Extracted Text
14(d) Advise Charity Limited with reasons which project should be undertaken
using calculations in (c) above.
6001/2 Specimen paper
---
Page 15
Extracted Text
15BLANK PAGE
6001/2 Specimen paper
---
Page 16
Extracted Text
16BLANK PAGE
6001/2 Specimen paper
---