📄 Exam Questions & Readable Text Transcript
Full OCR-extracted text of questions, syllabus codes, and exam instructions.
Extracted Content: 4051q02
Page 1
Extracted Text
Surname Forename(s) Centre Number Candidate NumberC )
For Performance Measurement
ZIMBABWE SCHOOL EXAMINATIONS COUNCIL
General Certificate of Education Ordinary Level
PRINCIPLES OF ACCOUNTING 4051/2
PAPER 2
SPECIMEN PAPER 2 hours 30 minutes
Allow candidates 5 minutes to count pages before the examination.
TIME: 2 hours 30 minutes
INSTRUCTIONS TO CANDIDATES
Check that all the pages are in the booklet and ask the invigilator for a replacement if there are duplicate
or missing pages.
Write your name, (Summame and Forename(s)), centre number and candidate number in the spaces
provided at the top of this page and your centre number and candidate number in the box at the top right
comer of every page of this paper.
Answer all questions.
Write your answers in the spaces provided on the question paper.
Use black or blue ball-point pen only.
All calculations must be shown adjacent to the answer.
Calculators may be used.
INFORMATION FOR CANDIDATES
The number of marks is given in brackets [ ] at the end of each question or part question.
Amounts used in this Question Paper are for calculation purposes only.
The businesses described in this paper are entirely fictitious.
This question paper consists of 22 printed pages and 2 blank pages.
Copyright: Zimbabwe School Examinations Council, Specimen paper.
@ZIMSEC Specimen paper [Turn over
---
Page 2
Extracted Text
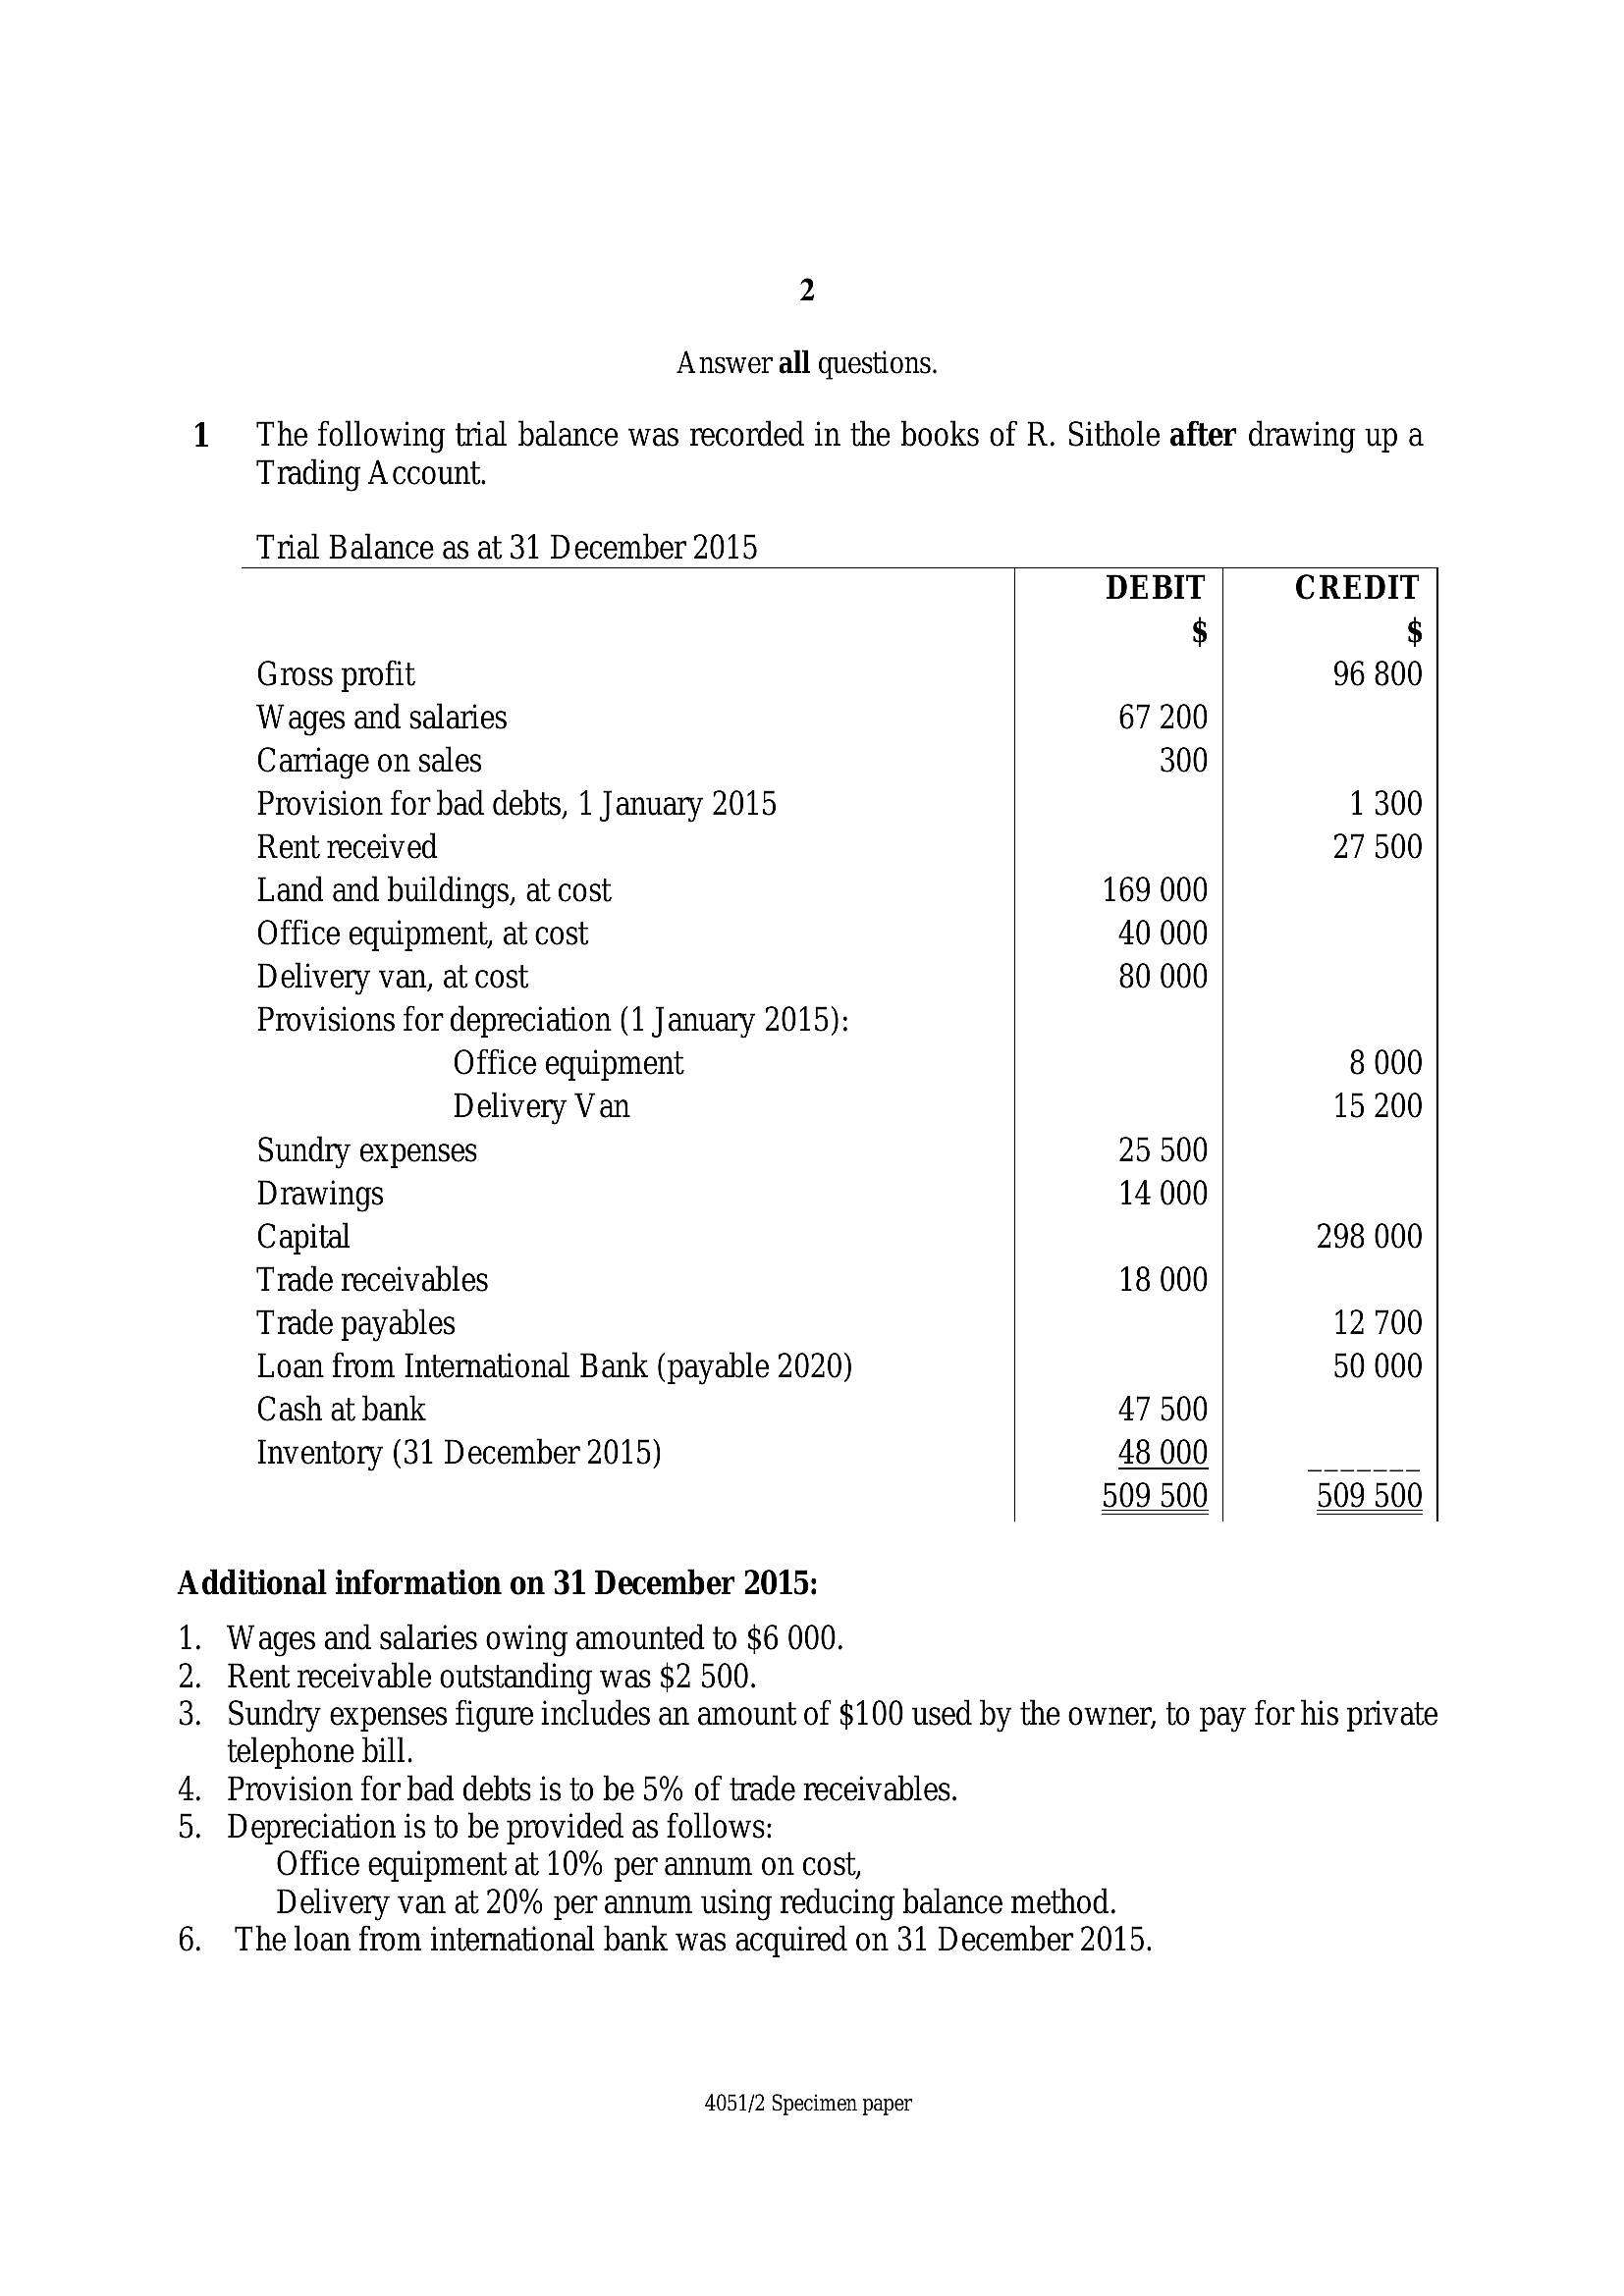
2 Answer all questions.1 The following trial balance was recorded in the books of R. Sithole after drawing up a
Trading Account.
Trial Balance as at 31 December 2015
DEBIT CREDIT
$ $
Gross profit 96 800
Wages and salaries 67 200
Carriage on sales 300
Provision for bad debts, 1 January 2015 1300
Rent received 27500
Land and buildings, at cost 169 000
Office equipment, at cost 40 000
Delivery van, at cost 80 000
Provisions for depreciation (1 January 2015):
Office equipment 8 000
Delivery Van 15 200
Sundry expenses 25 500
Drawings 14 000
Capital 298 000
Trade receivables 18 000
Trade payables 12 700
Loan from International Bank (payable 2020) 50 000
Cash at bank 47 500
Inventory (31 December 2015) 48000;
509 500 509 500
Additional information on 31 December 2015:
1. Wages and salaries owing amounted to $6 000.
2. Rent receivable outstanding was $2 500.
3. Sundry expenses figure includes an amount of $100 used by the owner, to pay for his private
telephone bill.
4, Provision for bad debts is to be 5% of trade receivables.
5. Depreciation is to be provided as follows:
Office equipment at 10% per annum on cost,
Delivery van at 20% per annum using reducing balance method.
6. The loan from international bank was acquired on 31 December 2015.
4051/2 Specimen paper
---
Page 3
Extracted Text
Y ou are required to prepare:(a) AnIncome Statement/Profit and Loss Account for the year ended
31 December 2015
4051/2 Specimen paper
[Turn over
---
Page 4
Extracted Text
4051/2 Specimen paper---
Page 5
Extracted Text
5(b) _ A statement of financial Position as at 31 December 2015.
4051/2 Specimen paper
[Turn over
---
Page 6
Extracted Text
4051/2 Specimen paper---
Page 7
Extracted Text
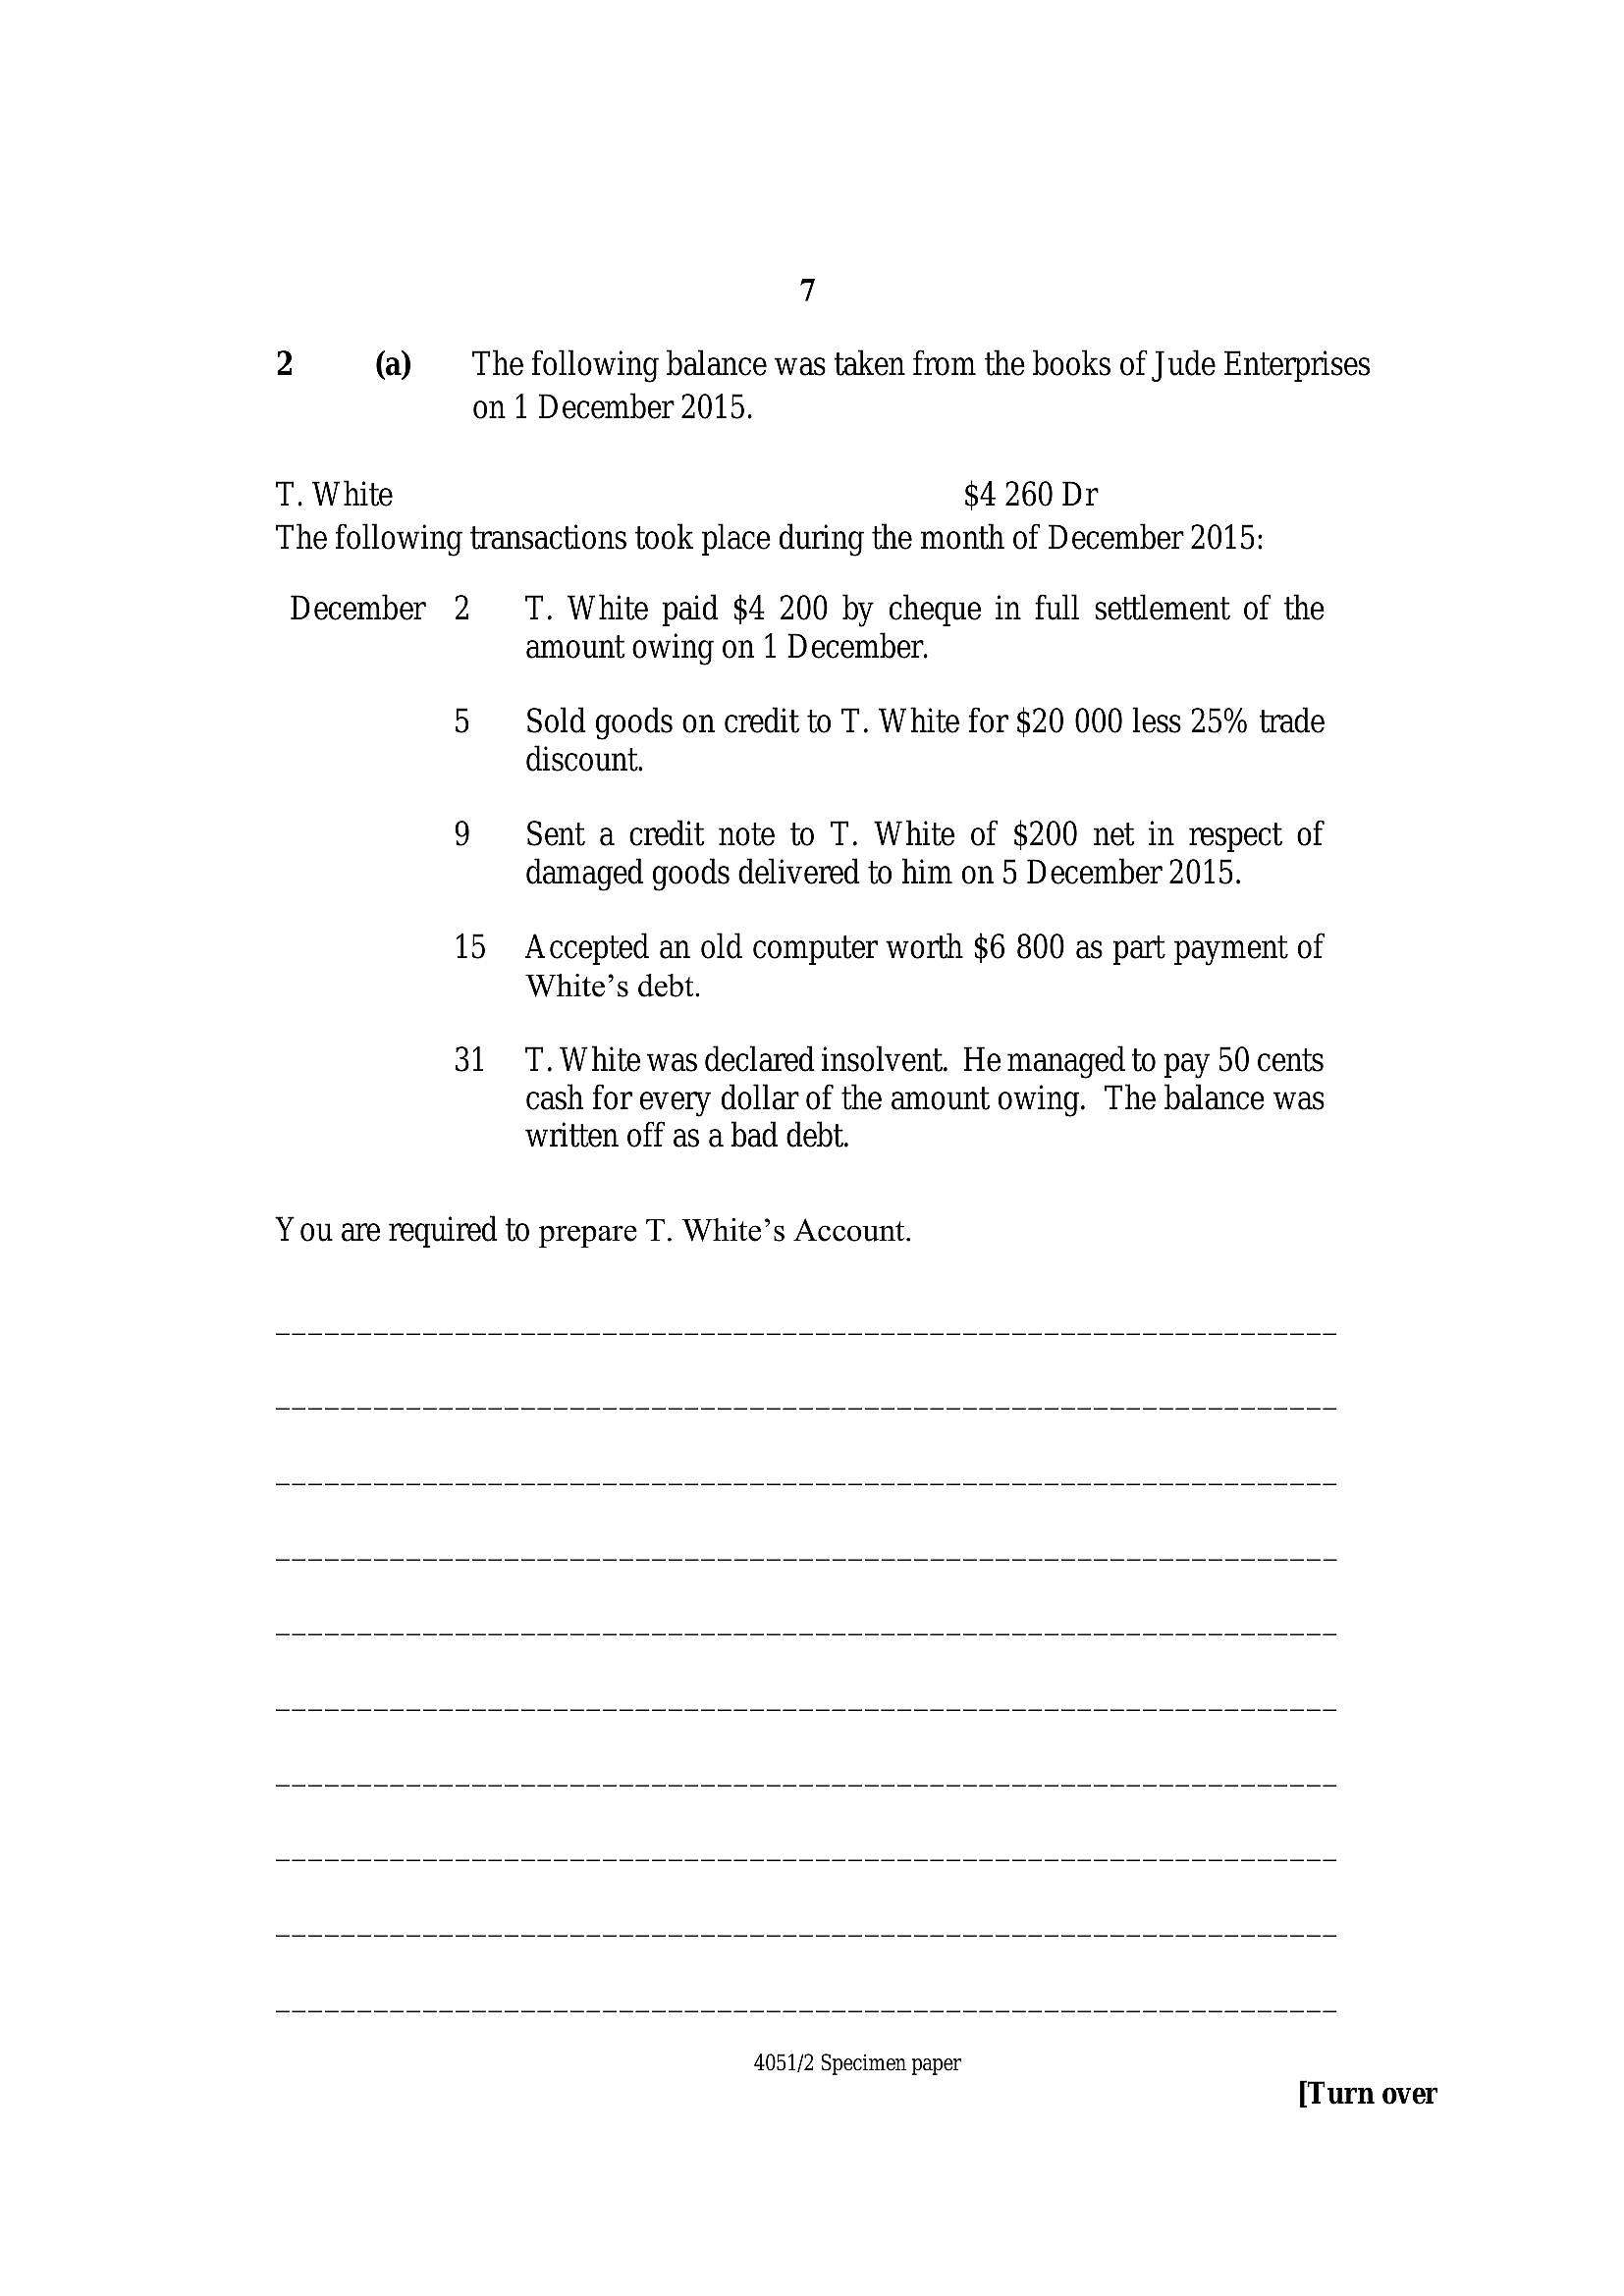
72 (a) ‘The following balance was taken from the books of Jude Enterprises
on 1 December 2015.
T. White $4 260 Dr
The following transactions took place during the month of December 2015:
December 2 TT. White paid $4 200 by cheque in full settlement of the
amount owing on 1 December.
5 Sold goods on credit to T. White for $20 000 less 25% trade
discount.
9 Sent a credit note to T. White of $200 net in respect of
damaged goods delivered to him on 5 December 2015.
15 Accepted an old computer worth $6 800 as part payment of
White’s debt.
31 T. White was declared insolvent. He managed to pay 50 cents
cash for every dollar of the amount owing. The balance was
written off as a bad debt.
Y ou are required to prepare T. White’s Account.
4051/2 Specimen paper
[Turn over
---
Page 8
Extracted Text
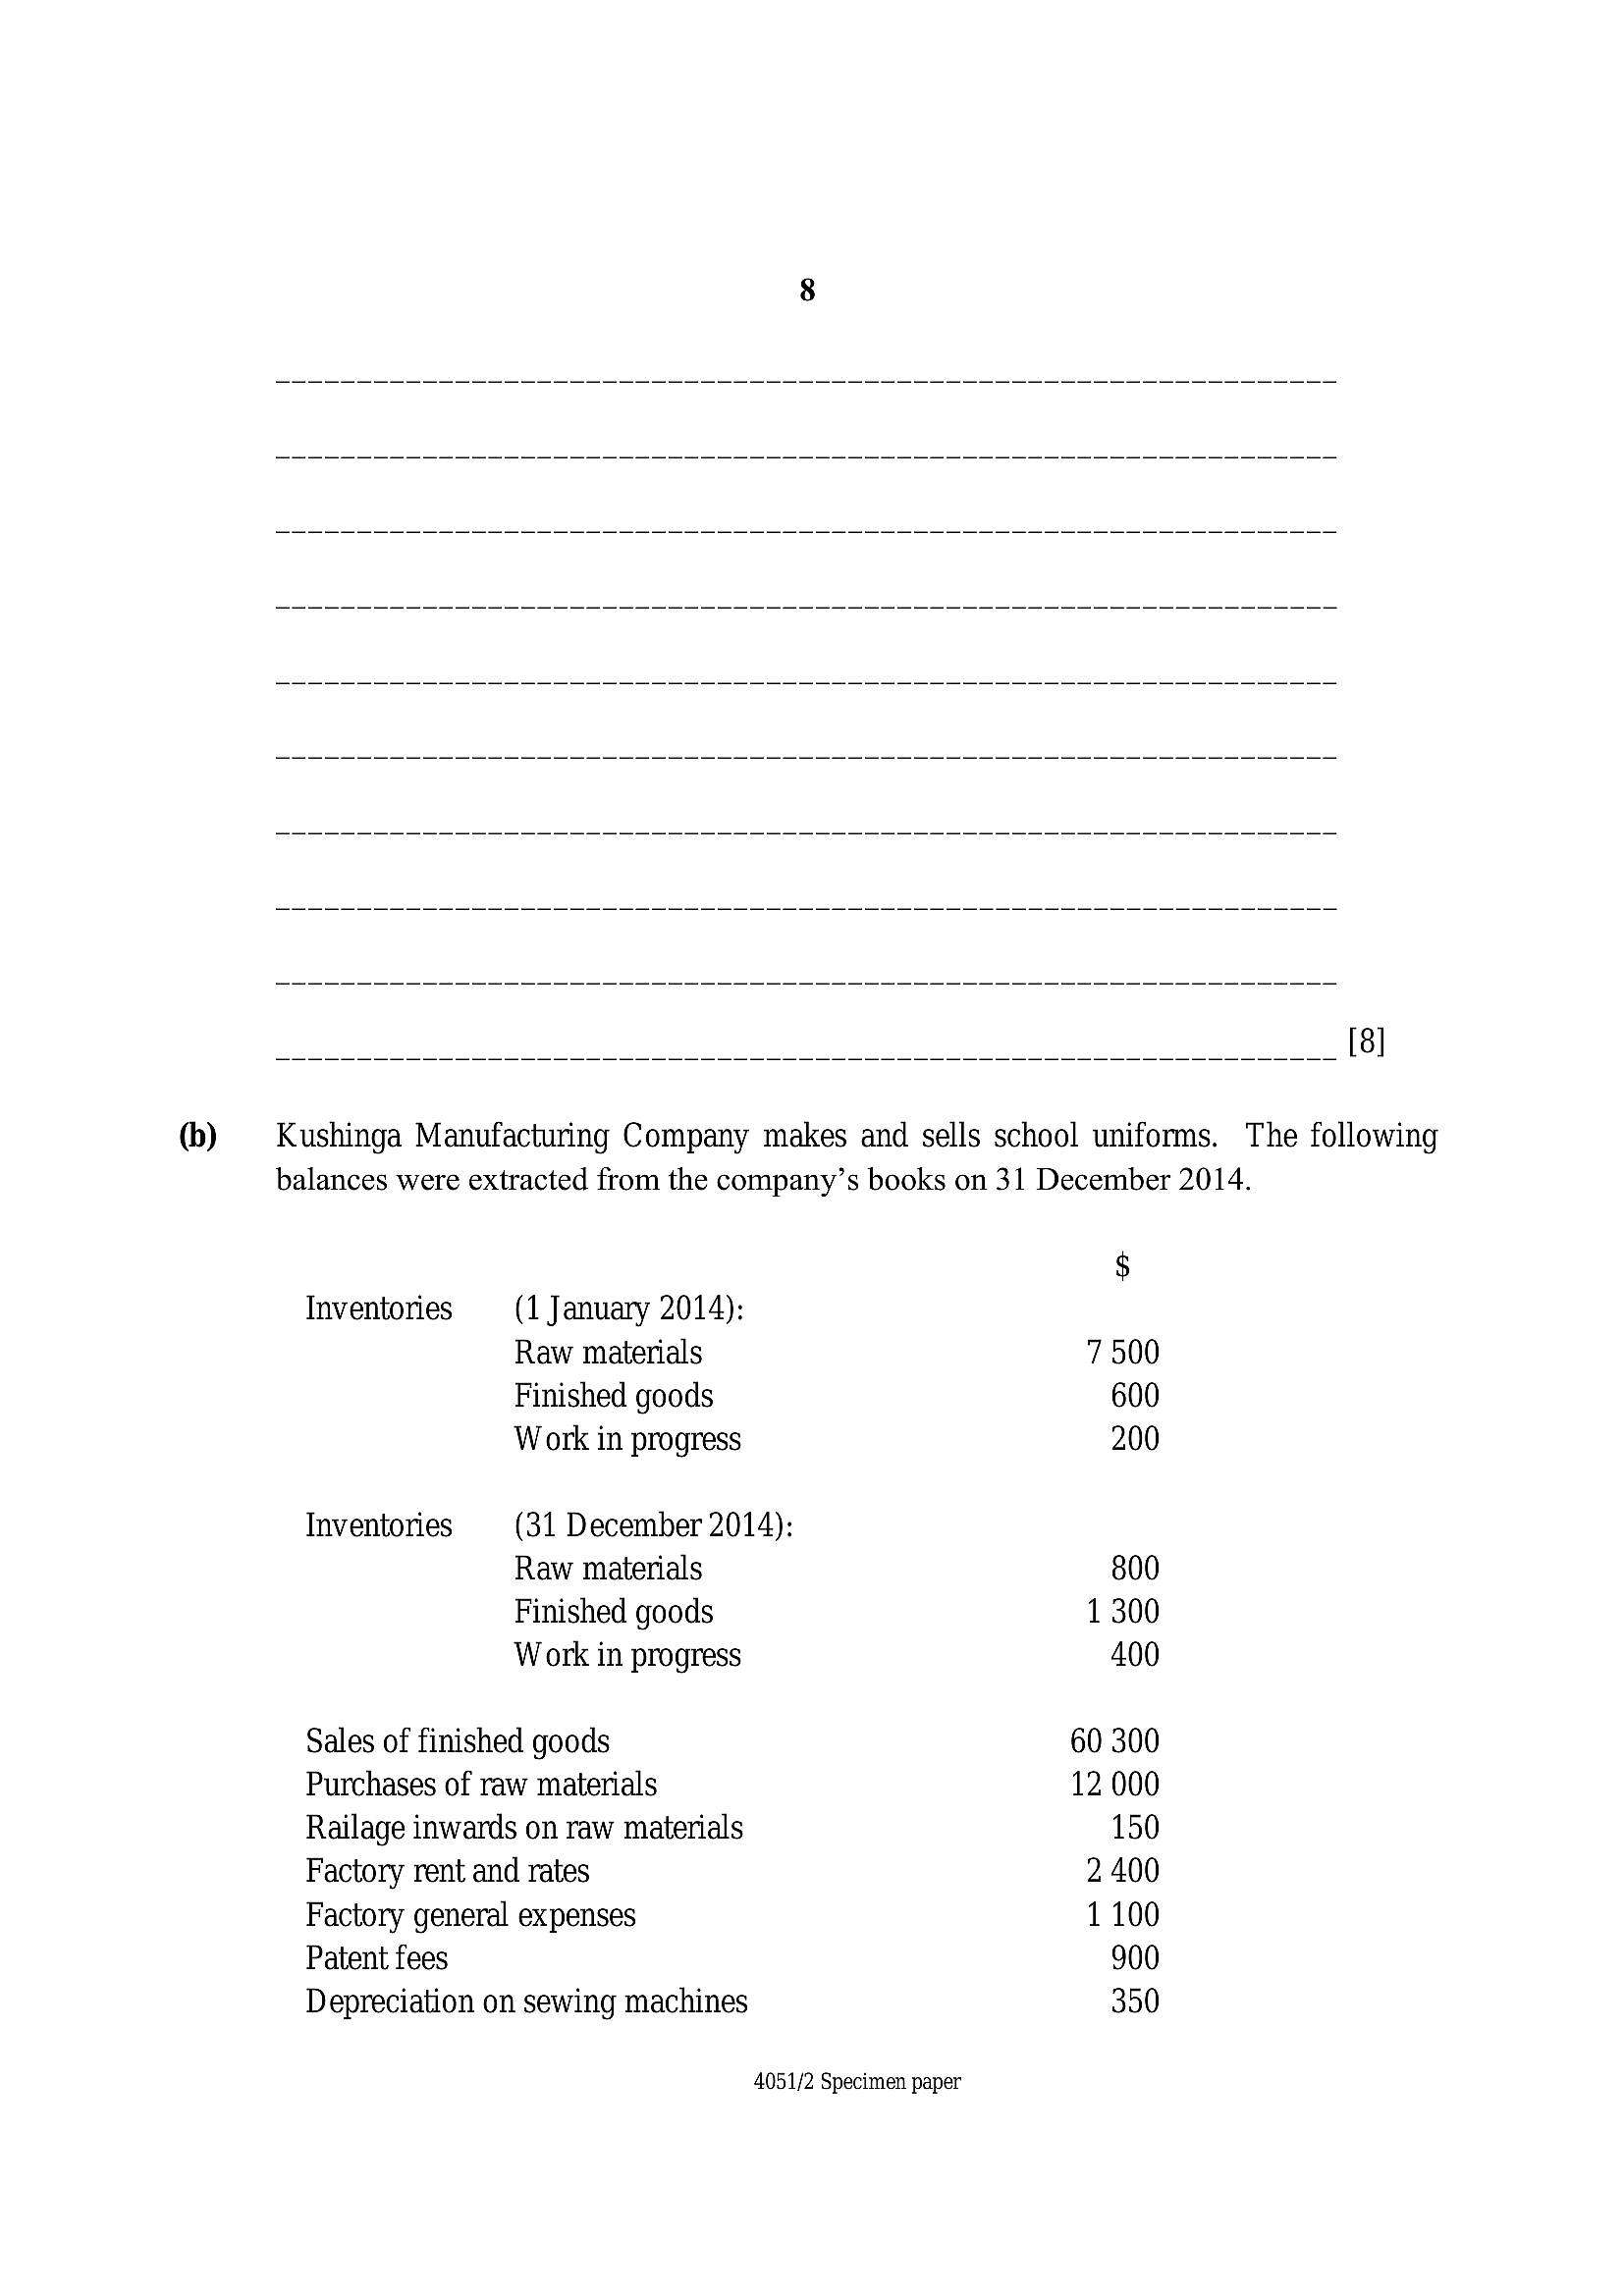
(b) = Kushinga Manufacturing Company makes and sells school uniforms. The following balances were extracted from the company’s books on 31 December 2014.$
Inventories (1 January 2014):
Raw materials 7500
Finished goods 600
Work in progress 200
Inventories (31 December 2014):
Raw materials 800
Finished goods 1300
Work in progress 400
Sales of finished goods 60 300
Purchases of raw materials 12 000
Railage inwards on raw materials 150
Factory rent and rates 2 400
Factory general expenses 1100
Patent fees 900
Depreciation on sewing machines 350
4051/2 Specimen paper
---
Page 9
Extracted Text
Y ou are required to prepare:(i) A Manufacturing Account for the year ended 31 December 2014.
4051/2 Specimen paper
[Turn over
---
Page 10
Extracted Text
(ii) = A Trading Account for the year ended 31 December 2014.4051/2 Specimen paper
---
Page 11
Extracted Text
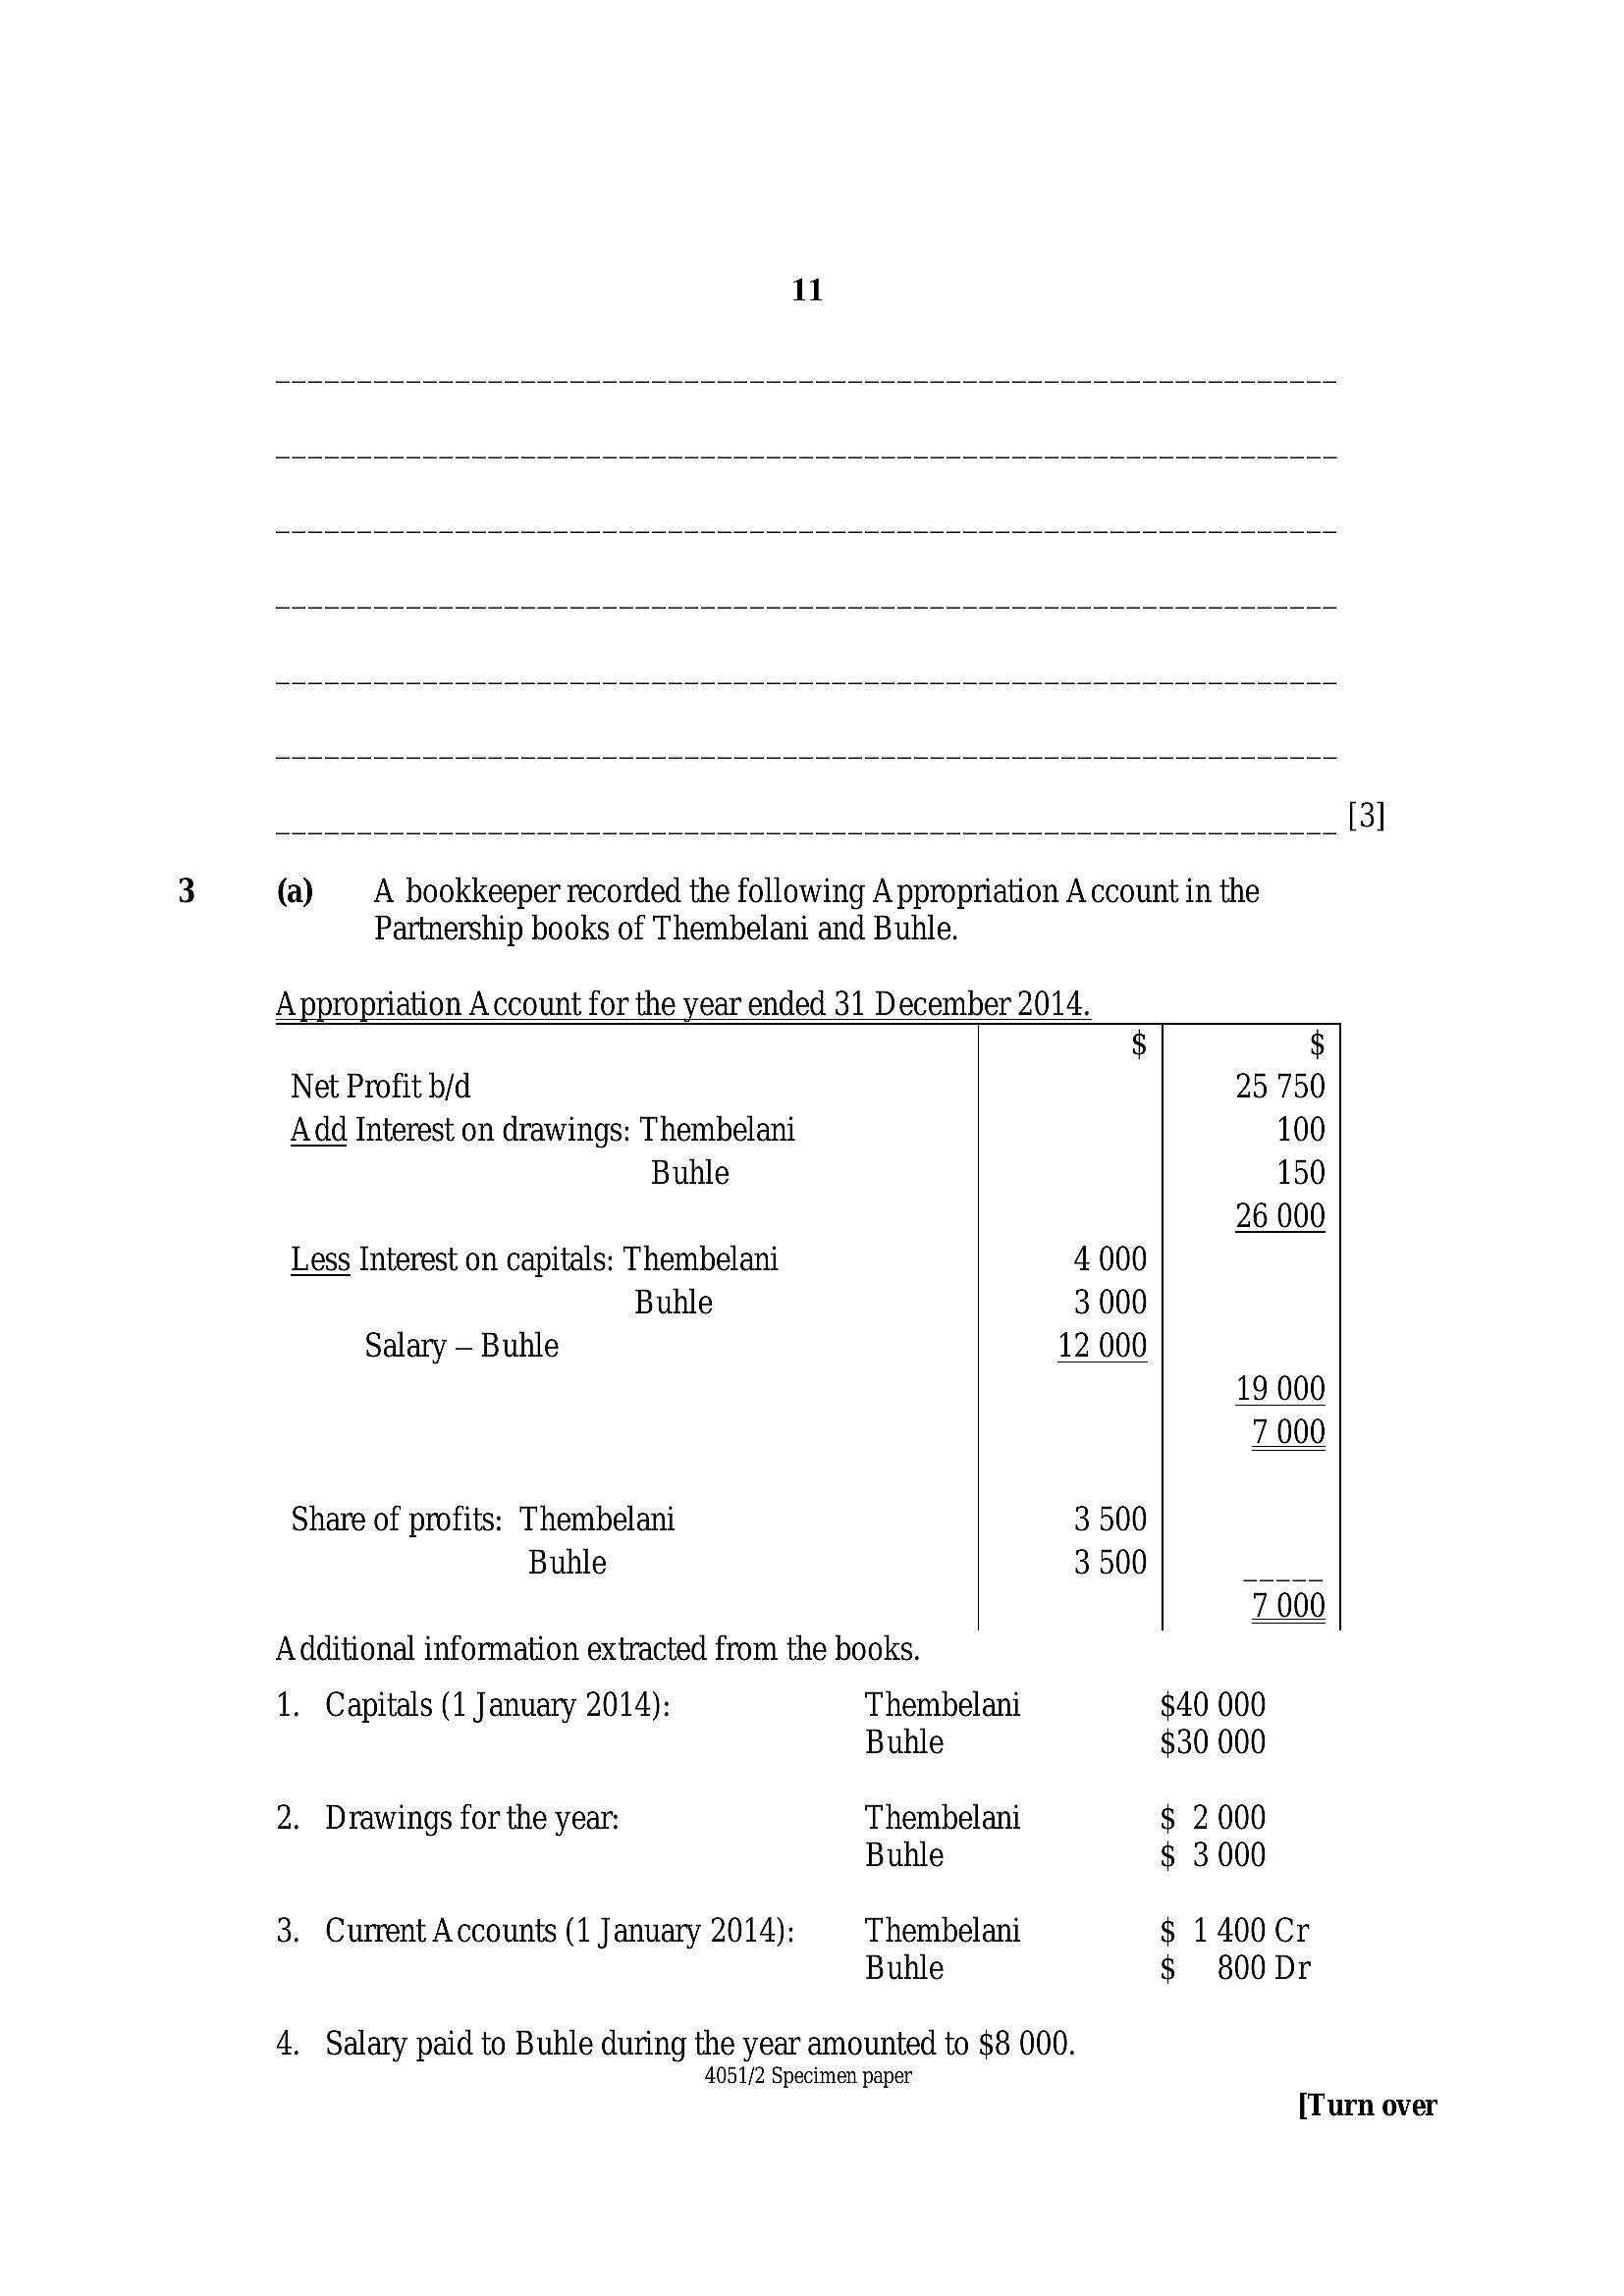
(a) A bookkeeper recorded the following A ppropriation A ccount in the Partnership books of Thembelani and Buhle.Appropriation A ccount for the year ended 31 December 2014.
$ $
Net Profit b/d 25 750
Add Interest on drawings: Thembelani 100
Buhle 150
26 000
Less Interest on capitals: Thembelani 4000
Buhle 3 000
Salary — Buhle 12 000
19 000
7.000
Share of profits: Thembelani 3 500
Buhle 3500;
7.000
Additional information extracted from the books.
1. Capitals (1 January 2014): Thembelani $40 000
Buhle $30 000
2. Drawings for the year: Thembelani $ 2000
Buhle $ 3.000
3. Current Accounts (1 January 2014): Thembelani $ 1400 Cr
Buhle $ 800Dr
4, Salary paid to Buhle during the year amounted to $8 000.
4051/2 Specimen paper
[Turn over
---
Page 12
Extracted Text
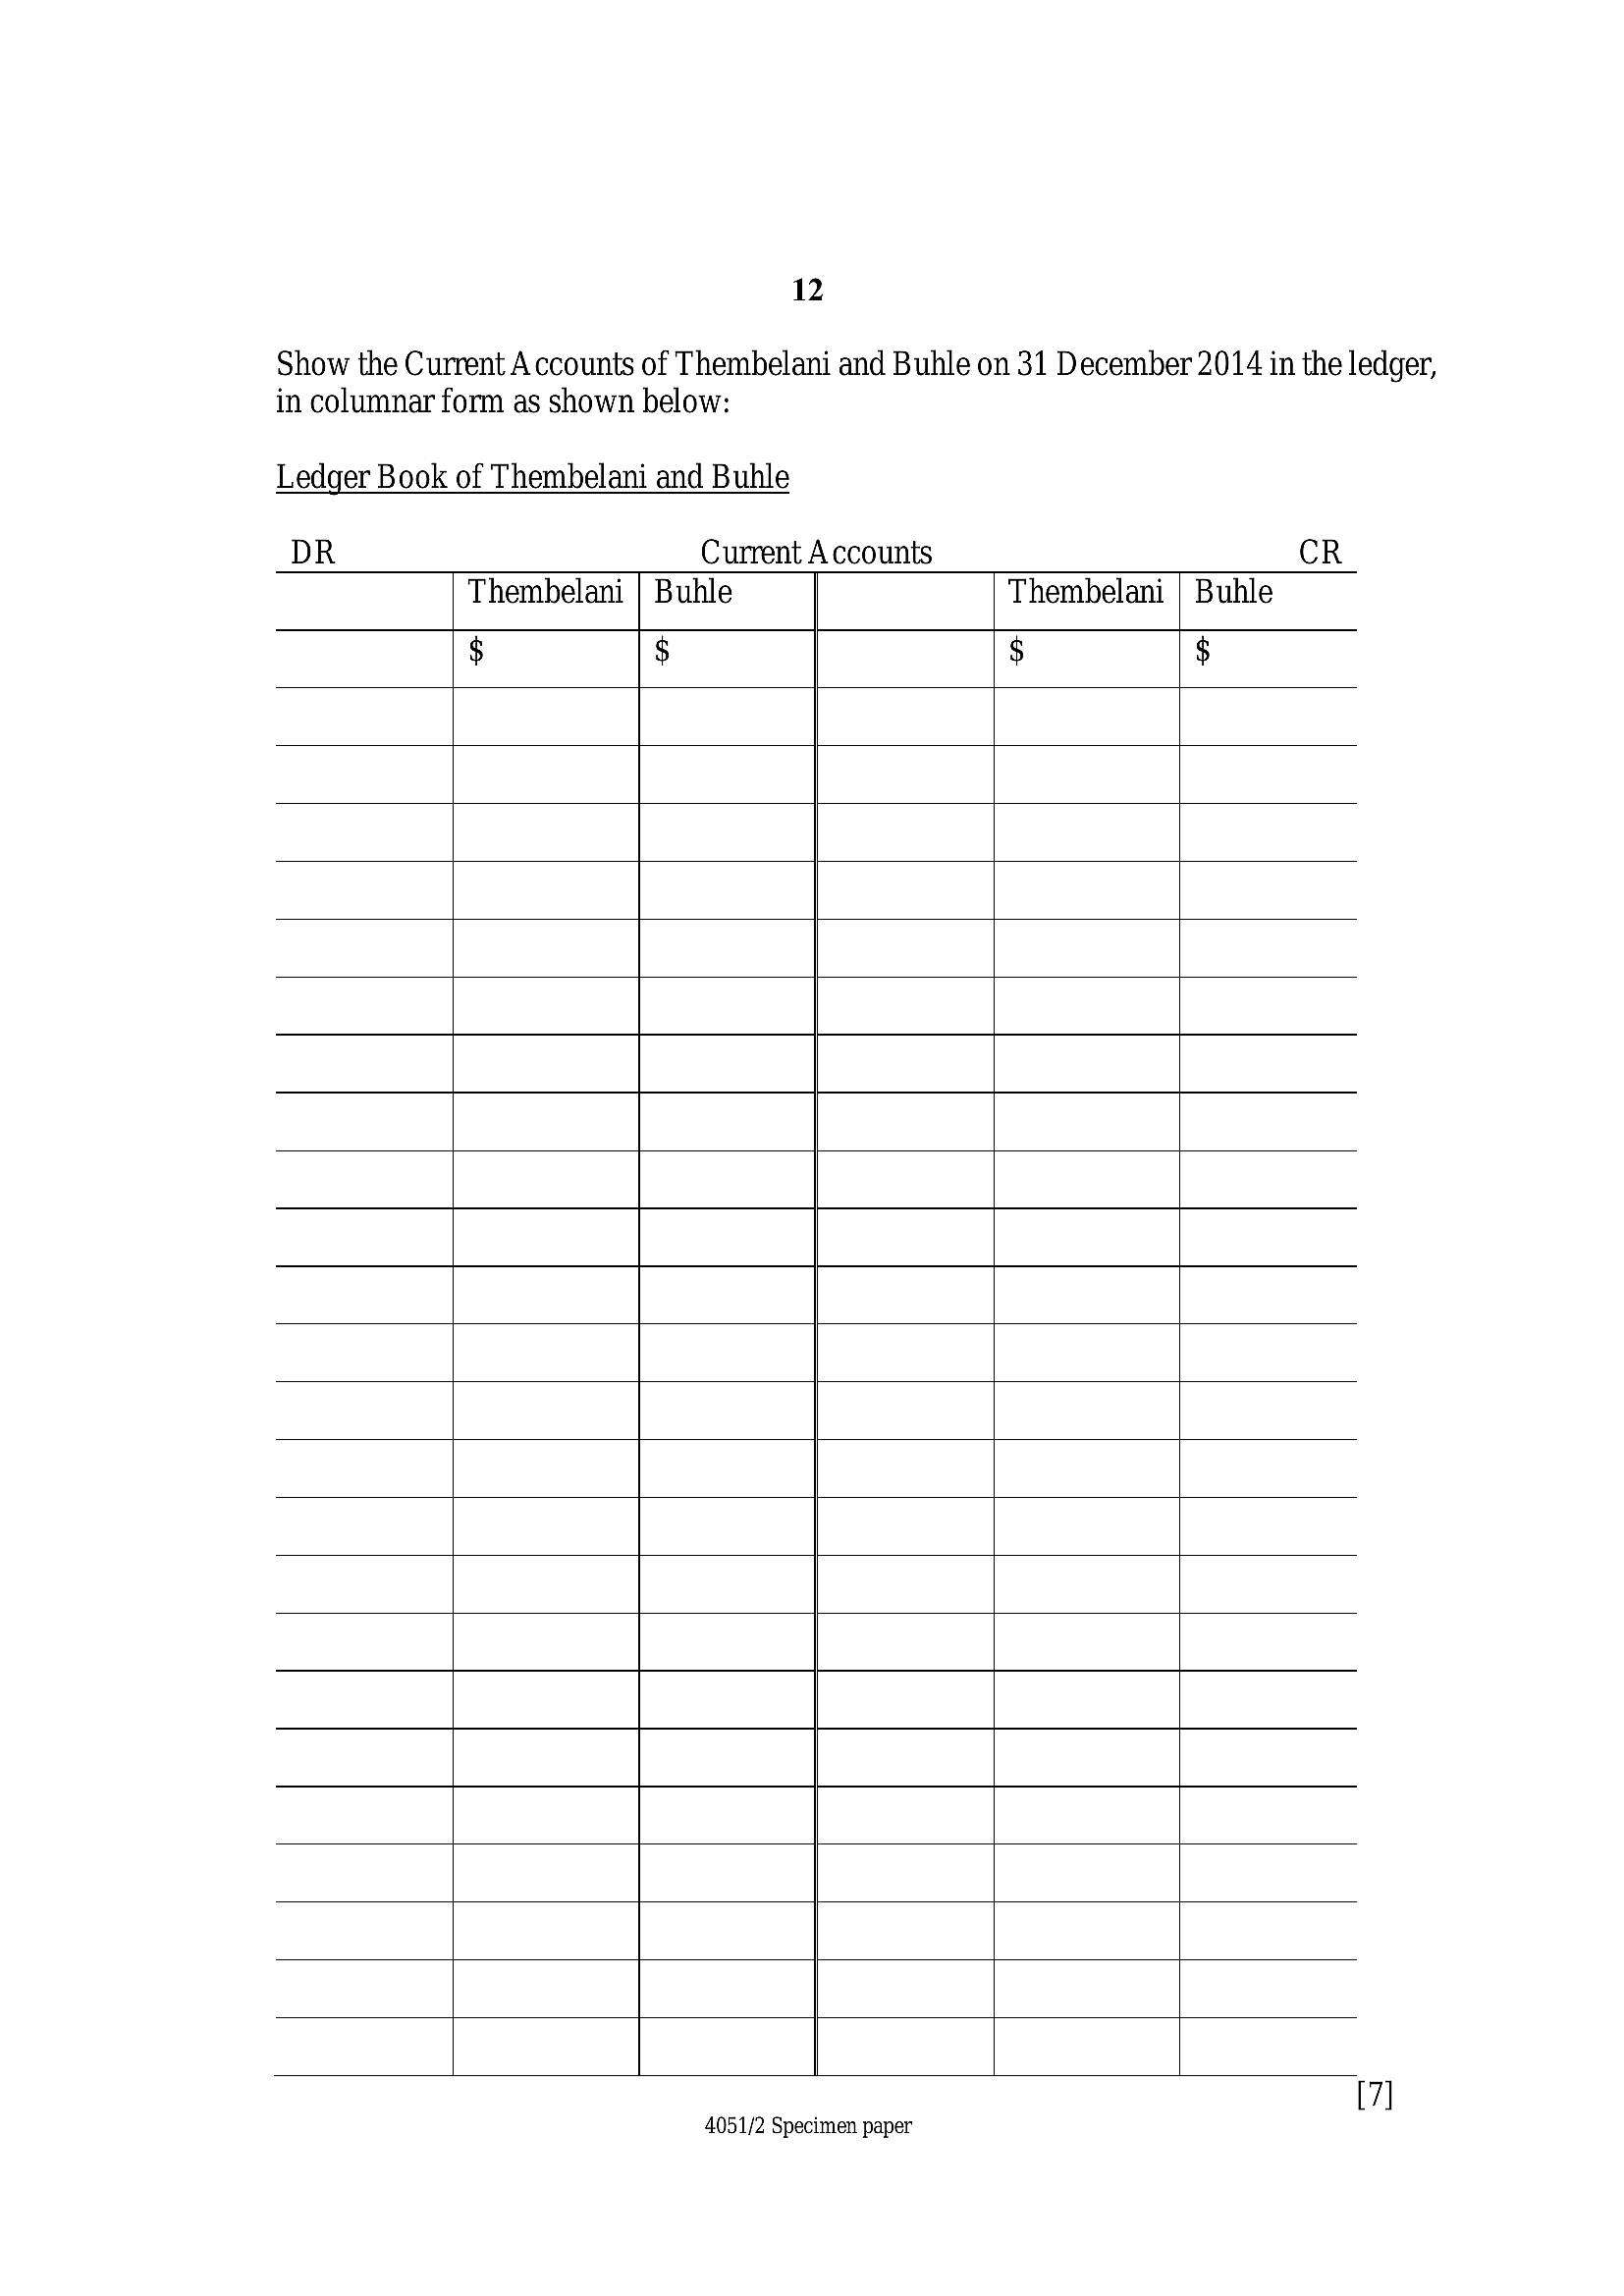
12Show the Current A ccounts of Thembelani and Buhle on 31 December 2014 in the ledger,
in columnar form as shown below:
Ledger Book of Thembelani and Buhle
DR Current Accounts CR
Thembelani | Buhle Thembelani | Buhle
$ $ $ $
4051/2 Specimen paper
---
Page 13
Extracted Text
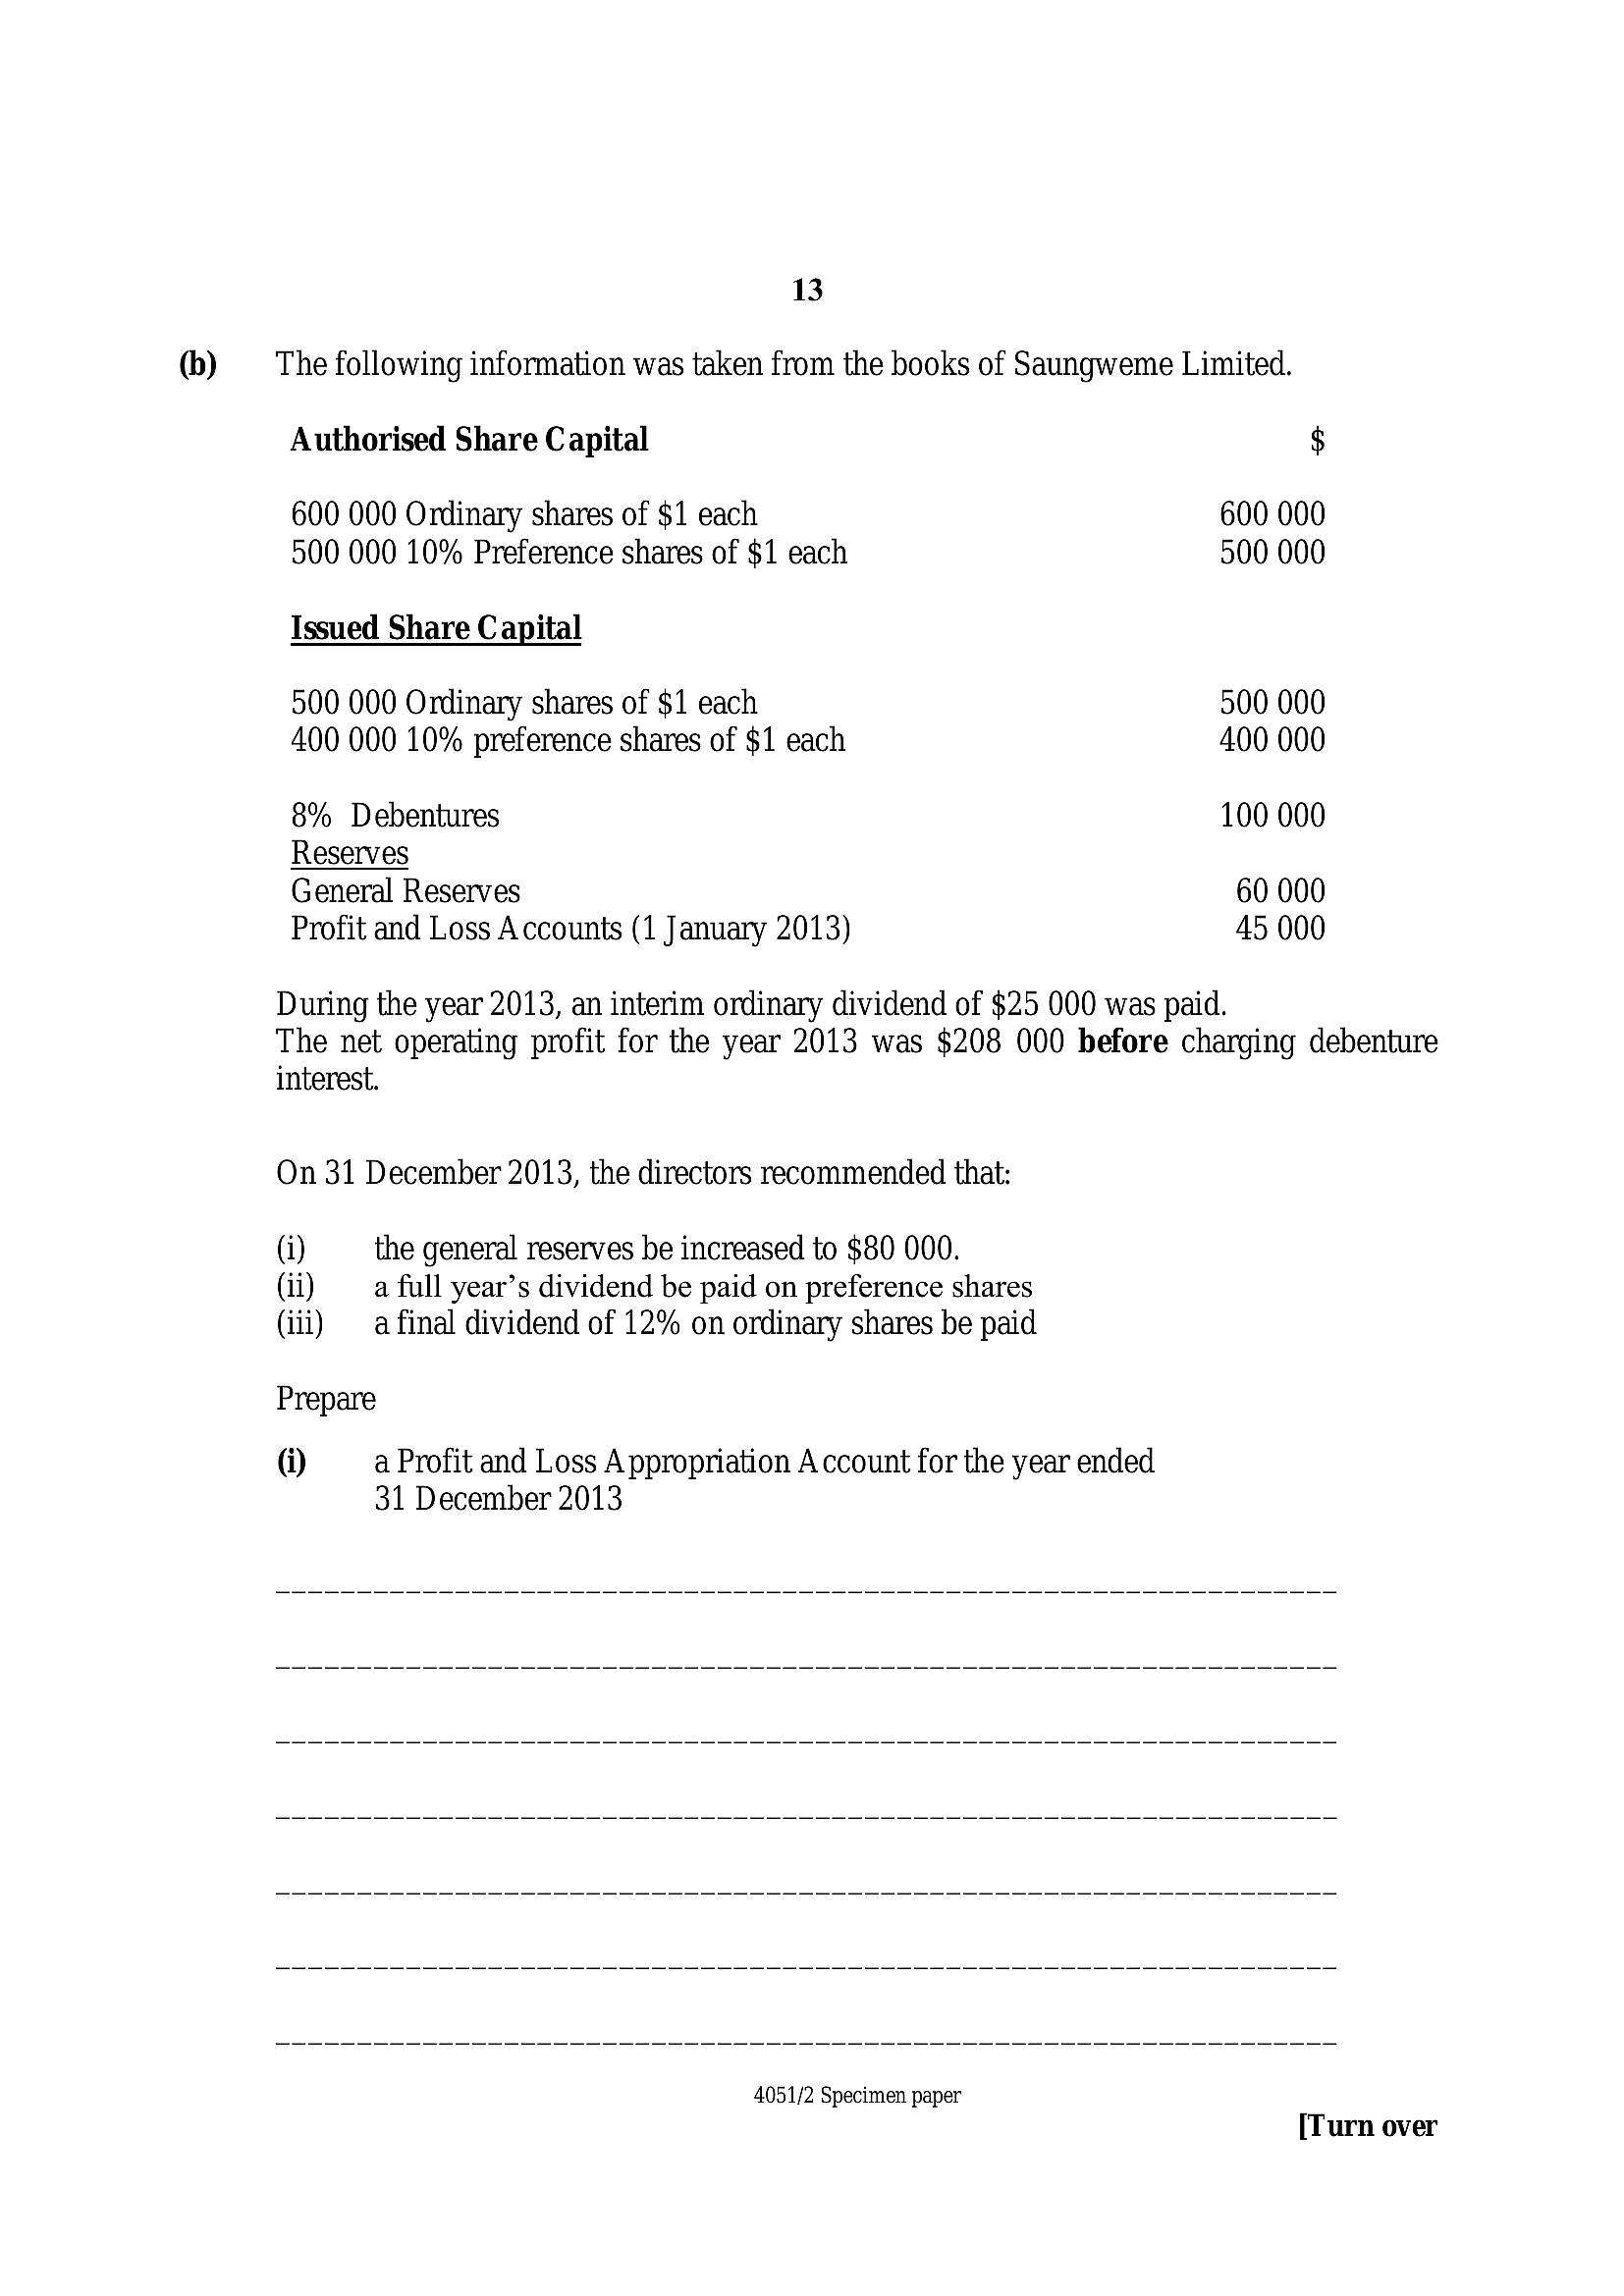
13(b) The following information was taken from the books of Saungweme Limited.
Authorised Share Capital $
600 000 Ordinary shares of $1 each 600 000
500 000 10% Preference shares of $1 each 500 000
Issued Share Capital
500 000 Ordinary shares of $1 each 500 000
400 000 10% preference shares of $1 each 400 000
8% Debentures 100 000
Reserves
General Reserves 60 000
Profit and Loss Accounts (1 January 2013) 45 000
During the year 2013, an interim ordinary dividend of $25 000 was paid.
The net operating profit for the year 2013 was $208 000 before charging debenture
interest.
On 31 December 2013, the directors recommended that:
(i) the general reserves be increased to $80 000.
(ii) a full year’s dividend be paid on preference shares
(iii) a final dividend of 12% on ordinary shares be paid
Prepare
(1) a Profit and Loss A ppropriation A ccount for the year ended
31 December 2013
4051/2 Specimen paper
[Turn over
---
Page 14
Extracted Text
(ii) a Statement of Financial Position extract as at 31 December 2013, showing the details and total of the shareholders’ equity.4051/2 Specimen paper
---
Page 15
Extracted Text
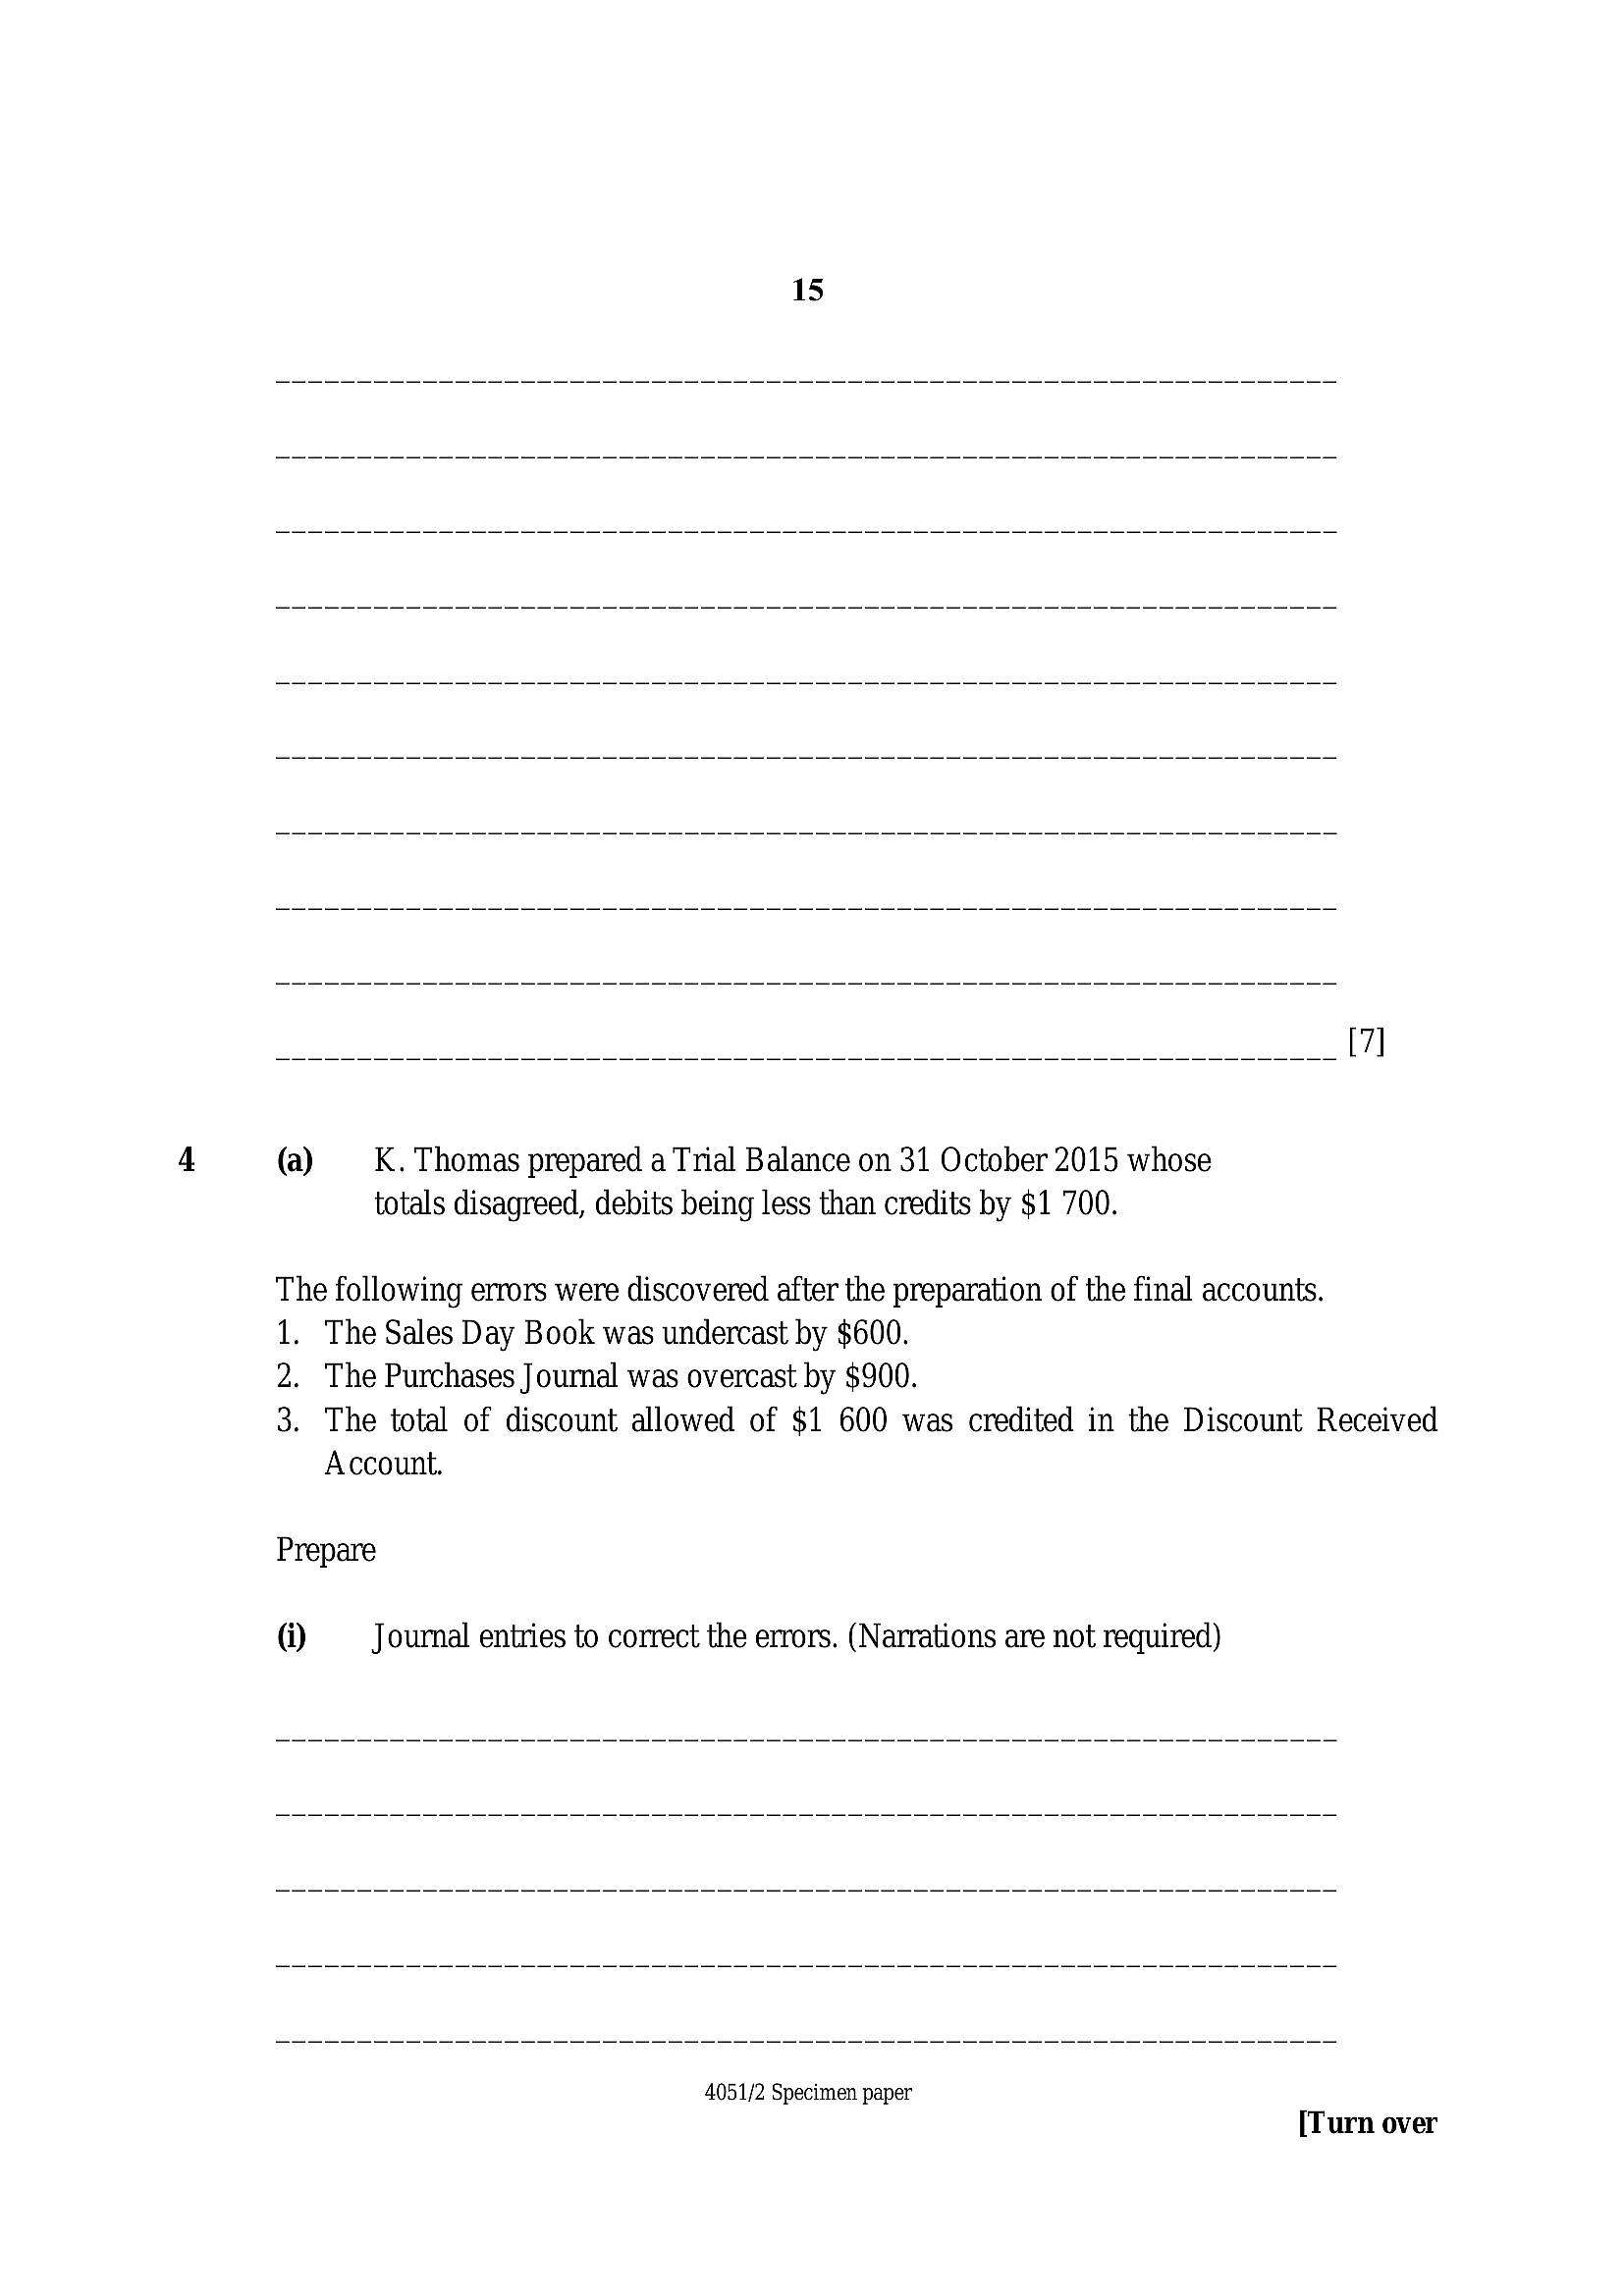
(a)The
K. Thomas prepared a Trial Balance on 31 October 2015 whose
totals disagreed, debits being less than credits by $1 700.
following errors were discovered after the preparation of the final accounts.
1. The Sales Day Book was undercast by $600.
2. The Purchases Journal was overcast by $900.
3. The total of discount allowed of $1 600 was credited in the Discount Received
Account.
Prepare
@
Journal entries to correct the errors. (Narrations are not required)
4051/2 Specimen paper
[Turn over
---
Page 16
Extracted Text
(ii) The Suspense Account.4051/2 Specimen paper
---
Page 17
Extracted Text
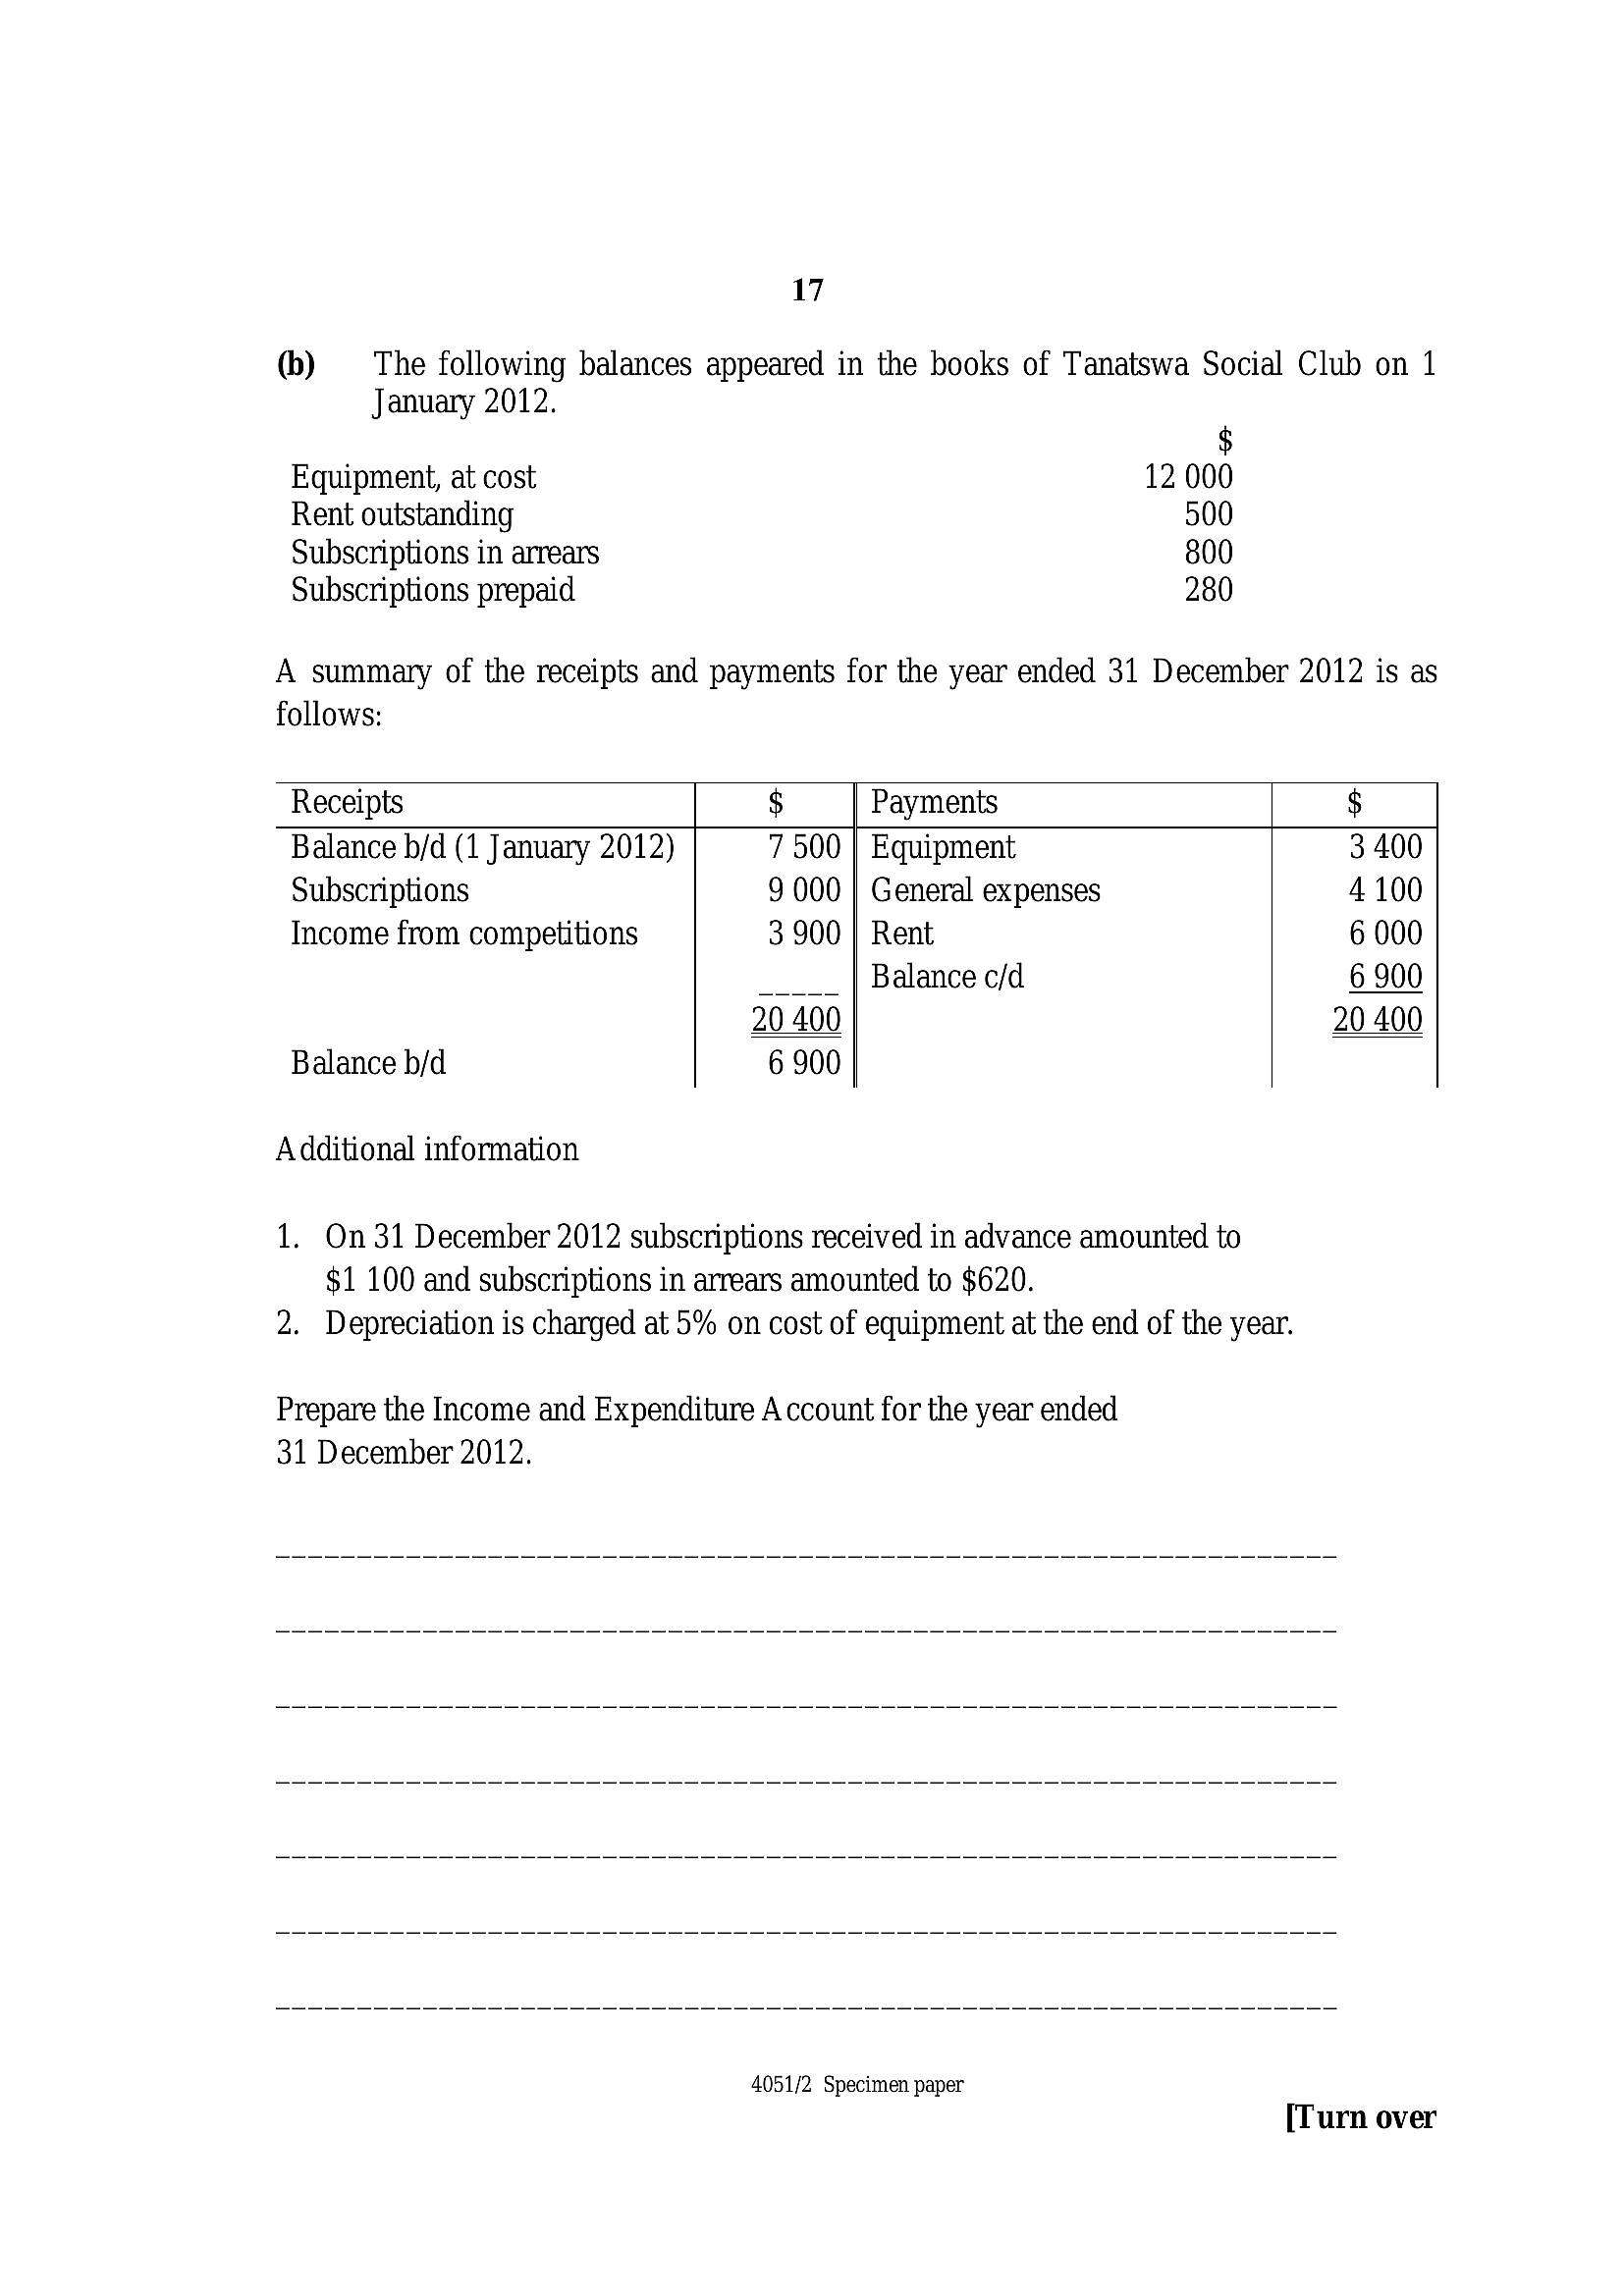
17(b) — The following balances appeared in the books of Tanatswa Social Club on 1
January 2012.
$
Equipment, at cost 12 000
Rent outstanding 500
Subscriptions in arrears 800
Subscriptions prepaid 280
A summary of the receipts and payments for the year ended 31 December 2012 is as
follows:
Receipts $ Payments $
Balance b/d (1 January 2012) 7 500 | Equipment 3 400
Subscriptions 9 000 | General expenses 4 100
Income from competitions 3 900 | Rent 6 000
_ Balance c/d 6 900
20 400 20 400
Balance b/d 6 900
Additional information
1. On31 December 2012 subscriptions received in advance amounted to
$1 100 and subscriptions in arrears amounted to $620.
2. Depreciation is charged at 5% on cost of equipment at the end of the year.
Prepare the Income and Expenditure A ccount for the year ended
31 December 2012.
4051/2 Specimen paper
[Turn over
---
Page 18
Extracted Text
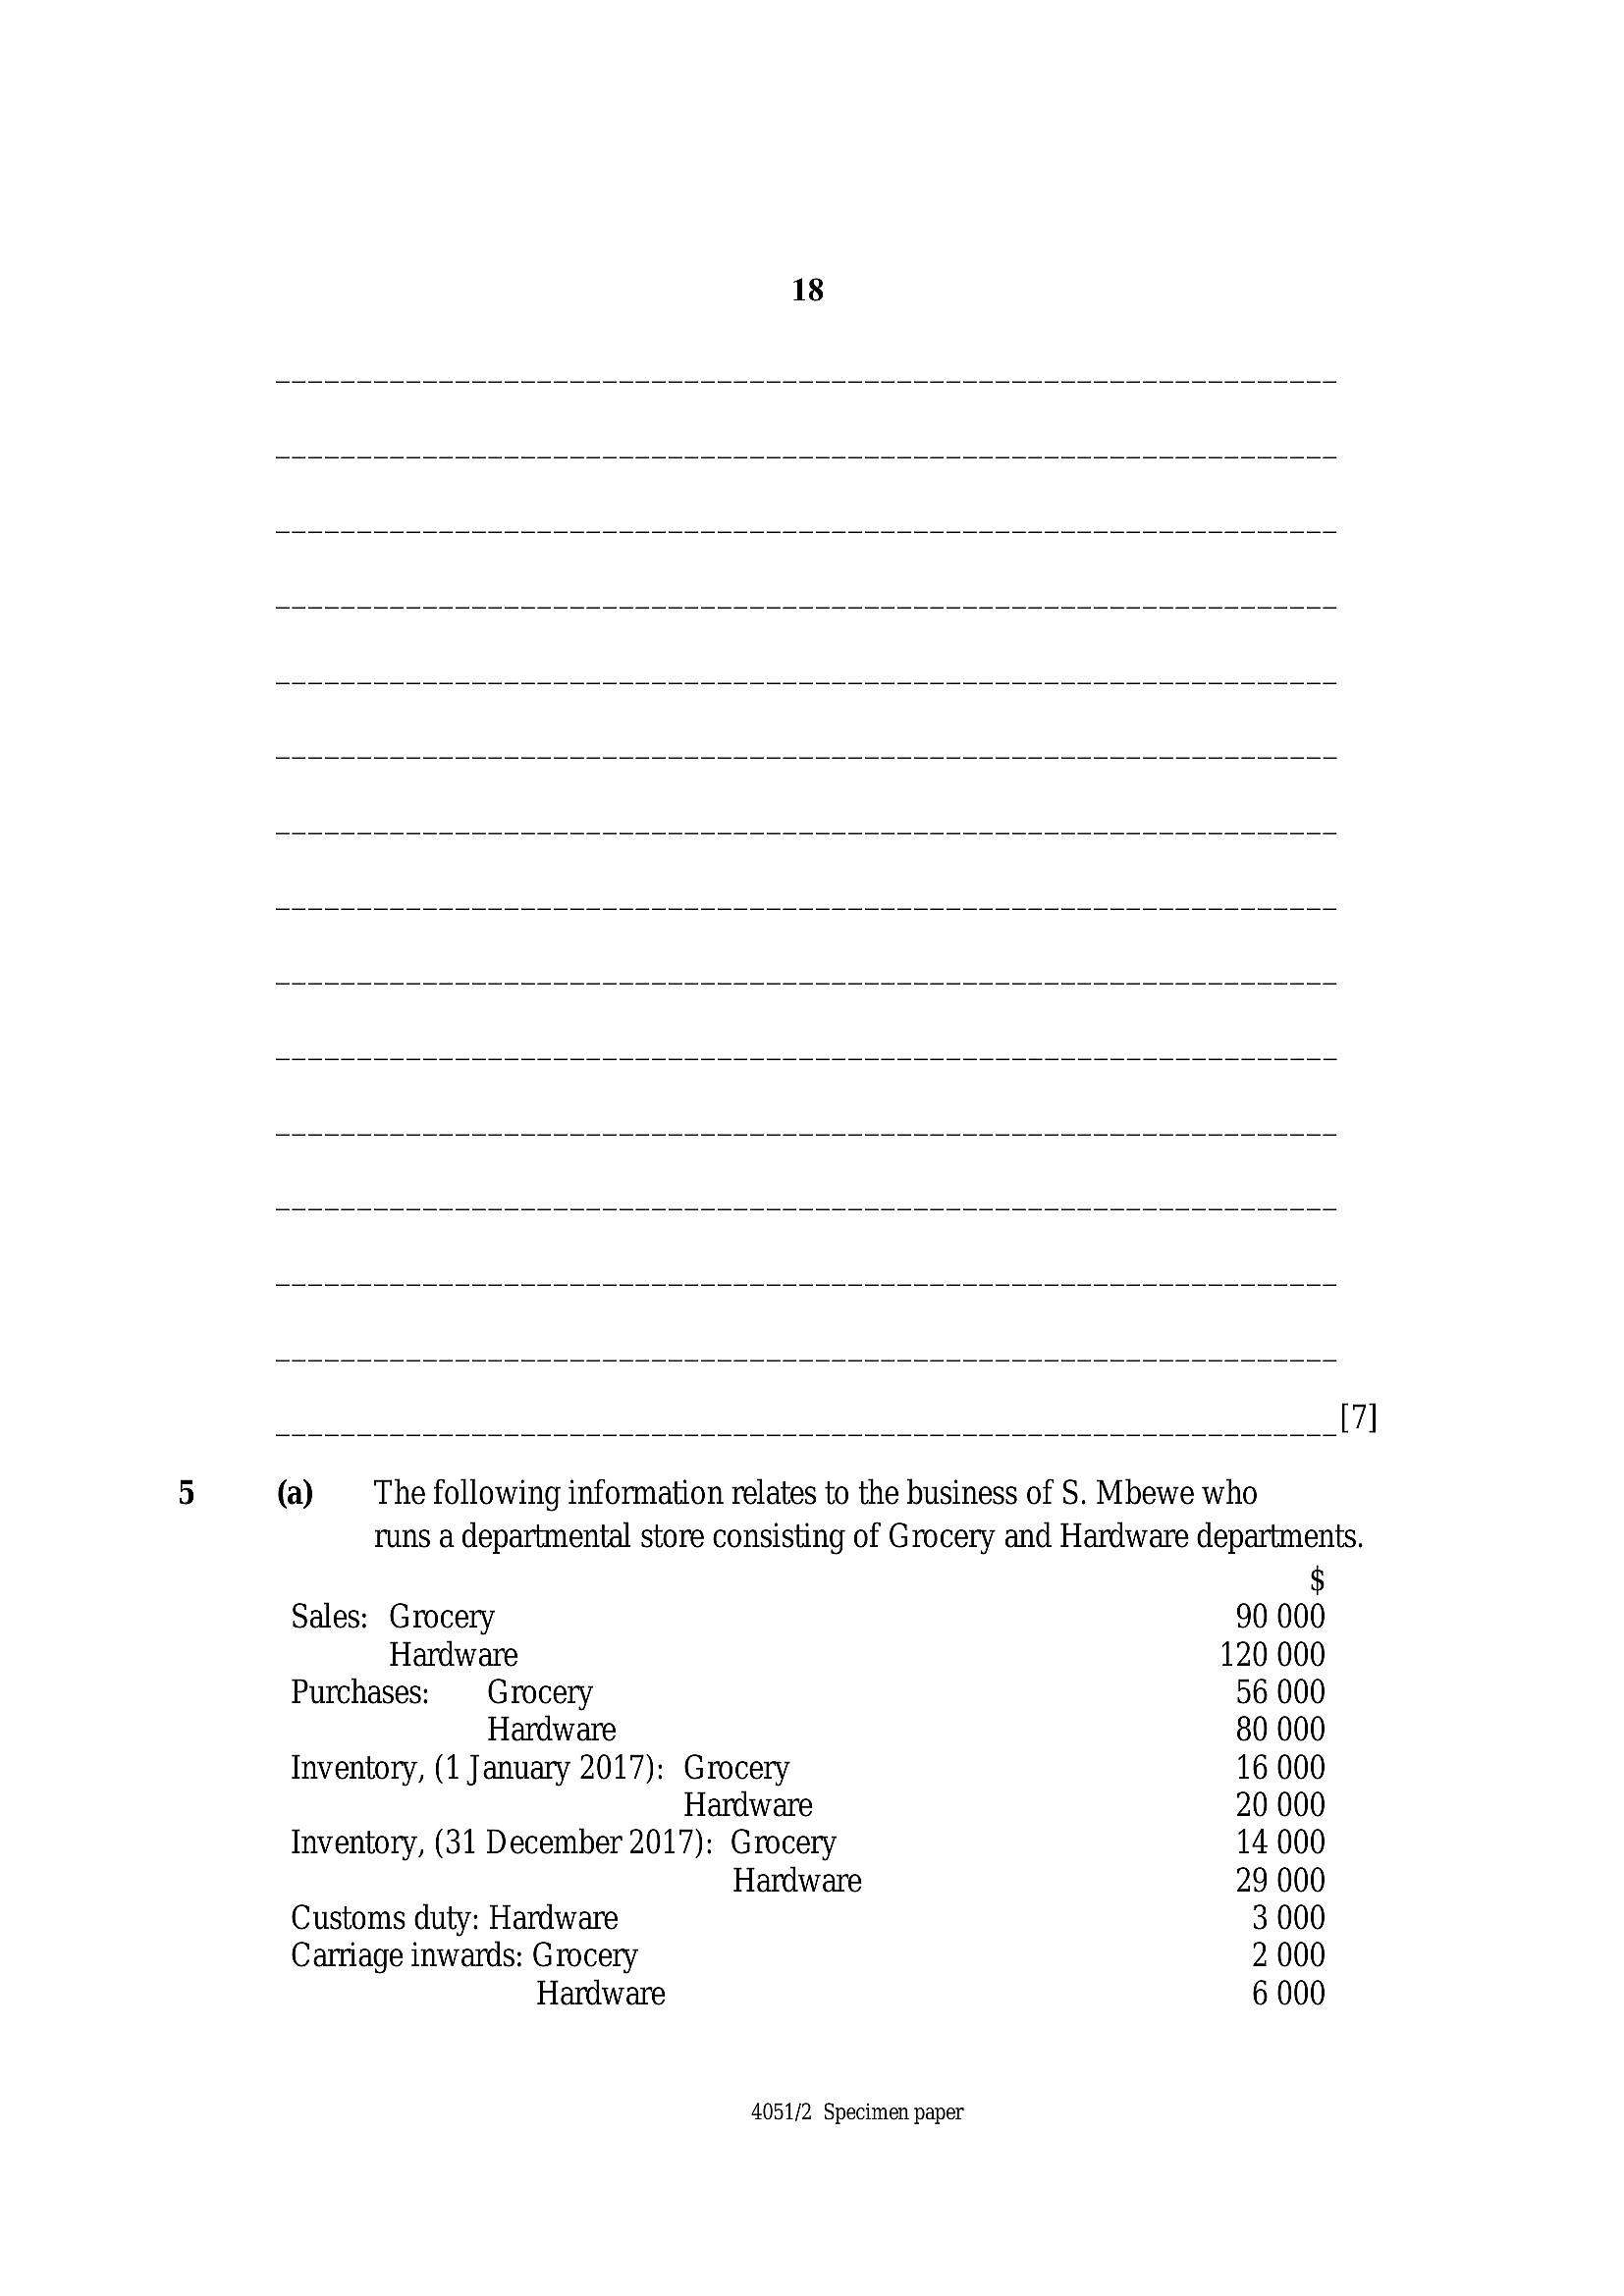
(a) The following information relates to the business of S. Mbewe who runs a departmental store consisting of Grocery and Hardware departments.Sales: Grocery
Hardware
Purchases: Grocery
Hardware
Inventory, (1 January 2017): Grocery
Hardware
Inventory, (31 December 2017): Grocery
Hardware
Customs duty: Hardware
Carriage inwards: Grocery
Hardware
4051/2 Specimen paper
$
90 000
120 000
56 000
80 000
16 000
20 000
14 000
---
Page 19
Extracted Text
19(i) _ prepare a Departmental Trading Account for the year ended
31 December 2017 [10]
4051/2 Specimen paper
[Turn over
---
Page 20
Extracted Text
(iii)4051/2 Specimen paper
---
Page 21
Extracted Text
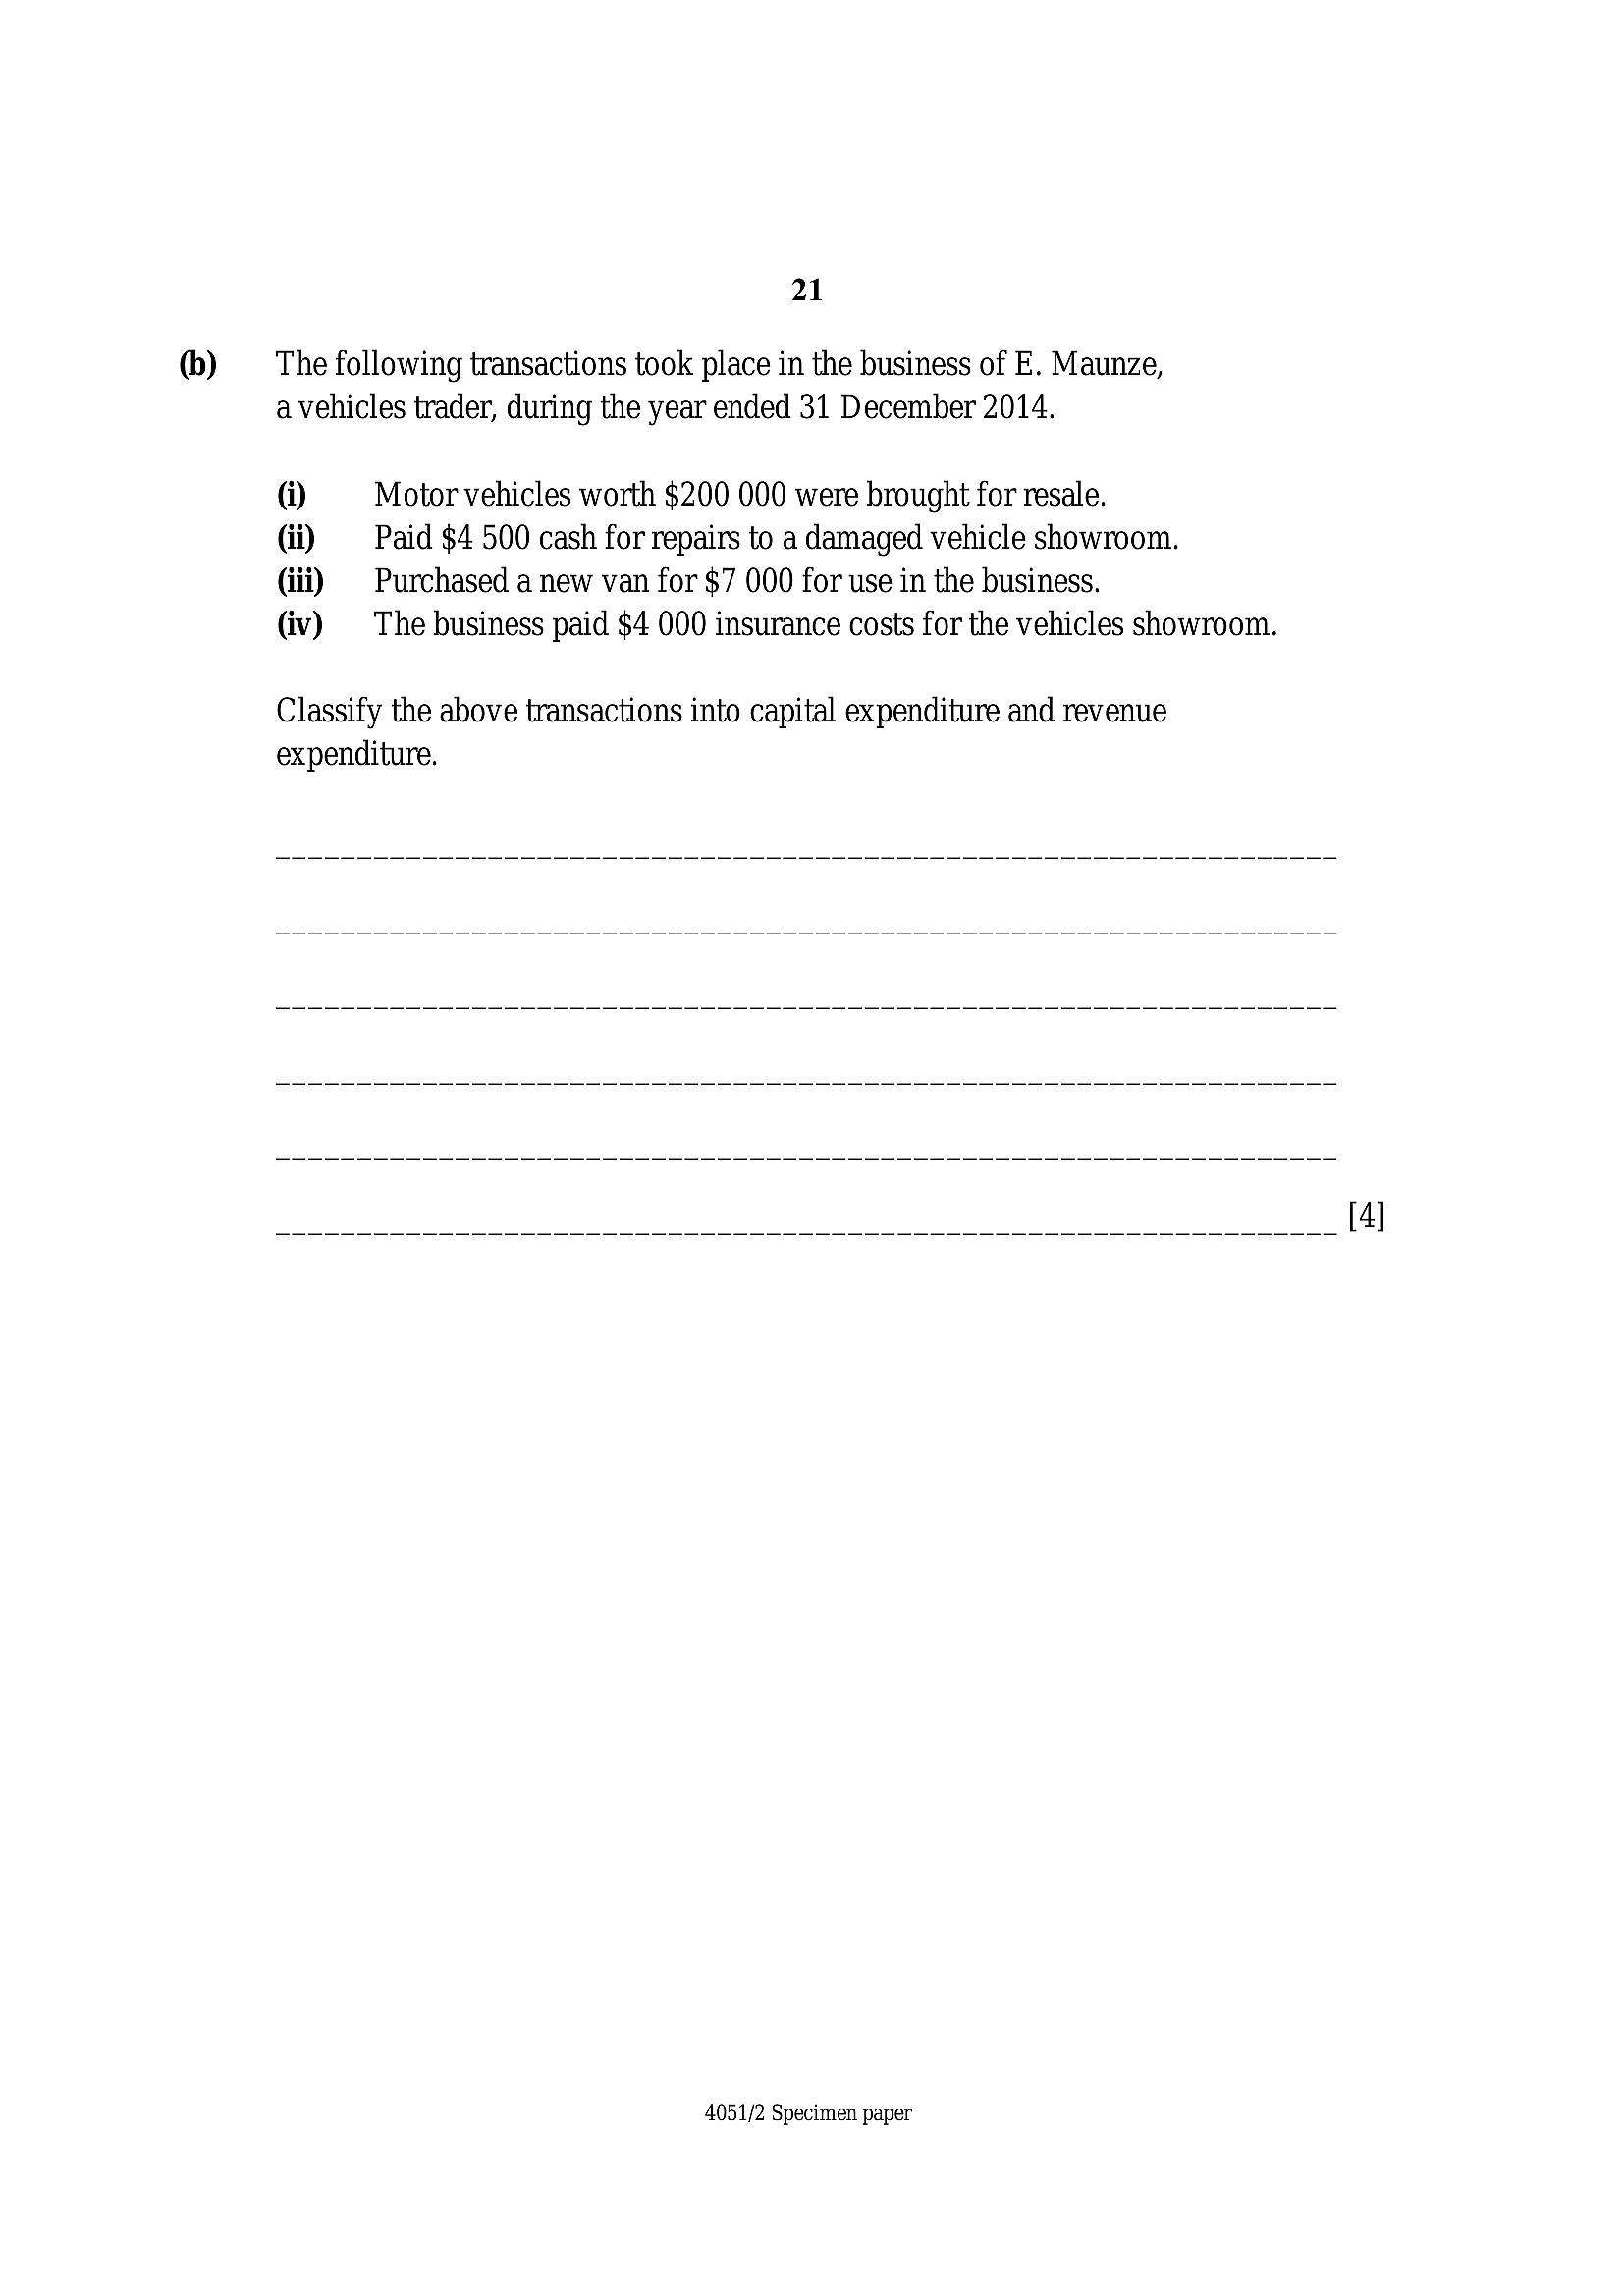
21(b) The following transactions took place in the business of E. Maunze,
a vehicles trader, during the year ended 31 December 2014.
@ Motor vehicles worth $200 000 were brought for resale.
di Paid $4 500 cash for repairs to a damaged vehicle showroom.
(iii) | Purchased a new van for $7 000 for use in the business.
(iv) | The business paid $4 000 insurance costs for the vehicles showroom.
Classify the above transactions into capital expenditure and revenue
expenditure.
4051/2 Specimen paper
---
Page 22
Extracted Text
22BLANK PAGE
4051/2 Specimen paper
---
Page 23
Extracted Text
23BLANK PAGE
4051/2 Specimen paper
---
Page 24
Extracted Text
24BLANK PAGE
4051/2 Specimen paper
---