2024_principlesOfAccounting_olevel_nov_paper1
Year: 2024 • Views: 2 • Downloads: 3
📄 Exam Questions & Readable Text Transcript
Full OCR-extracted text of questions, syllabus codes, and exam instructions.
Extracted Content: 2024_principlesOfAccounting_olevel_nov_paper1
Page 1
Extracted Text
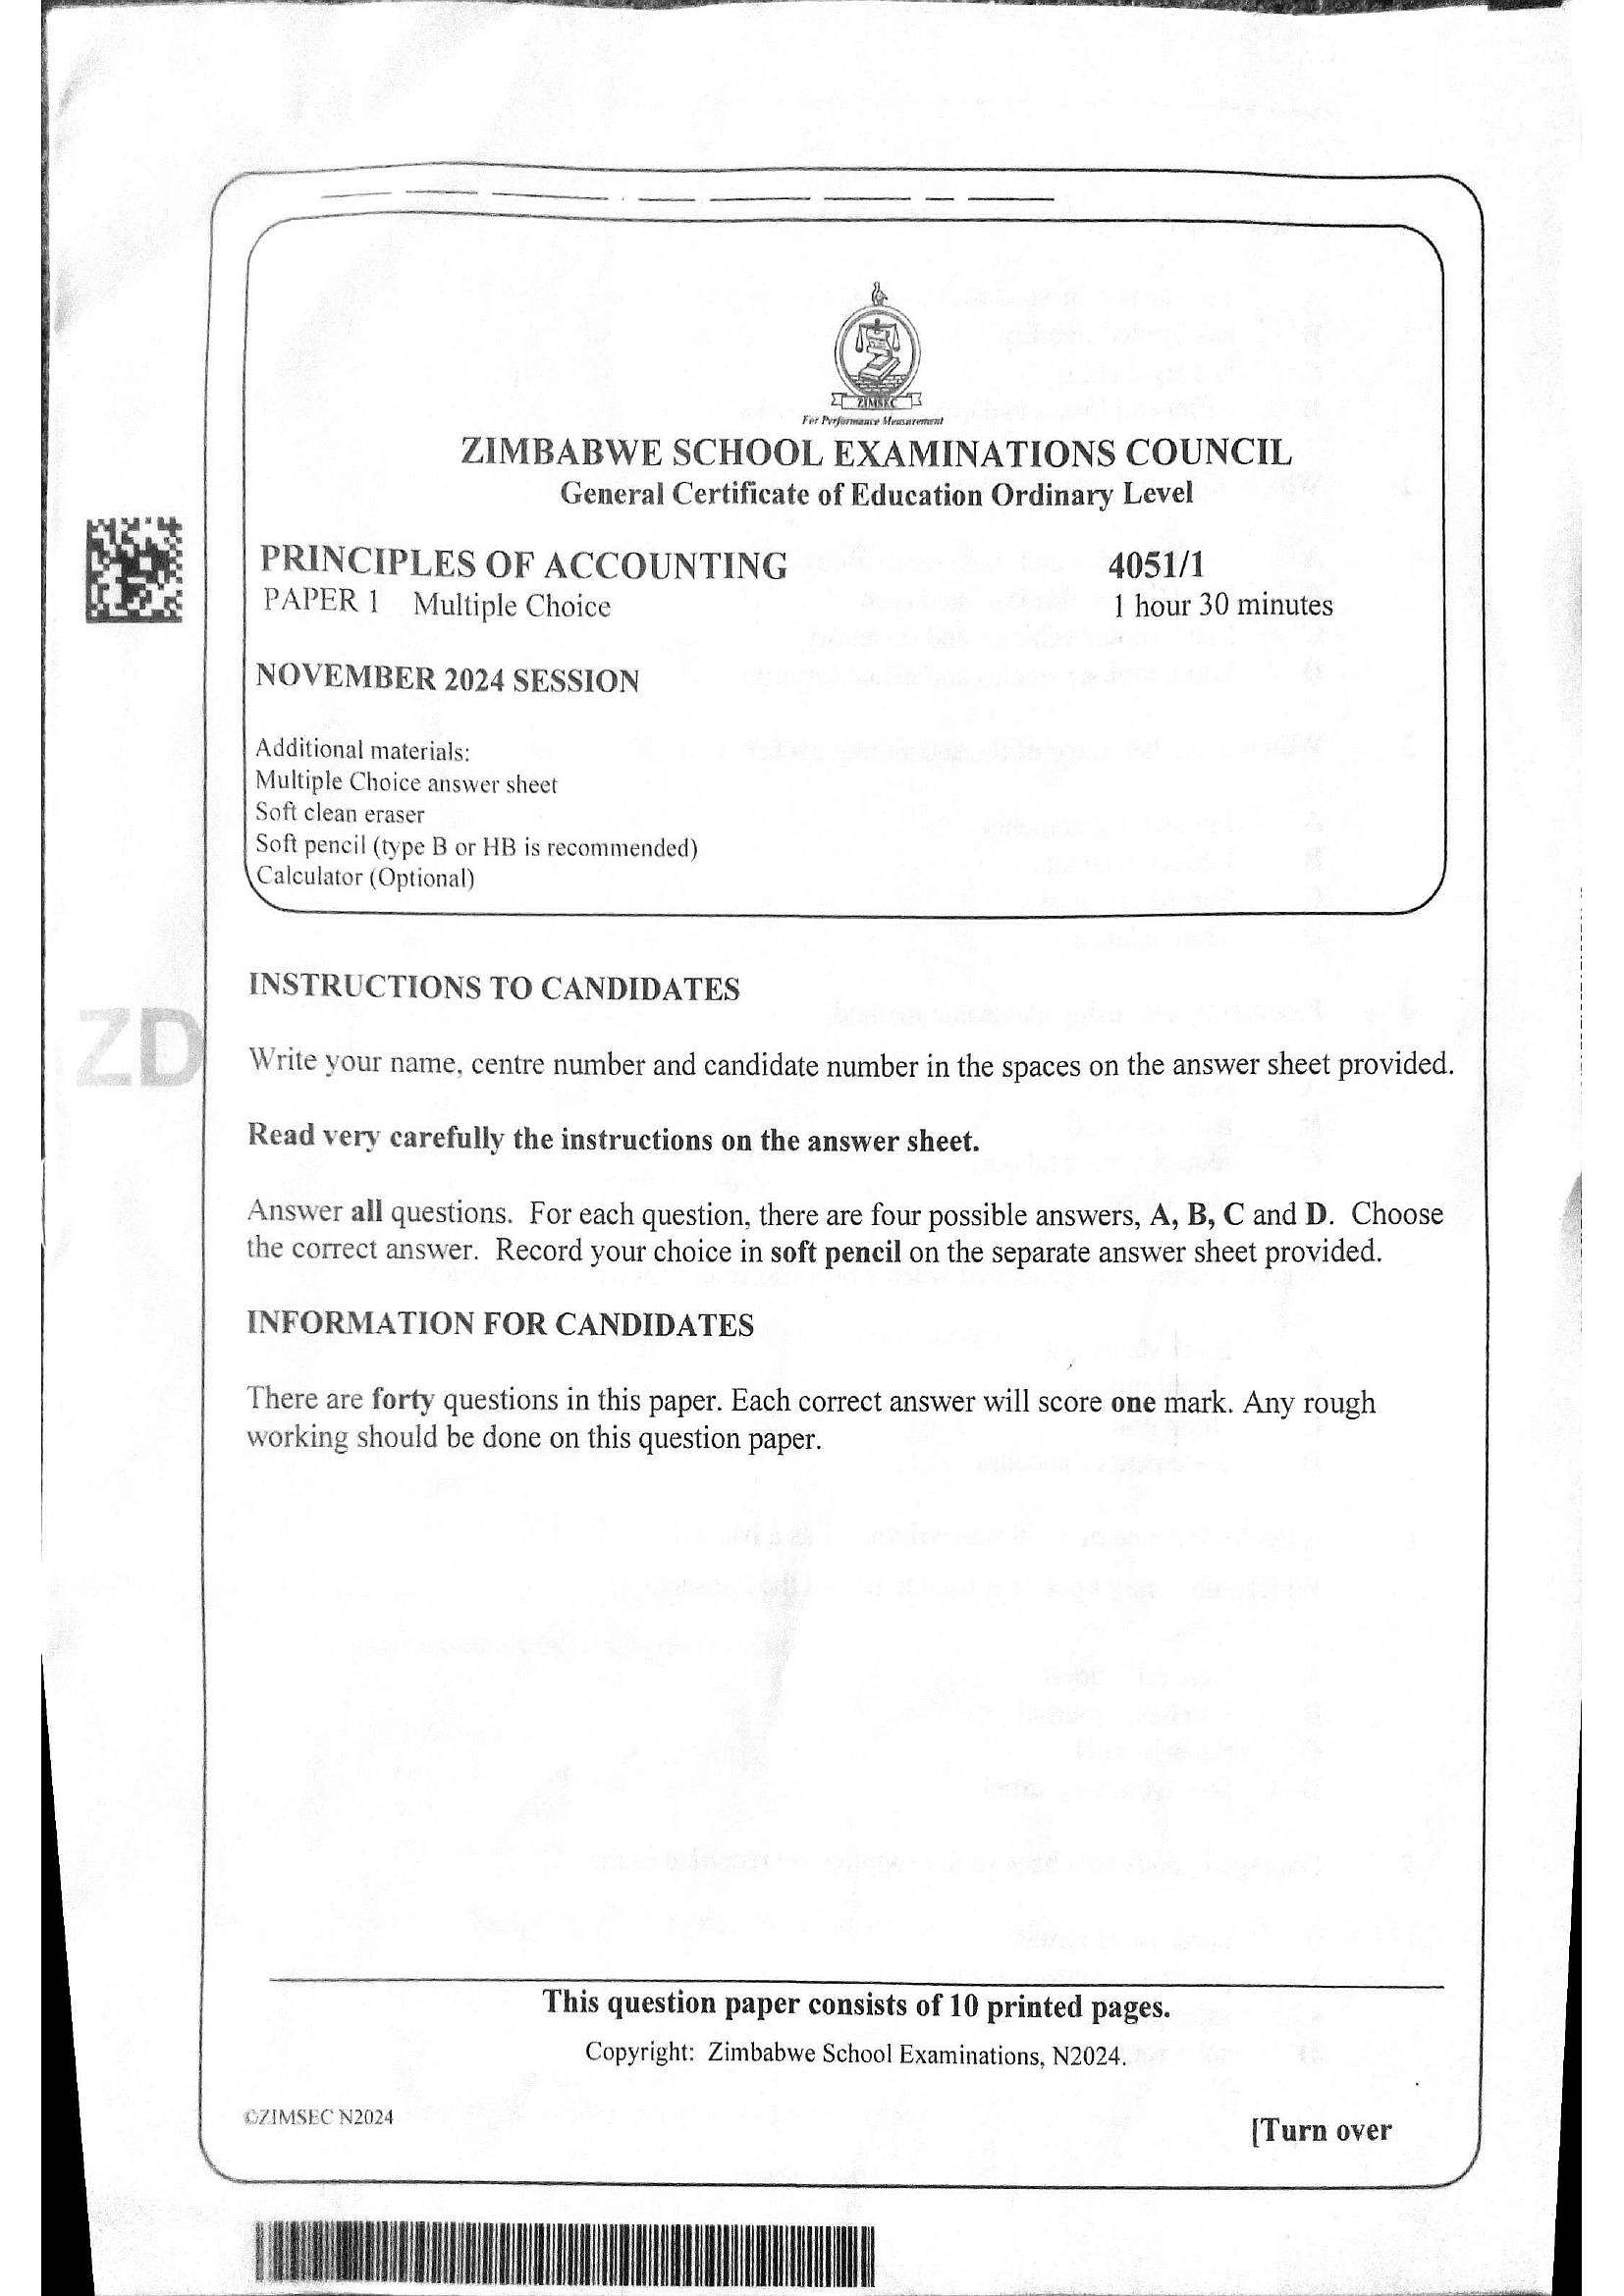
For Peformance MecsncementZIMBABWE SCHOOL EXAMINATIONS COUNCIL
General Certificate of Education Ordinary Level
PRINCIPLES OF ACCOUNTING 4051/1
PAPER 1 Multiple Choice 1 hour 30 minutes
NOVEMBER 2024 SESSION
Additional materials:
Multiple Choice answer sheet
Soft clean eraser
Soft pencil (type B or HB is recommended)
\edalnes (Optional)
INSTRUCTIONS TO CANDIDATES
Write your name, centre number and candidate number in the spaces on the answer sheet provided.
Read very carefully the instructions on the answer sheet.
Answer all questions. For each question, there are four possible answers, A, B, C and D. Choose
the correct answer. Record your choice in soft pencil on the separate answer sheet provided.
INFORMATION FOR CANDIDATES
There are forty questions in this paper. Each correct answer will score one mark. Any rough
working should be done on this question paper.
This question paper consists of 10 printed pages.
Copyright: Zimbabwe School Examinations, N2024.
SoZIMSEC N2024
[Turn over
CMAN
---
Page 2
Extracted Text
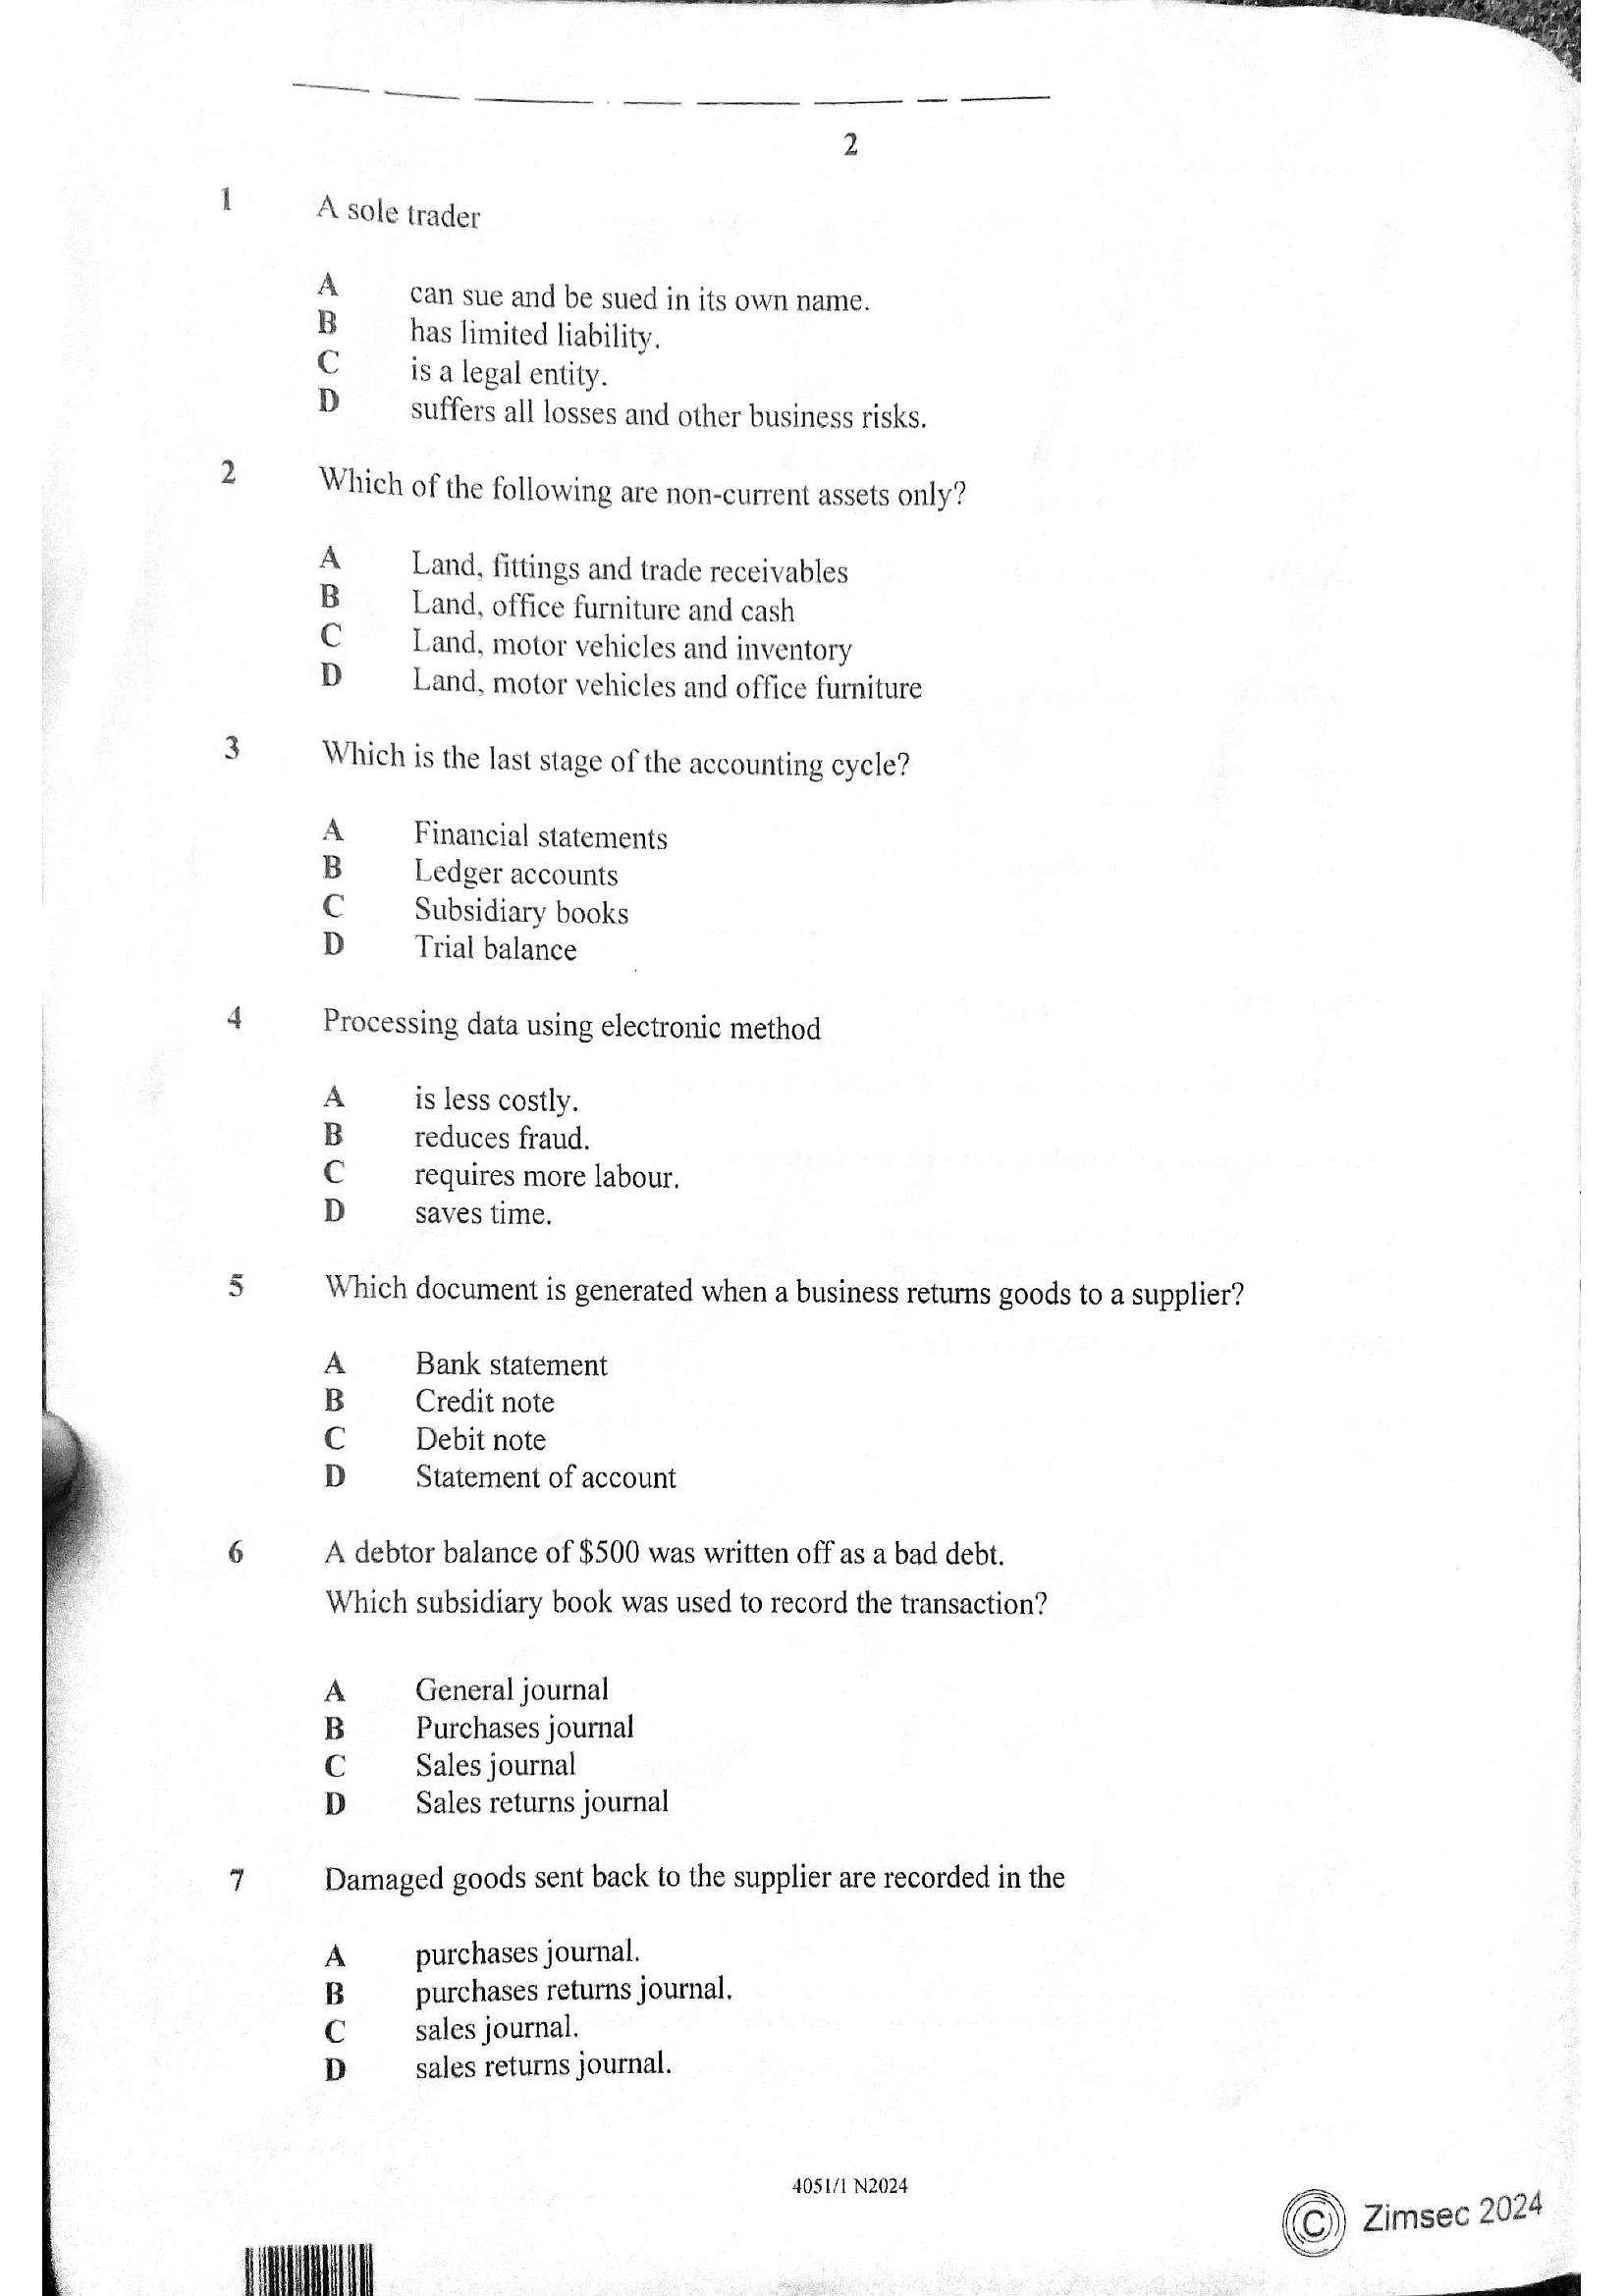
2 1 A sole trader A can sue and be sued in its own name. B has limited liability. C is a legal entity. D suffers all losses and other business risks. 2 Which of the following are non-current assets only? A Land, fittings and trade receivables B Land, office furniture and cash Cc Land, motor vehicles and inventory D Land, motor vehicles and office furniture 3 Which is the last stage of the accounting cycle? A Financial statements B Ledger accounts Cc Subsidiary books D Trial balance 4 Processing data using electronic method | A is less costly. B reduces fraud. Cc requires more labour. D saves time. 5 Which document is generated when a business returns goods to a supplier? A Bank statement B Credit note Cc Debit note D Statement of account6 A debtor balance of $500 was written off as a bad debt.
Which subsidiary book was used to record the transaction?
General journal
Purchases journal
Sales journal
Sales returns journal
Sour
7 Damaged goods sent back to the supplier are recorded in the
purchases journal.
purchases returns journal,
sales journal.
sales returms journal.
Sawp>
A0S1/1 N2024
© Zimsec 2024
HA ae |
---
Page 3
Extracted Text
11COONAN AA
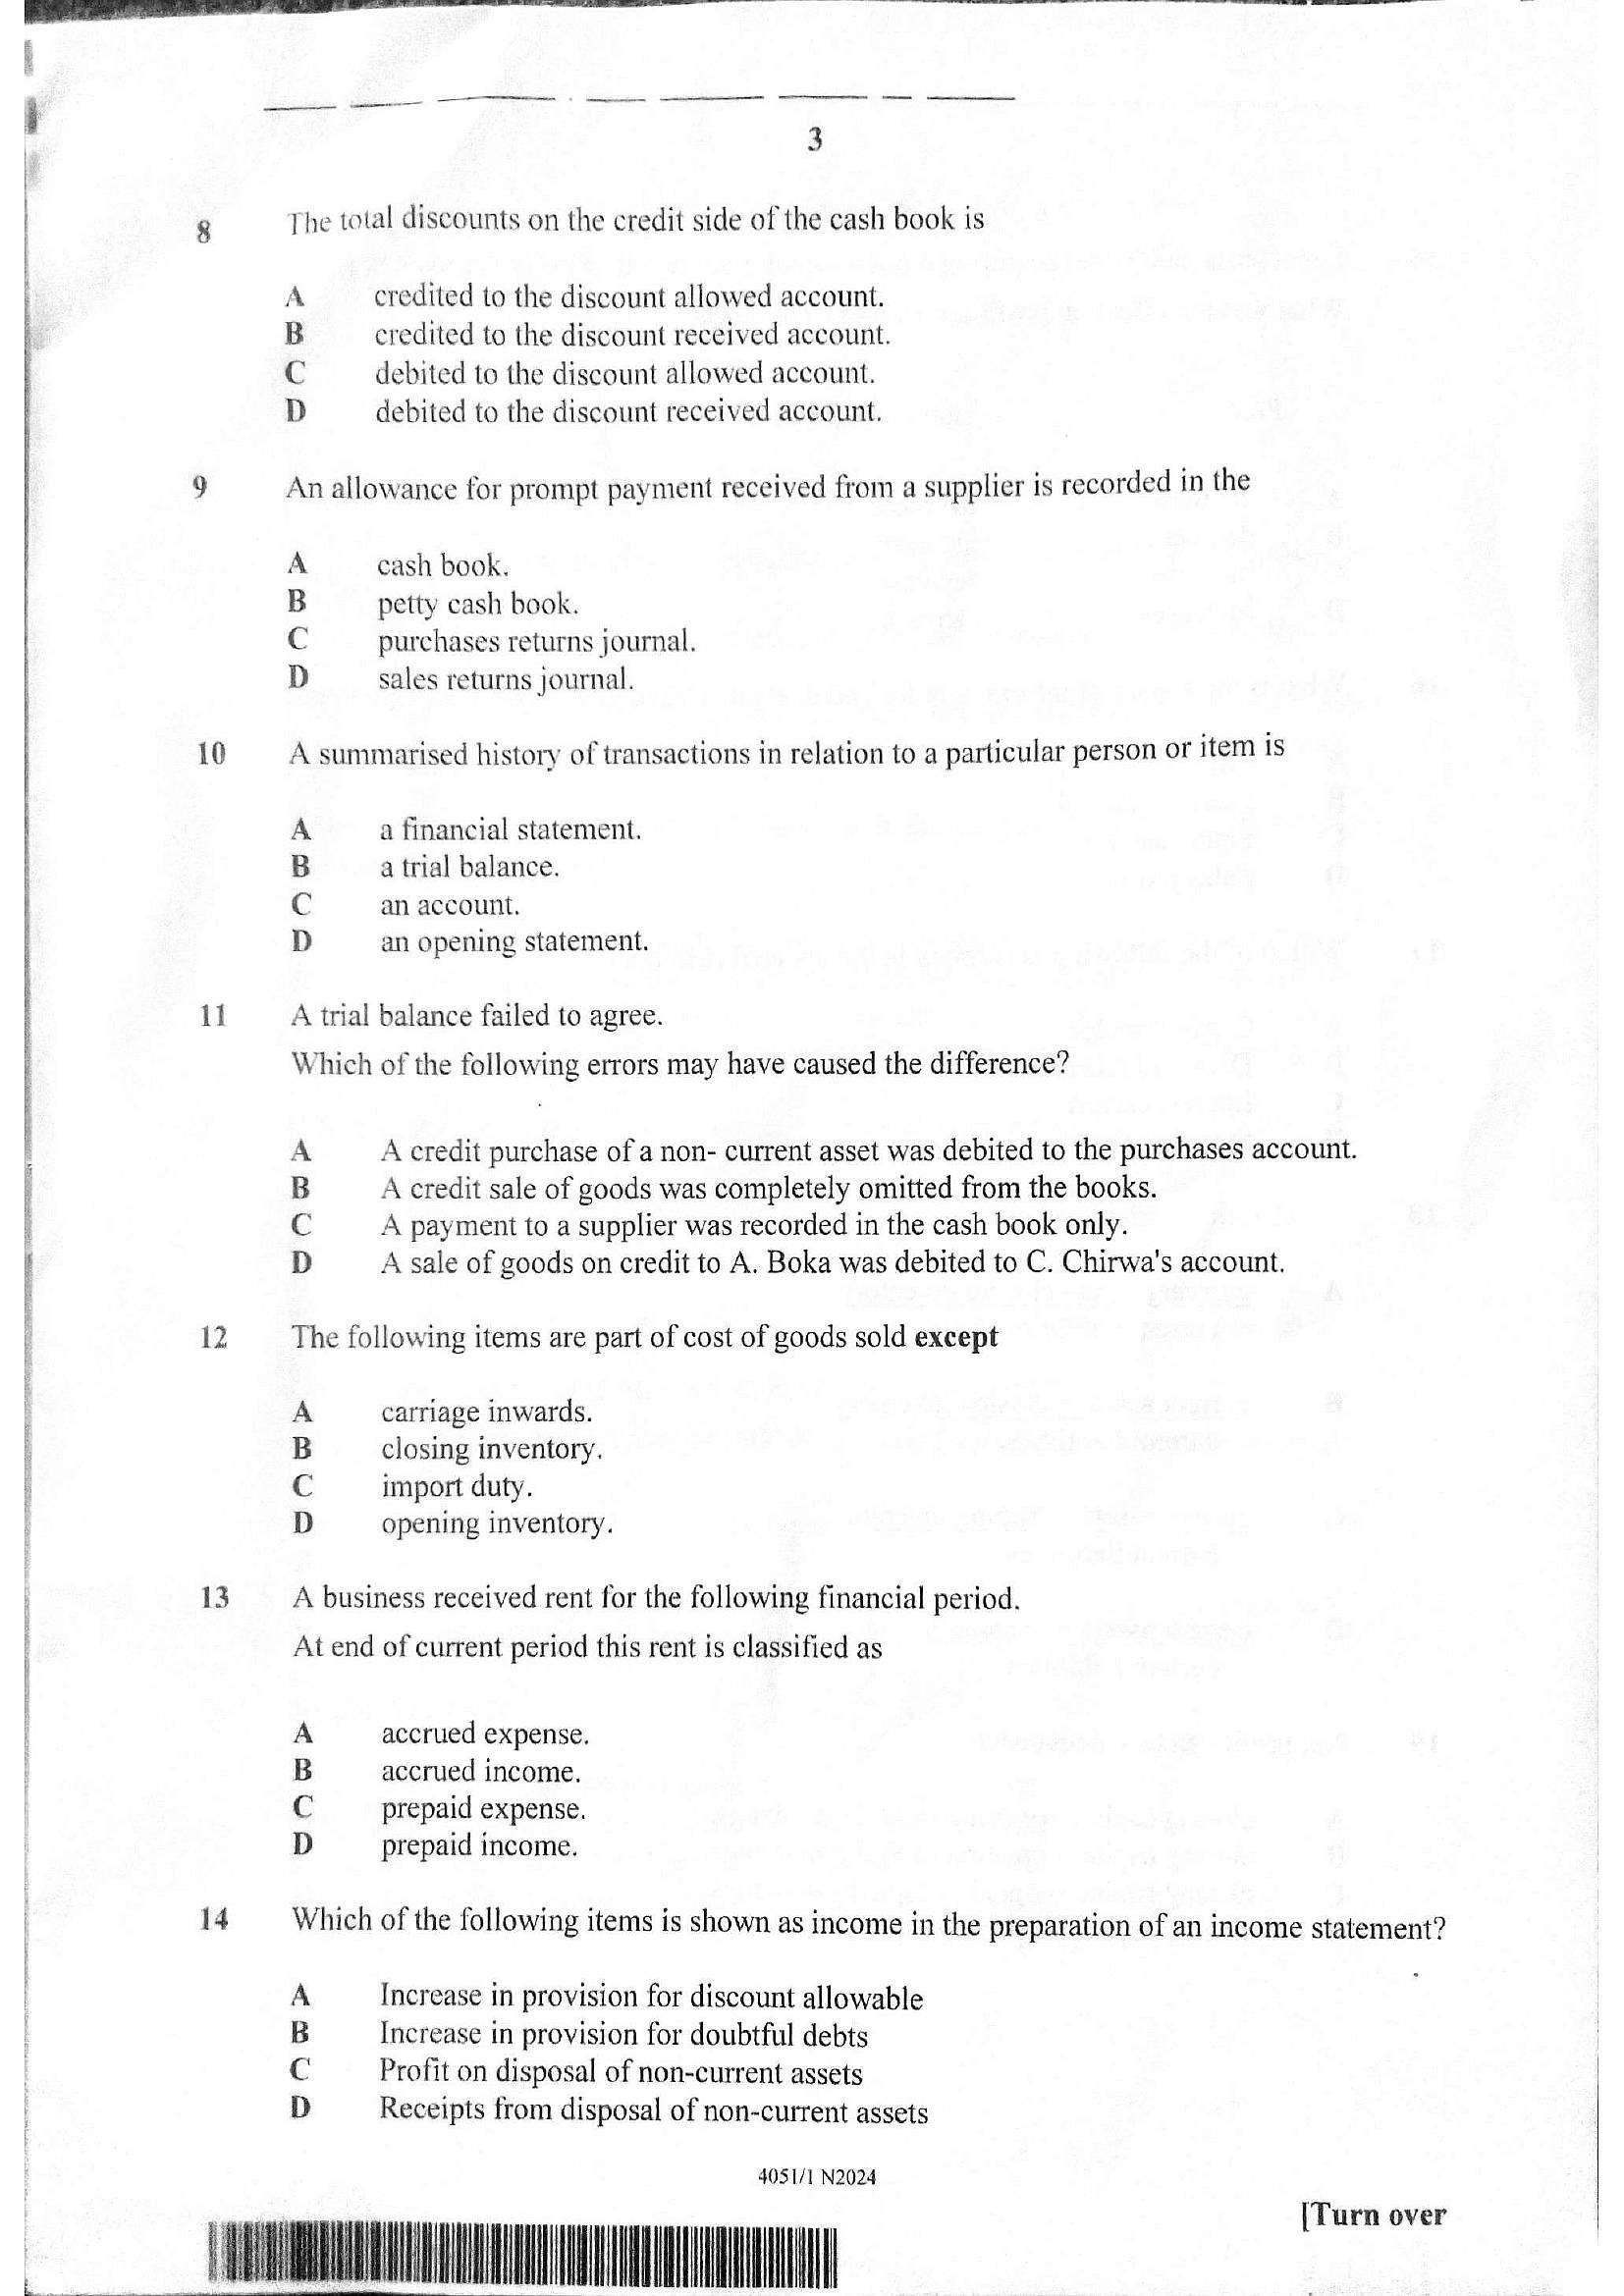
The total discounts on the credit side of the cash book is
credited to the discount allowed account.
credited to the discount received account.
debited to the discount allowed account.
debited to the discount received account.
— ap - -g
An allowance for prompt payment received from a supplier is recorded in the
A cash book.
B petty cash book.
Cc purchases returns journal.
D sales returns journal.
A summarised history of transactions in relation to a particular person or item 1s
a financial statement.
a trial balance.
an account.
an opening statement.
SOnmS
A trial balance failed to agree.
Which of the following errors may have caused the difference?
A credit purchase of a non- current asset was debited to the purchases account.
A credit sale of goods was completely omitted from the books.
A payment to a supplier was recorded in the cash book only.
A sale of goods on credit to A. Boka was debited to C. Chirwa’s account.
SOnmS
The following items are part of cost of goods sold except
carriage inwards.
closing inventory.
import duty.
opening inventory.
San,
A business received rent for the following financial period.
At end of current period this rent is classified as
accrued expense.
accrued income.
prepaid expense.
prepaid income.
SanS
Which of the following items is shown as income in the preparation of an income statement?
Increase in provision for discount allowable
Increase in provision for doubtful debts
Profit on disposal of non-current assets
Receipts from disposal of non-current assets
San S
4051/1 N2024
[Turn over
---
Page 4
Extracted Text
1617
18
(ain © Zimsec 2024
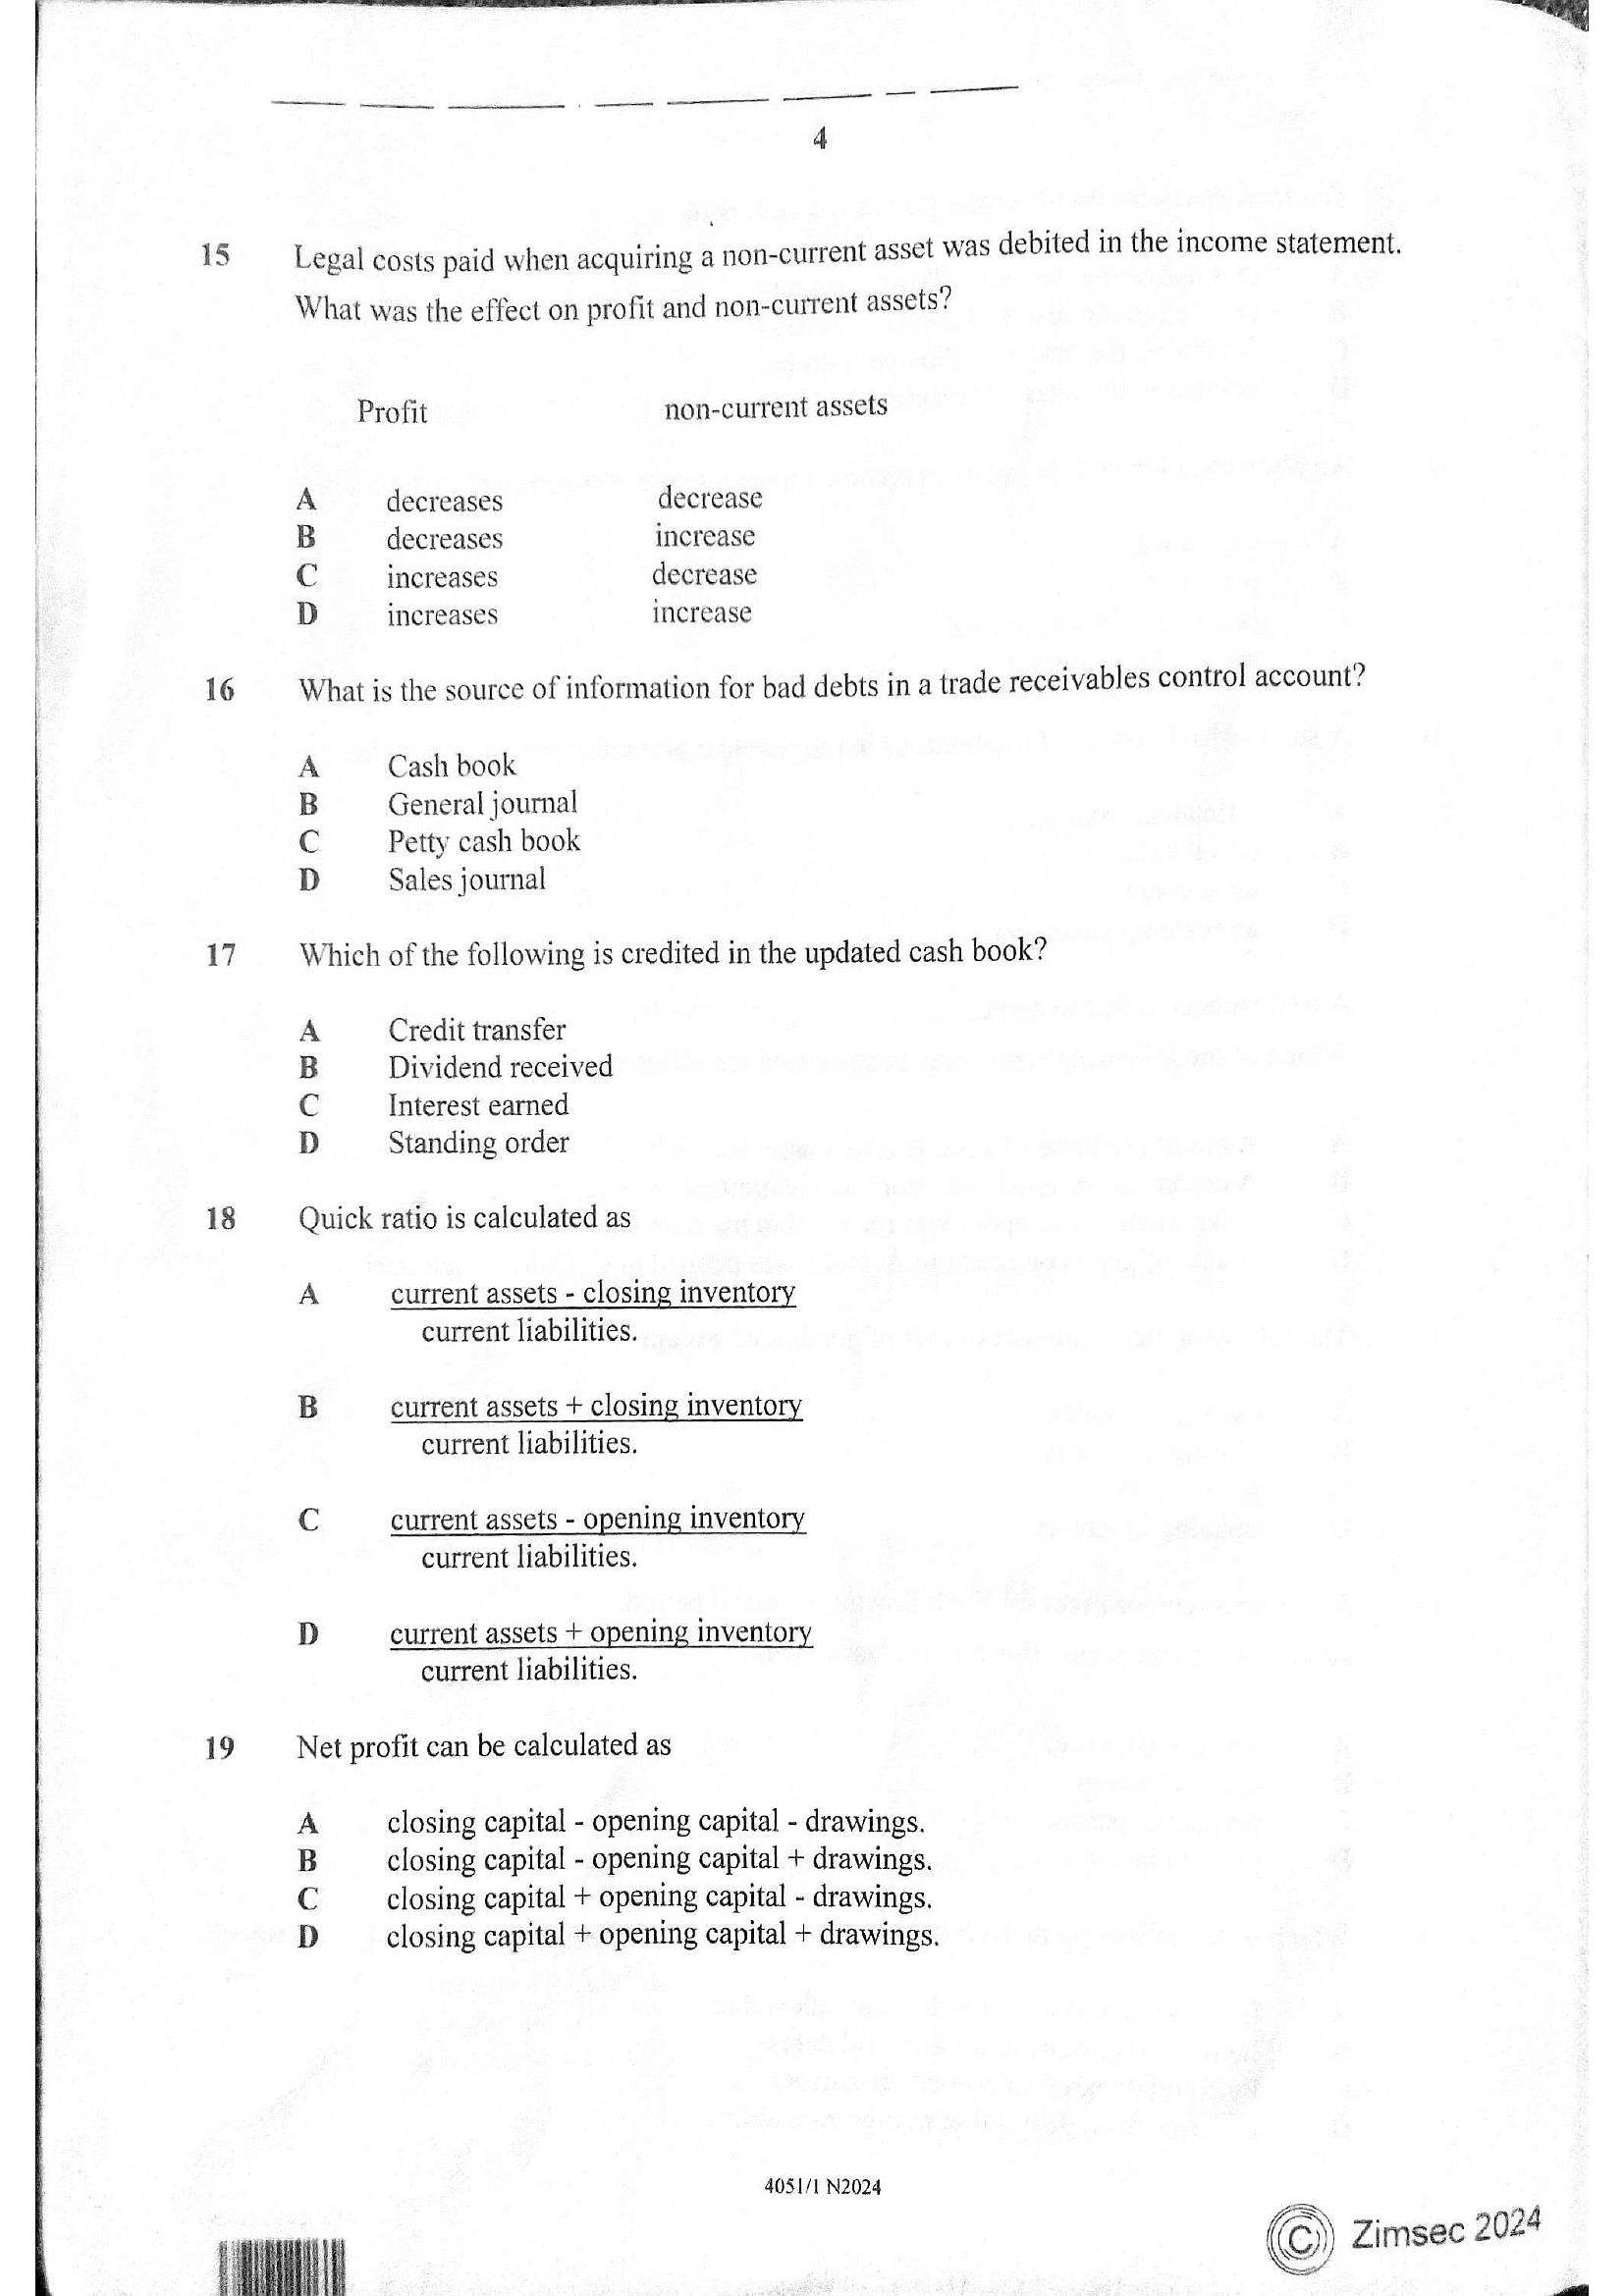
Legal costs paid when acquiring a non-current asset was debited in the income statement.
What was the effect on profit and non-current assets?
Profit non-current assets
A decreases decrease
B decreases increase
Cc increases decrease
D increases increase
What is the source of information for bad debts in a trade receivables control account?
Cash book
General journal
Petty cash book
Sales journal
SOnwPy
Which of the following is credited in the updated cash book?
Credit transfer
Dividend received
Interest earned
Standing order
SOW pe
Quick ratio is calculated as
A current assets - closing inventory
current liabilities.
B current assets + closing inventory
current liabilities.
c current assets - opening inventory
current liabilities.
D current assets + opening inventory
current liabilities.
Net profit can be calculated as
closing capital - opening capital - drawings.
closing capital - opening capital + drawings.
closing capital + opening capital - drawings.
closing capital + opening capital + drawings.
SOn >
4031/1 N2024
_—
---
Page 5
Extracted Text
2021
22
25
5
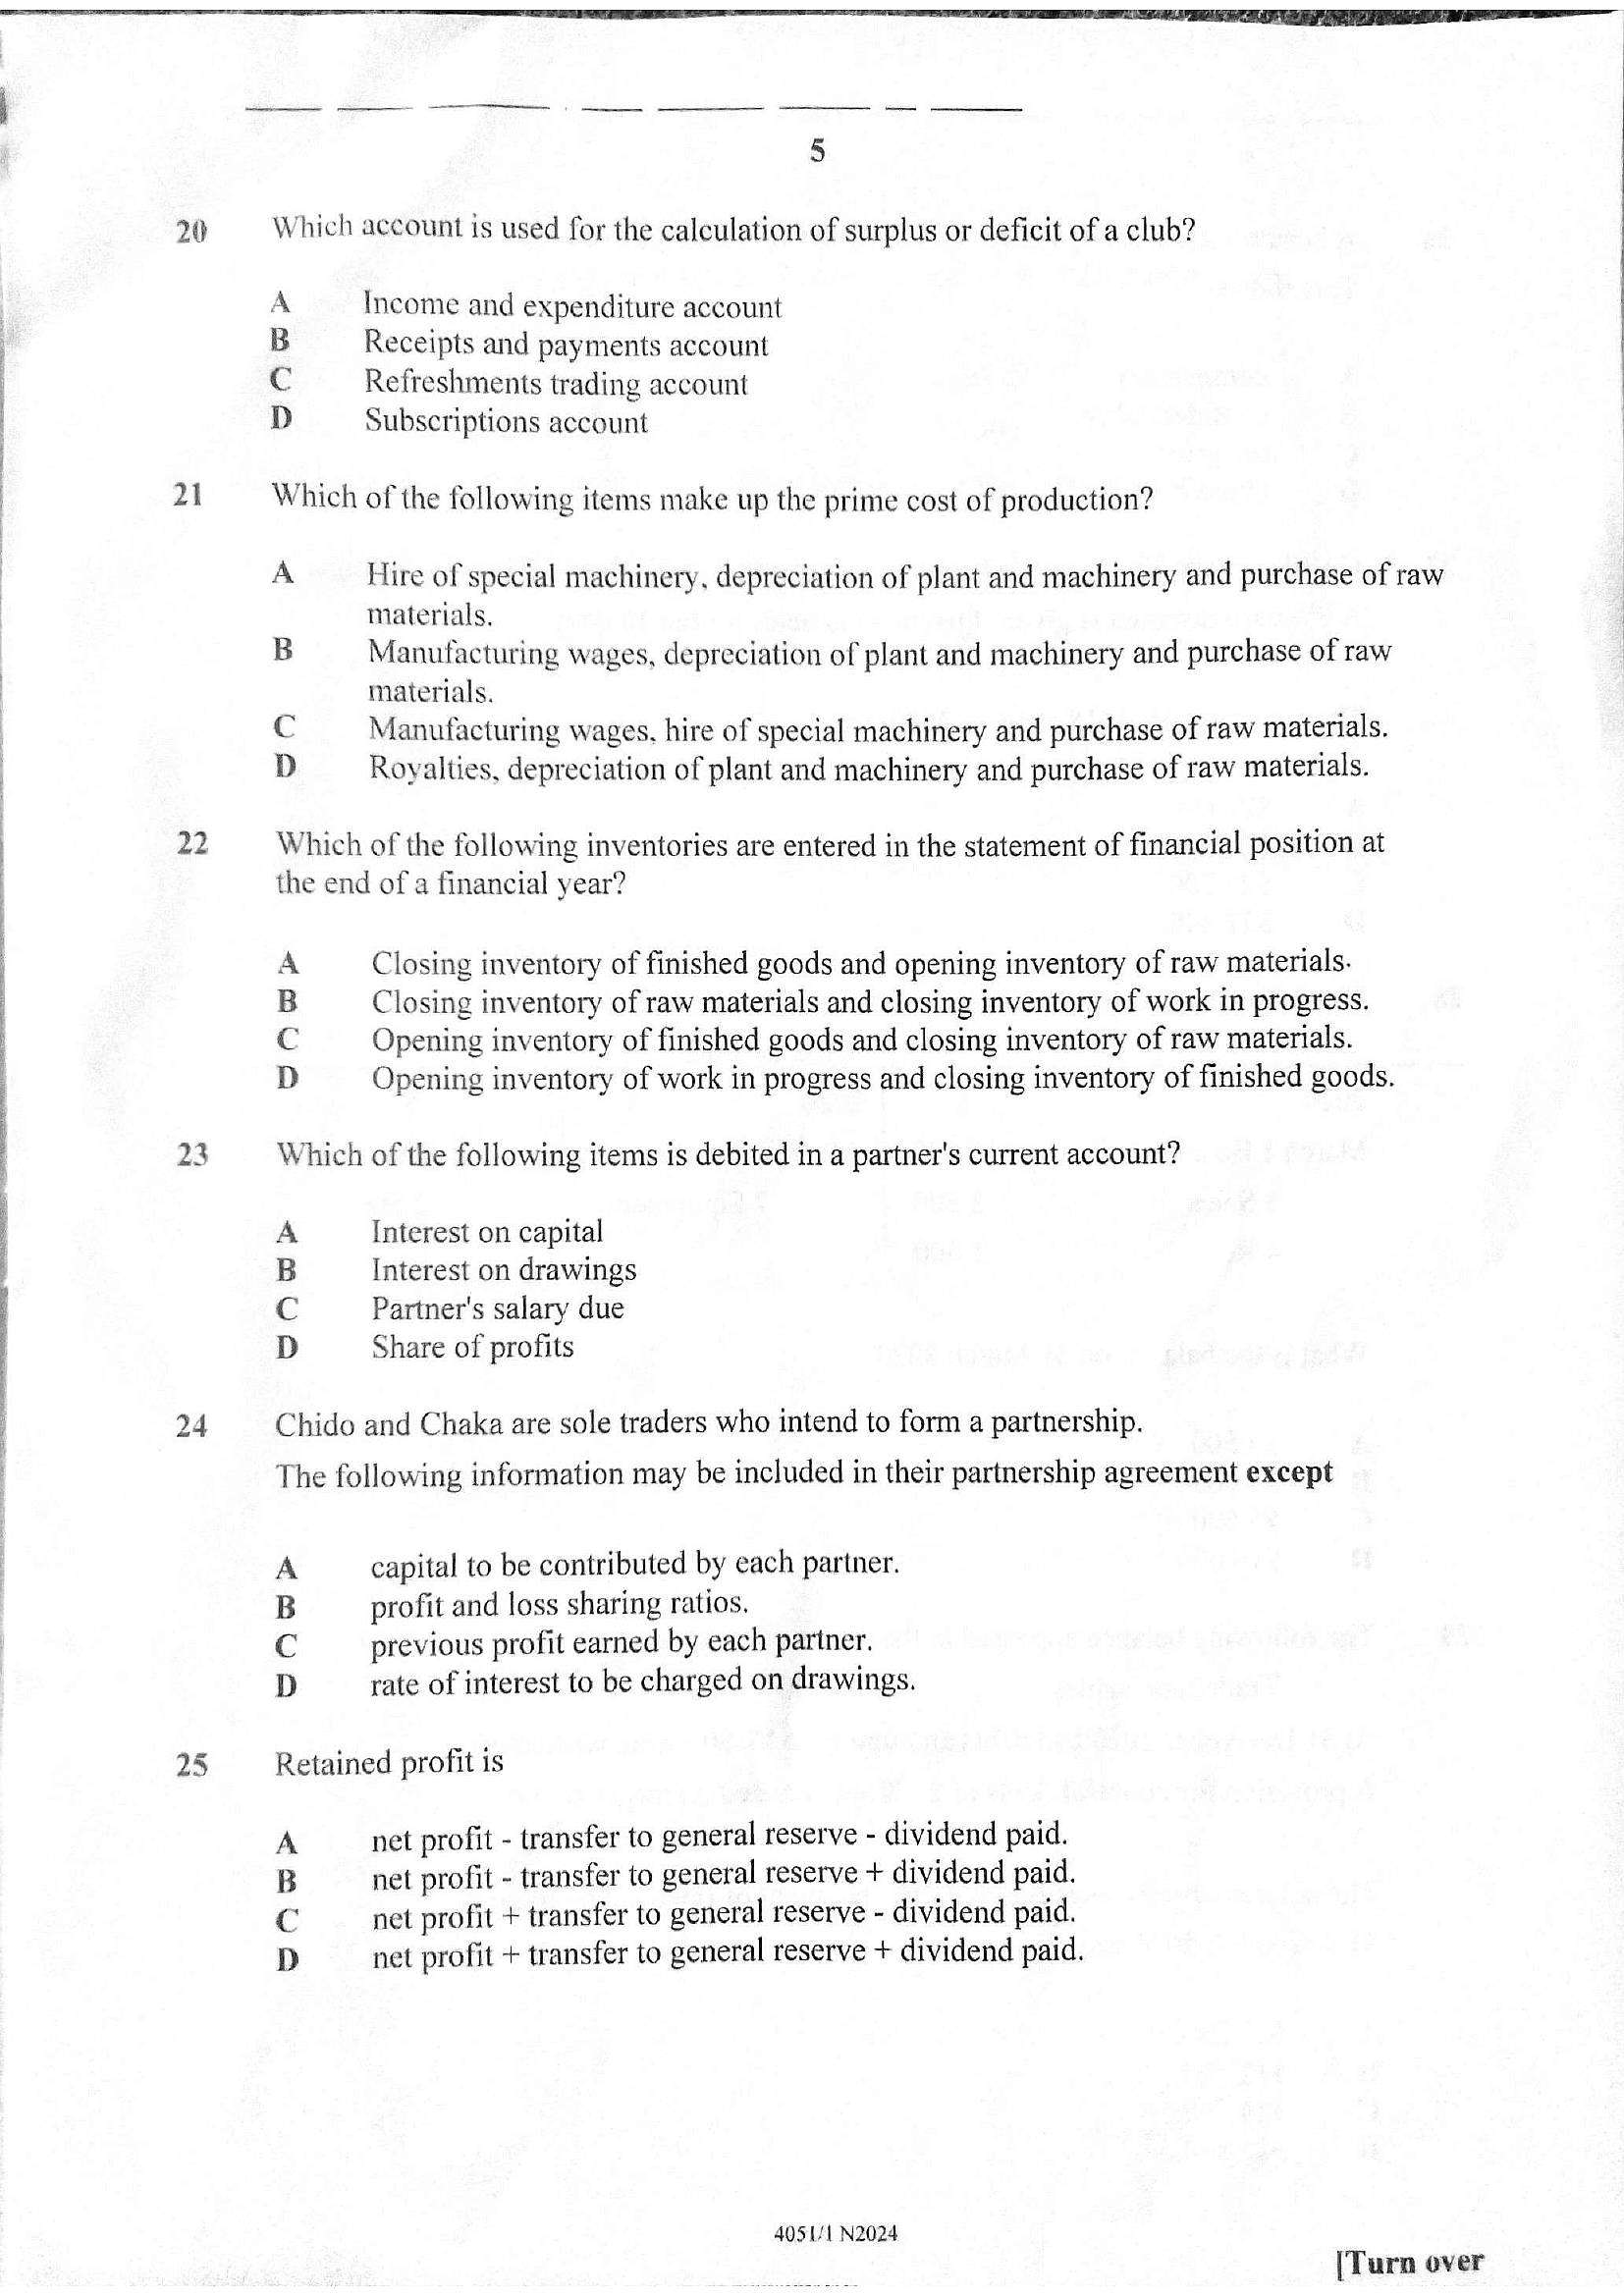
Which account is used for the calculation of surplus or deficit of a club?
Income and expenditure account
Receipts and payments account
Refreshments trading account
Subscriptions account
SanFr
Which of the following items make up the prime cost of production?
A Hire of special machinery, depreciation of plant and machinery and purchase of raw
materials.
B Manufacturing wages, depreciation of plant and machinery and purchase of raw
materials.
Cc Manufacturing wages. hire of special machinery and purchase of raw materials.
D Royalties, depreciation of plant and machinery and purchase of raw materials.
Which of the following inventories are entered in the statement of financial position at
the end of a financial year?
Closing inventory of finished goods and opening inventory of raw material
Opening inventory of finished goods and closing inventory of raw material.
SOS
Which of the following items is debited in a partner's current account?
Interest on capital
Interest on drawings
Partner's salary due
Share of profits
SaAwmP>F
Chido and Chaka are sole traders who intend to form a partnership.
The following information may be included in their partnership agreement except
capital to be contributed by each partner.
profit and loss sharing ratios.
previous profit earned by each partner.
rate of interest to be charged on drawings.
SOW >
Retained profit is
A net profit - transfer to general reserve - dividend paid.
B net profit - transfer to general reserve + dividend paid.
Cc net profit + transfer to general reserve - dividend paid.
D net profit + transfer to general reserve + dividend paid.
4051/1 N2024
S$:
Closing inventory of raw materials and closing inventory of work in progress.
S.
Opening inventory of work in progress and closing inventory of finished goods.
[Turn over
---
Page 6
Extracted Text
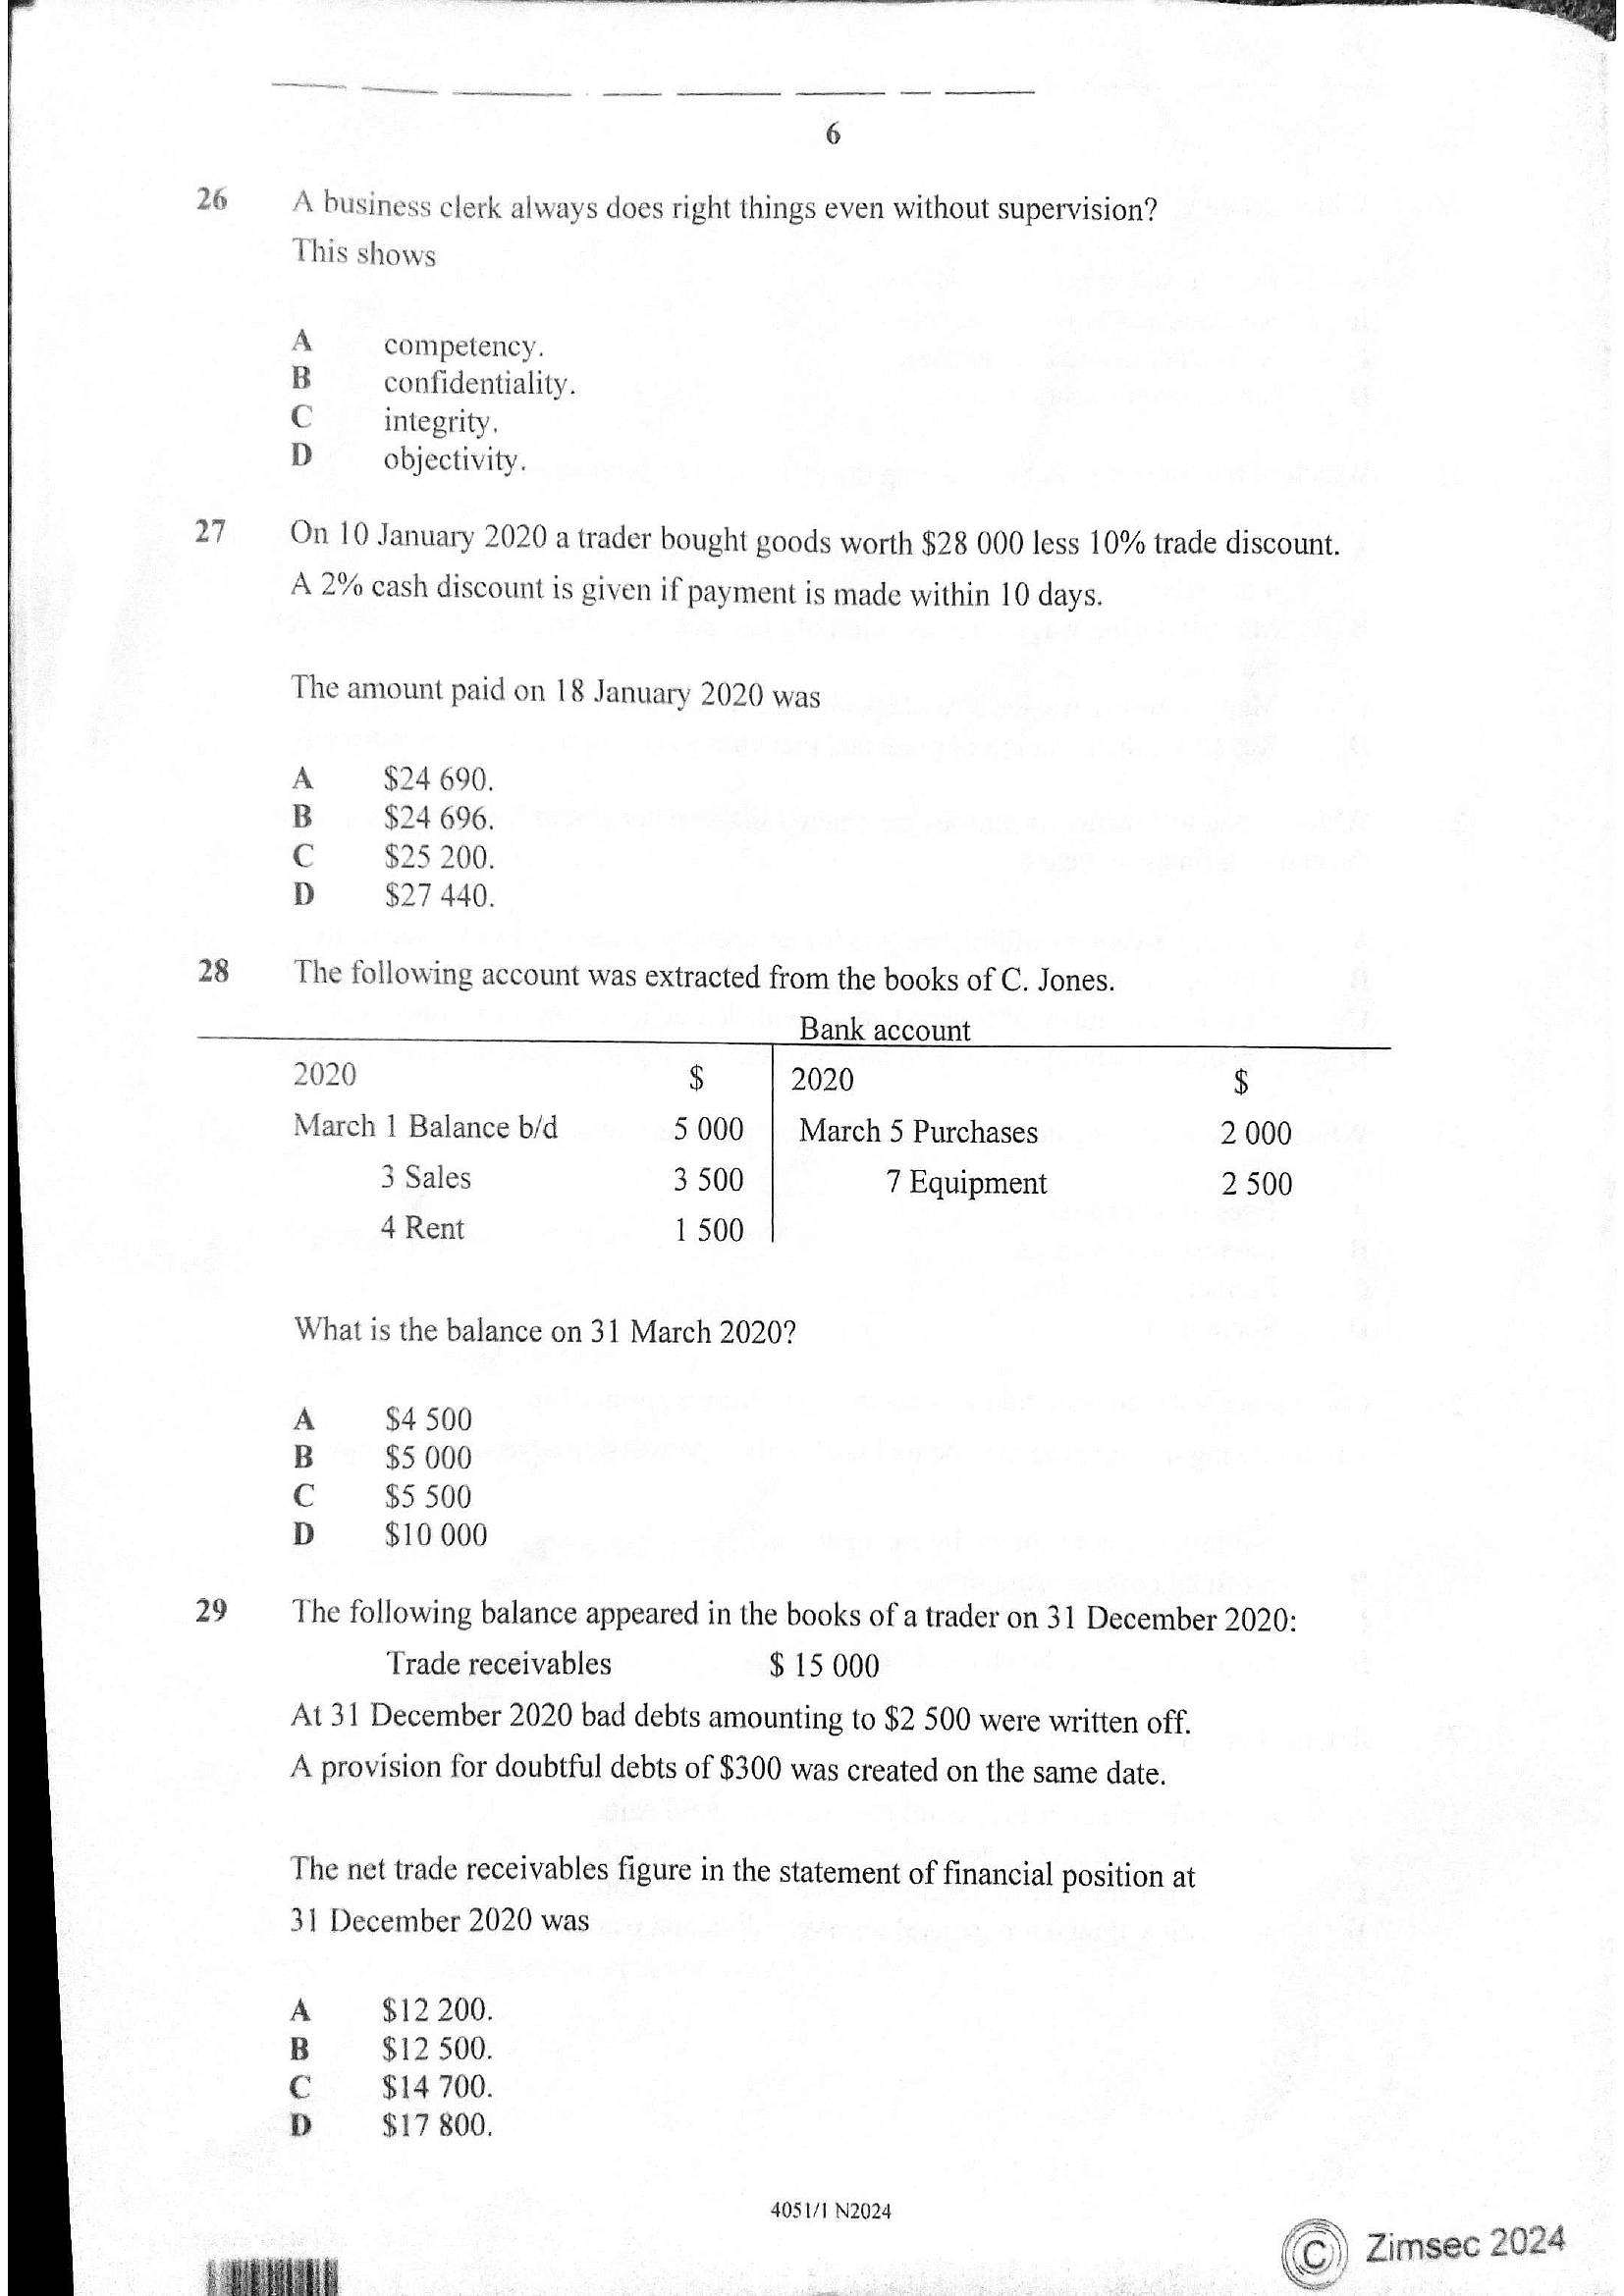
6 26 A business clerk always does right things even without supervision? This shows A competency. B confidentiality. Cc integrity, D objectivity. 27 On 10 January 2020 a trader bought goods worth $28 000 less 10% trade discount. A 2% cash discount is given if payment is made within 10 days. The amount paid on 18 January 2020 was A $24 690. B $24 696. Cc $25 200. D $27 440. 28 The following account was extracted from the books of C. Jones. Bank account 2020 $ 2020 $ March 1 Balance b/d 5.000 | March 5 Purchases 2 000 3 Sales 3 500 7 Equipment 2 500 4 Rent 1500 What is the balance on 31 March 2020? A $4 500 B $5 000 Cc $5 500 D $10 000 29 The following balance appeared in the books of a trader on 31 December 2020:pa
Trade receivables $ 15 000
At 31 December 2020 bad debts amounting to $2 500 were written off.
A provision for doubtful debts of $300 was created on the same date.
The net trade receivables figure in the statement of financial position at
31 December 2020 was
A $12 200.
B $12 500.
Cc $14 700.
D $17 800.
4051/1 N2024
---
Page 7
Extracted Text
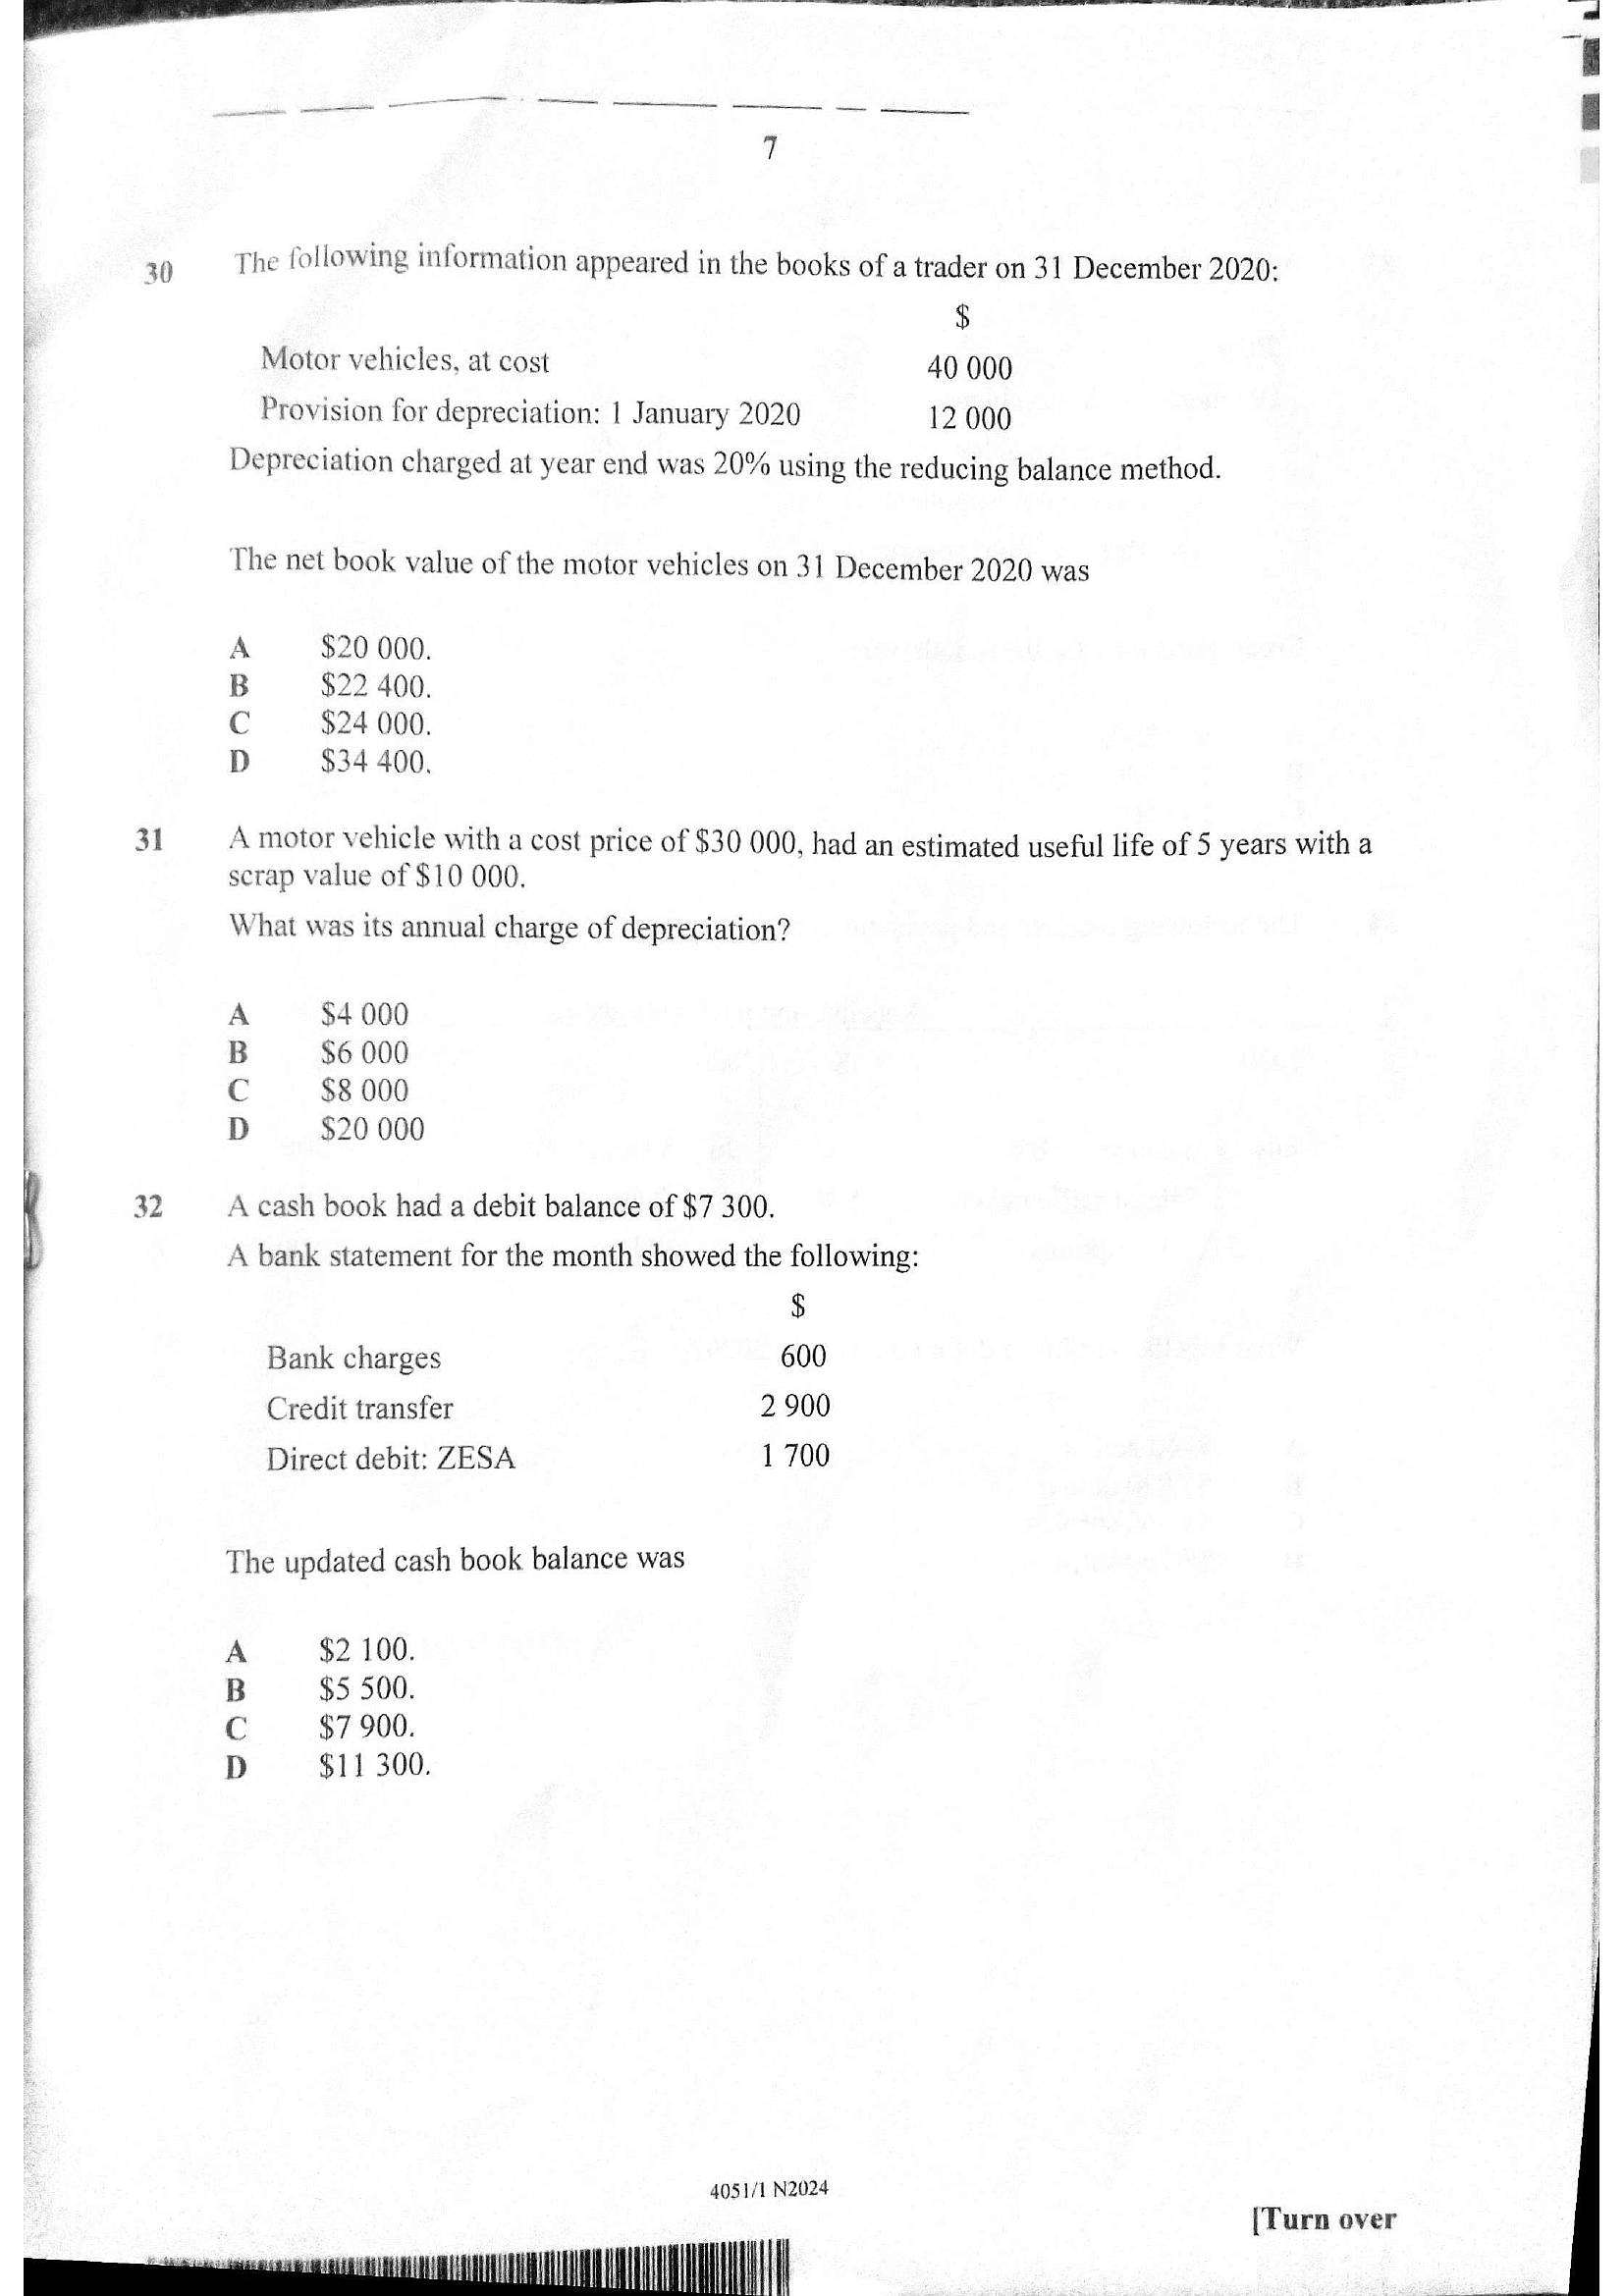
20) The following information appeared in the books of a trader on 31 December 2020:$
| Motor vehicles, at cost 40 000
Provision for depreciation: | January 2020 12 000
Depreciation charged at year end was 20% using the reducing balance method.
The net book value of the motor vehicles on 31 December 2020 was
A $20 000.
B $22 400.
Cc $24 000.
D $34 400,
31 A motor vehicle with a cost price of $30 000, had an estimated useful life of 5 years with a
scrap value of $10 000.
What was its annual charge of depreciation?
A $4000
B $6 000
C $8000
D —-$20.000 |
32 A cash book had a debit balance of $7 300.
A bank statement for the month showed the following:
$ |
Bank charges 600
Credit transfer 2 900 |
Direct debit: ZESA 1 700
The updated cash book balance was
|
|
A $2 100. |
B $5 500. |
Cc $7 900.
D $11 300. |
|
4051/1 N2024
[Turn over
---
Page 8
Extracted Text
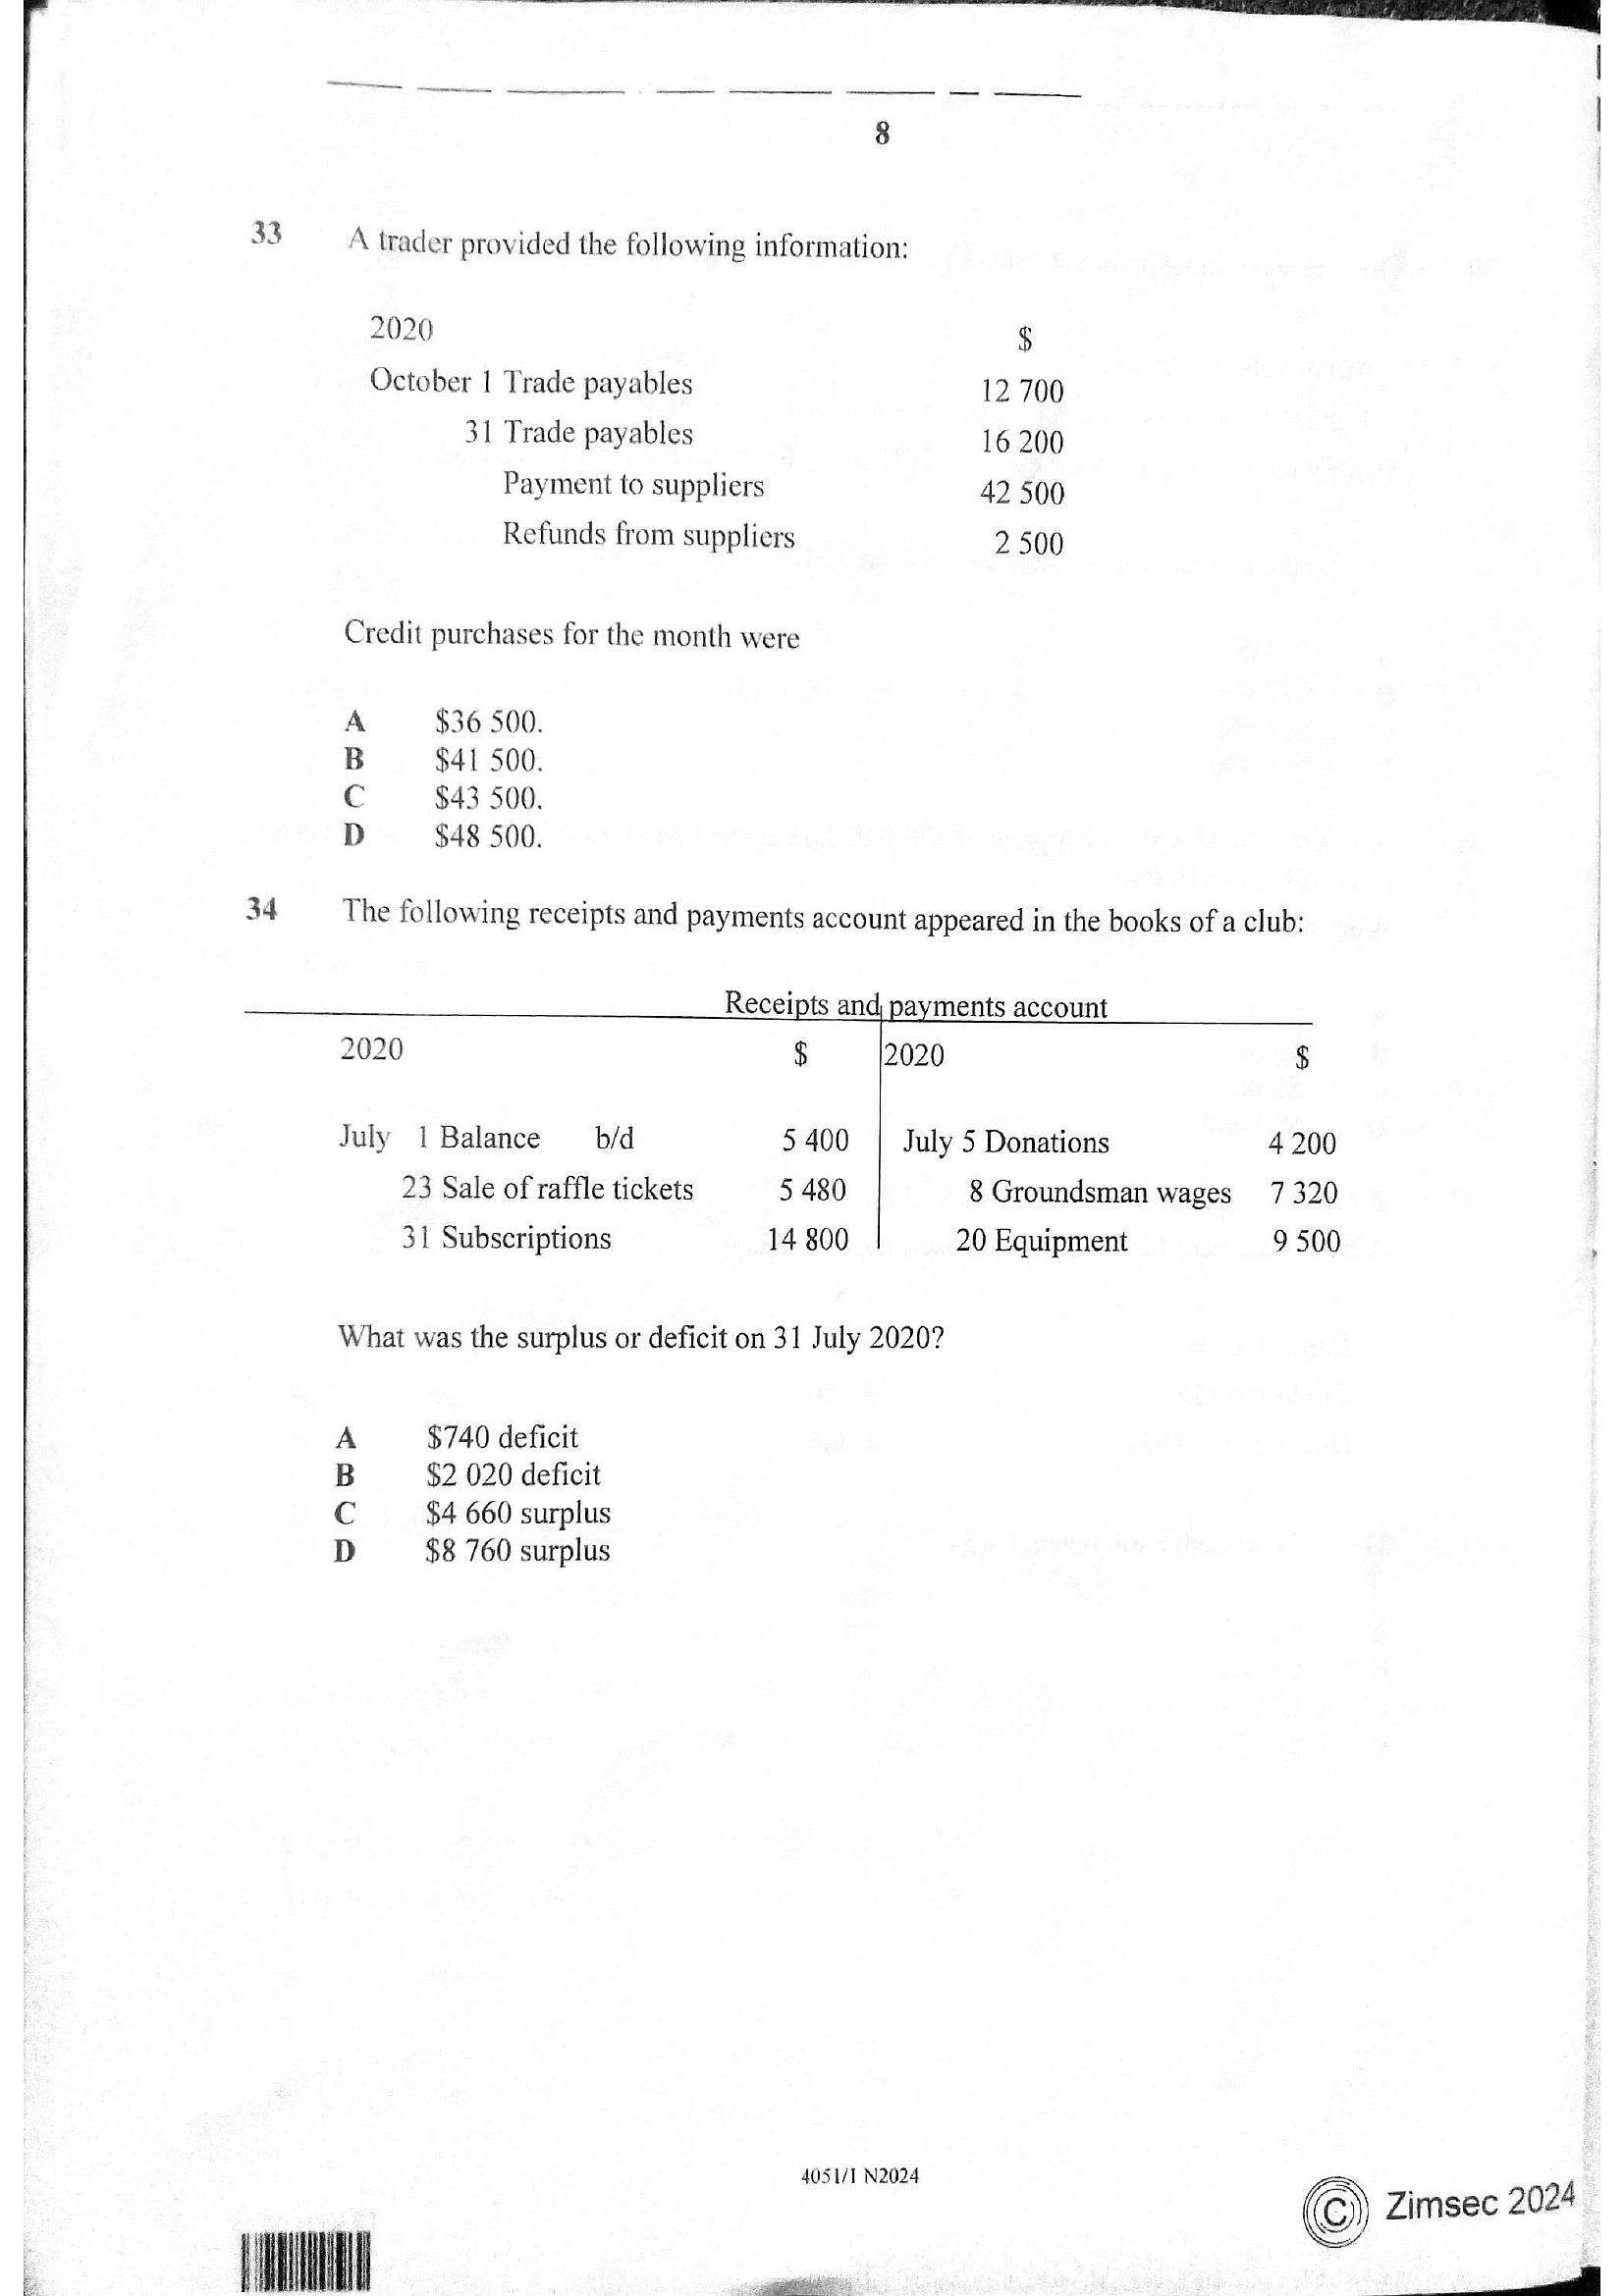
33A trader provided the following information:
2020 $
October 1 Trade payables 12 700
31 Trade payables 16 200
Payment to suppliers 42 500
Refunds from suppliers 2 500
Credit purchases for the month were
A $36 500.
B $41 500.
Cc $43 500.
D $48 500.
The following receipts and payments account appeared in the books of a club:
Receipts and payments account
2020 $ 2020 $
July 1 Balance b/d 5400 | July 5 Donations 4200
23 Sale of raffle tickets 5 480 8 Groundsman wages 7 320
31 Subscriptions 14 800 20 Equipment 9 500
What was the surplus or deficit on 31 July 2020?
A $740 deficit
B $2 020 deficit
Cc $4 660 surplus
D $8 760 surplus
4051/1 N2024
©) Zimsec 2024
eee |
---
Page 9
Extracted Text
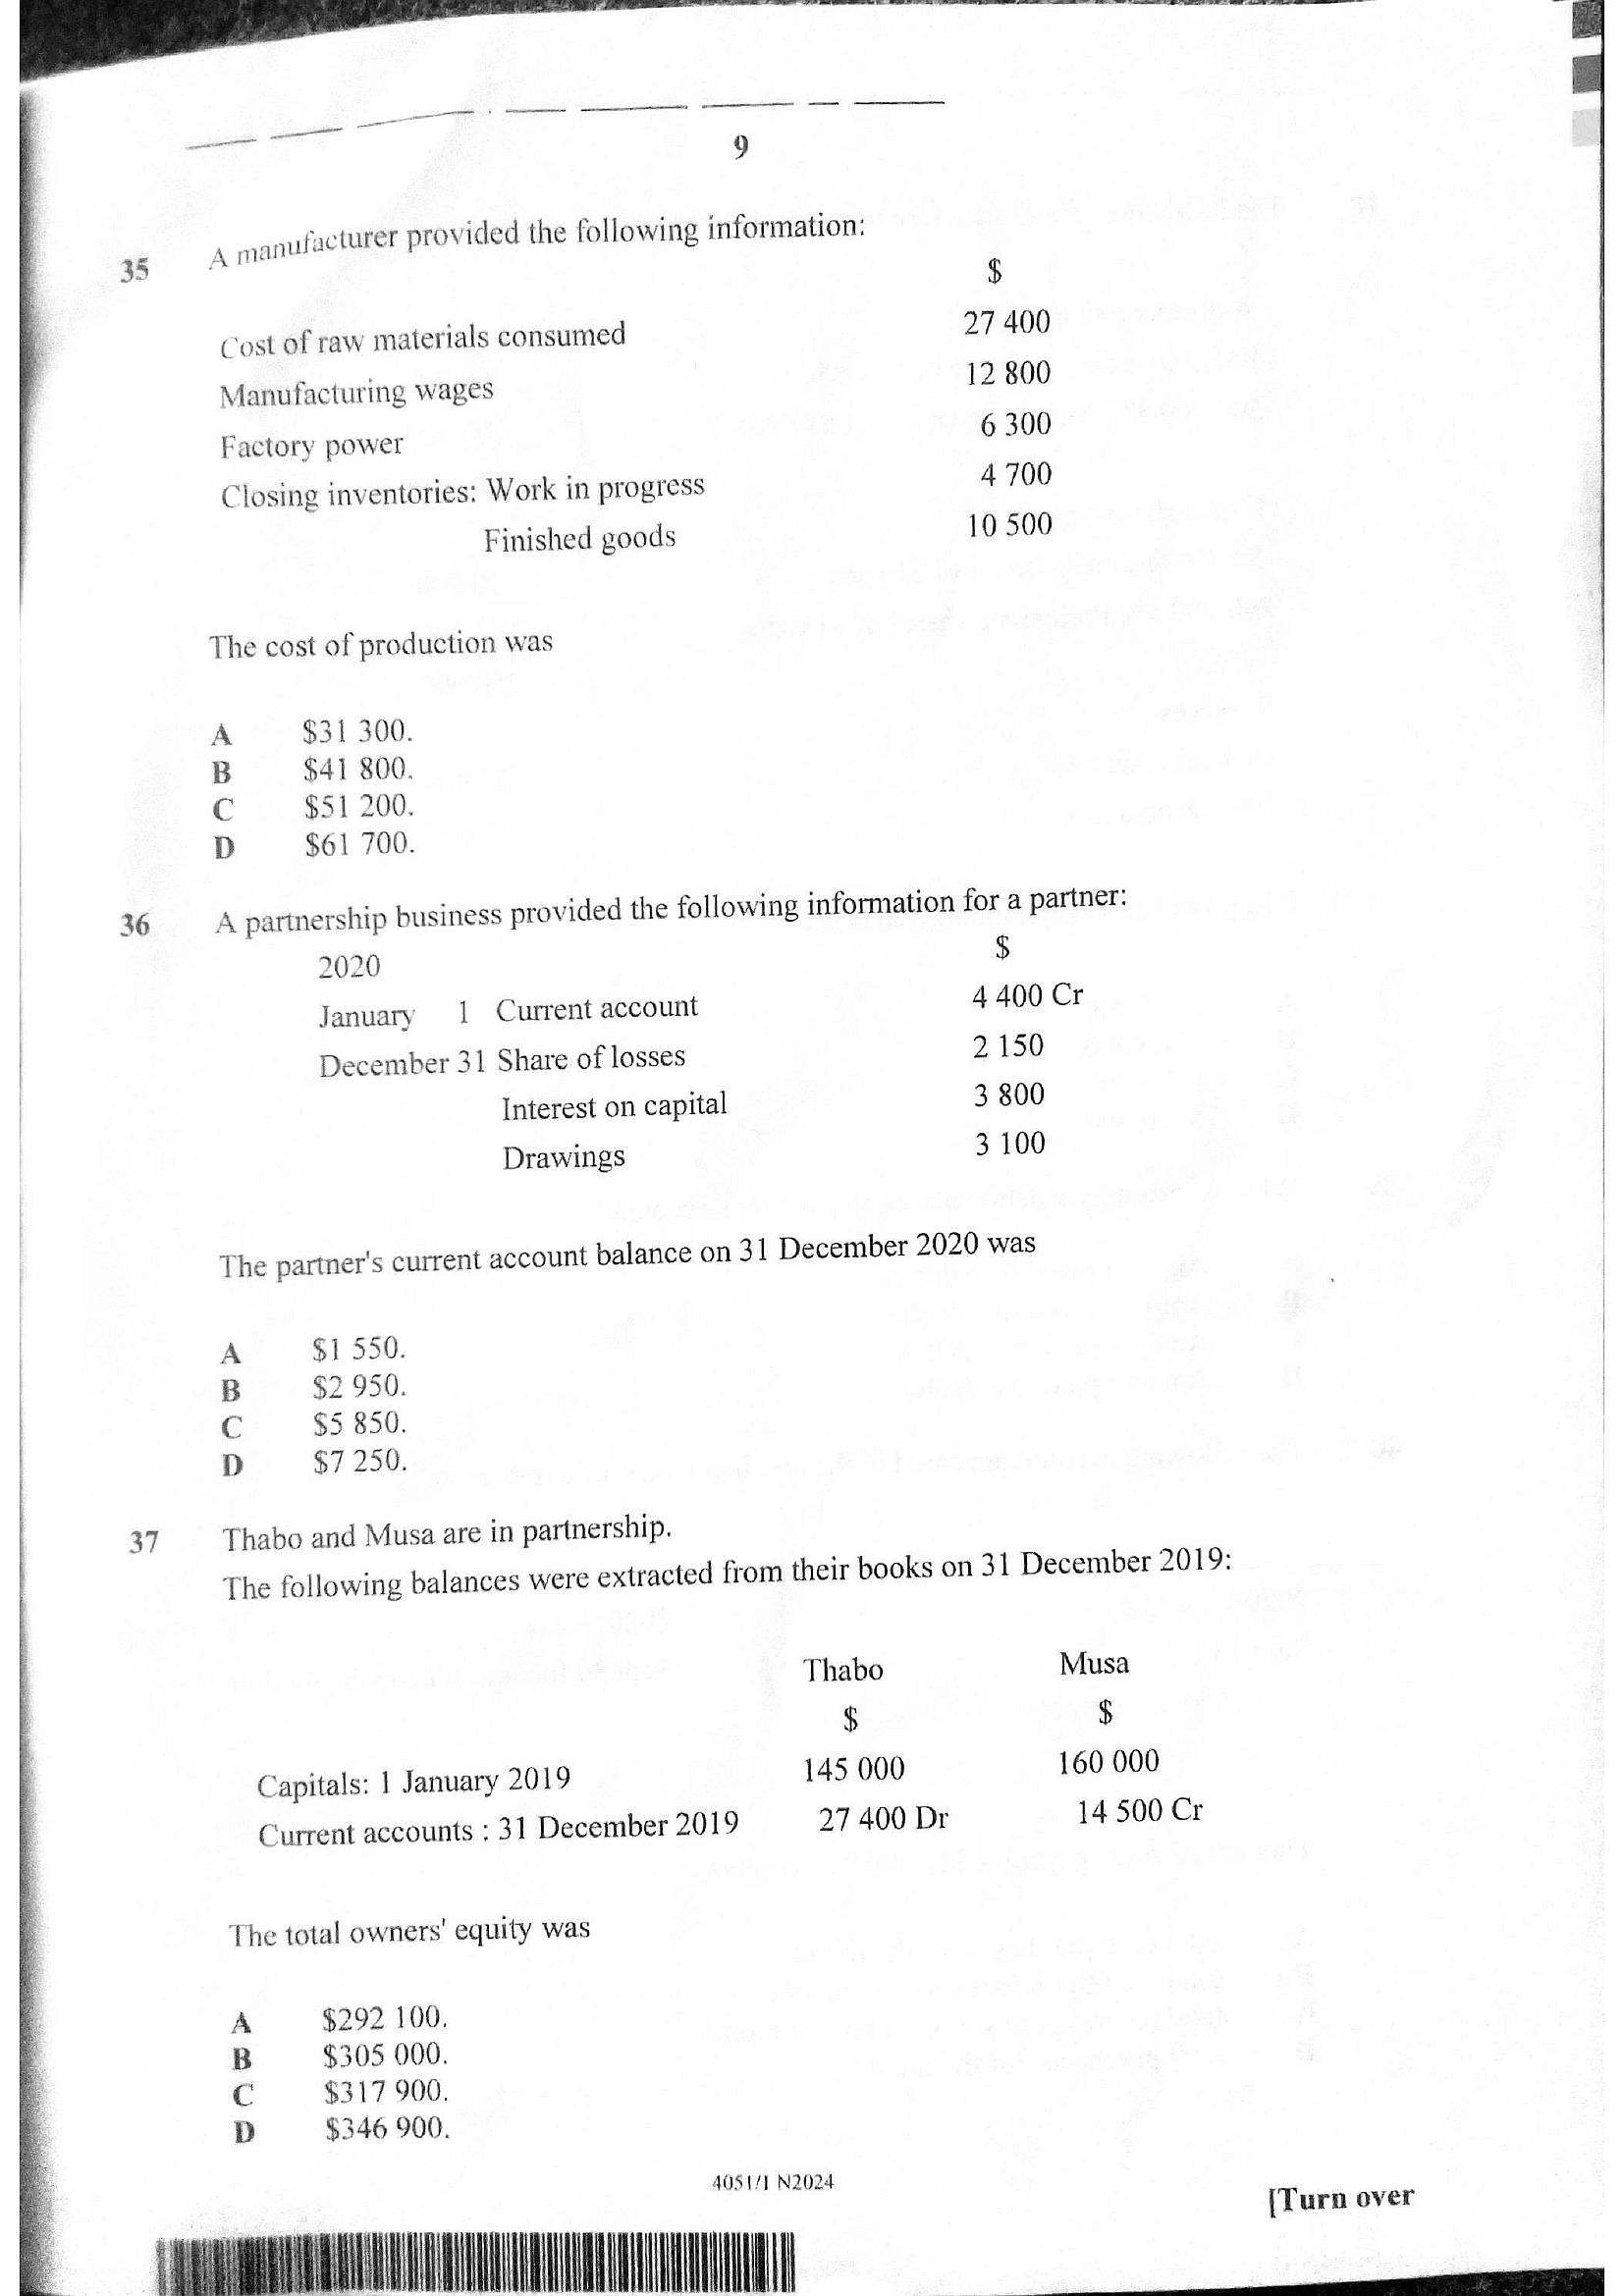
poem 93 ~#2OA manufacturer provided the following information.
$
Cost of raw materials consumed 27 400
Manufacturing wages 12 800
Factory power 6 300
Closing inventories: Work in progress 4700
10 500
Finished goods
The cost of production was
A $31 300.
B $41 800.
C $51 200.
D $61 700.
36 A partnership business provided the following information for a partner:
2020 $
| January 1 Current account 4 400 Cr
| December 31 Share of losses 2 150
Interest on capital 3 800
Drawings 3 100
The partner's current account balance on 31 December 2020 was
A $1550.
B $2950. |
Cc $5850. |
D $7250.
37 Thabo and Musa are in partnership.
The following balances were extracted from their books on 31 December 2019:
Thabo Musa
$ $
Capitals: | January 2019 145 000 160 000
Current accounts : 31 December 2019 27 400 Dr 14 500 Cr
The total owners’ equity was
A $292 100,
B $305 000.
c $317 900.
D $346 900.
4051/1 N2024
[Turn over
NAVAN AALAAUA a
---
Page 10
Extracted Text
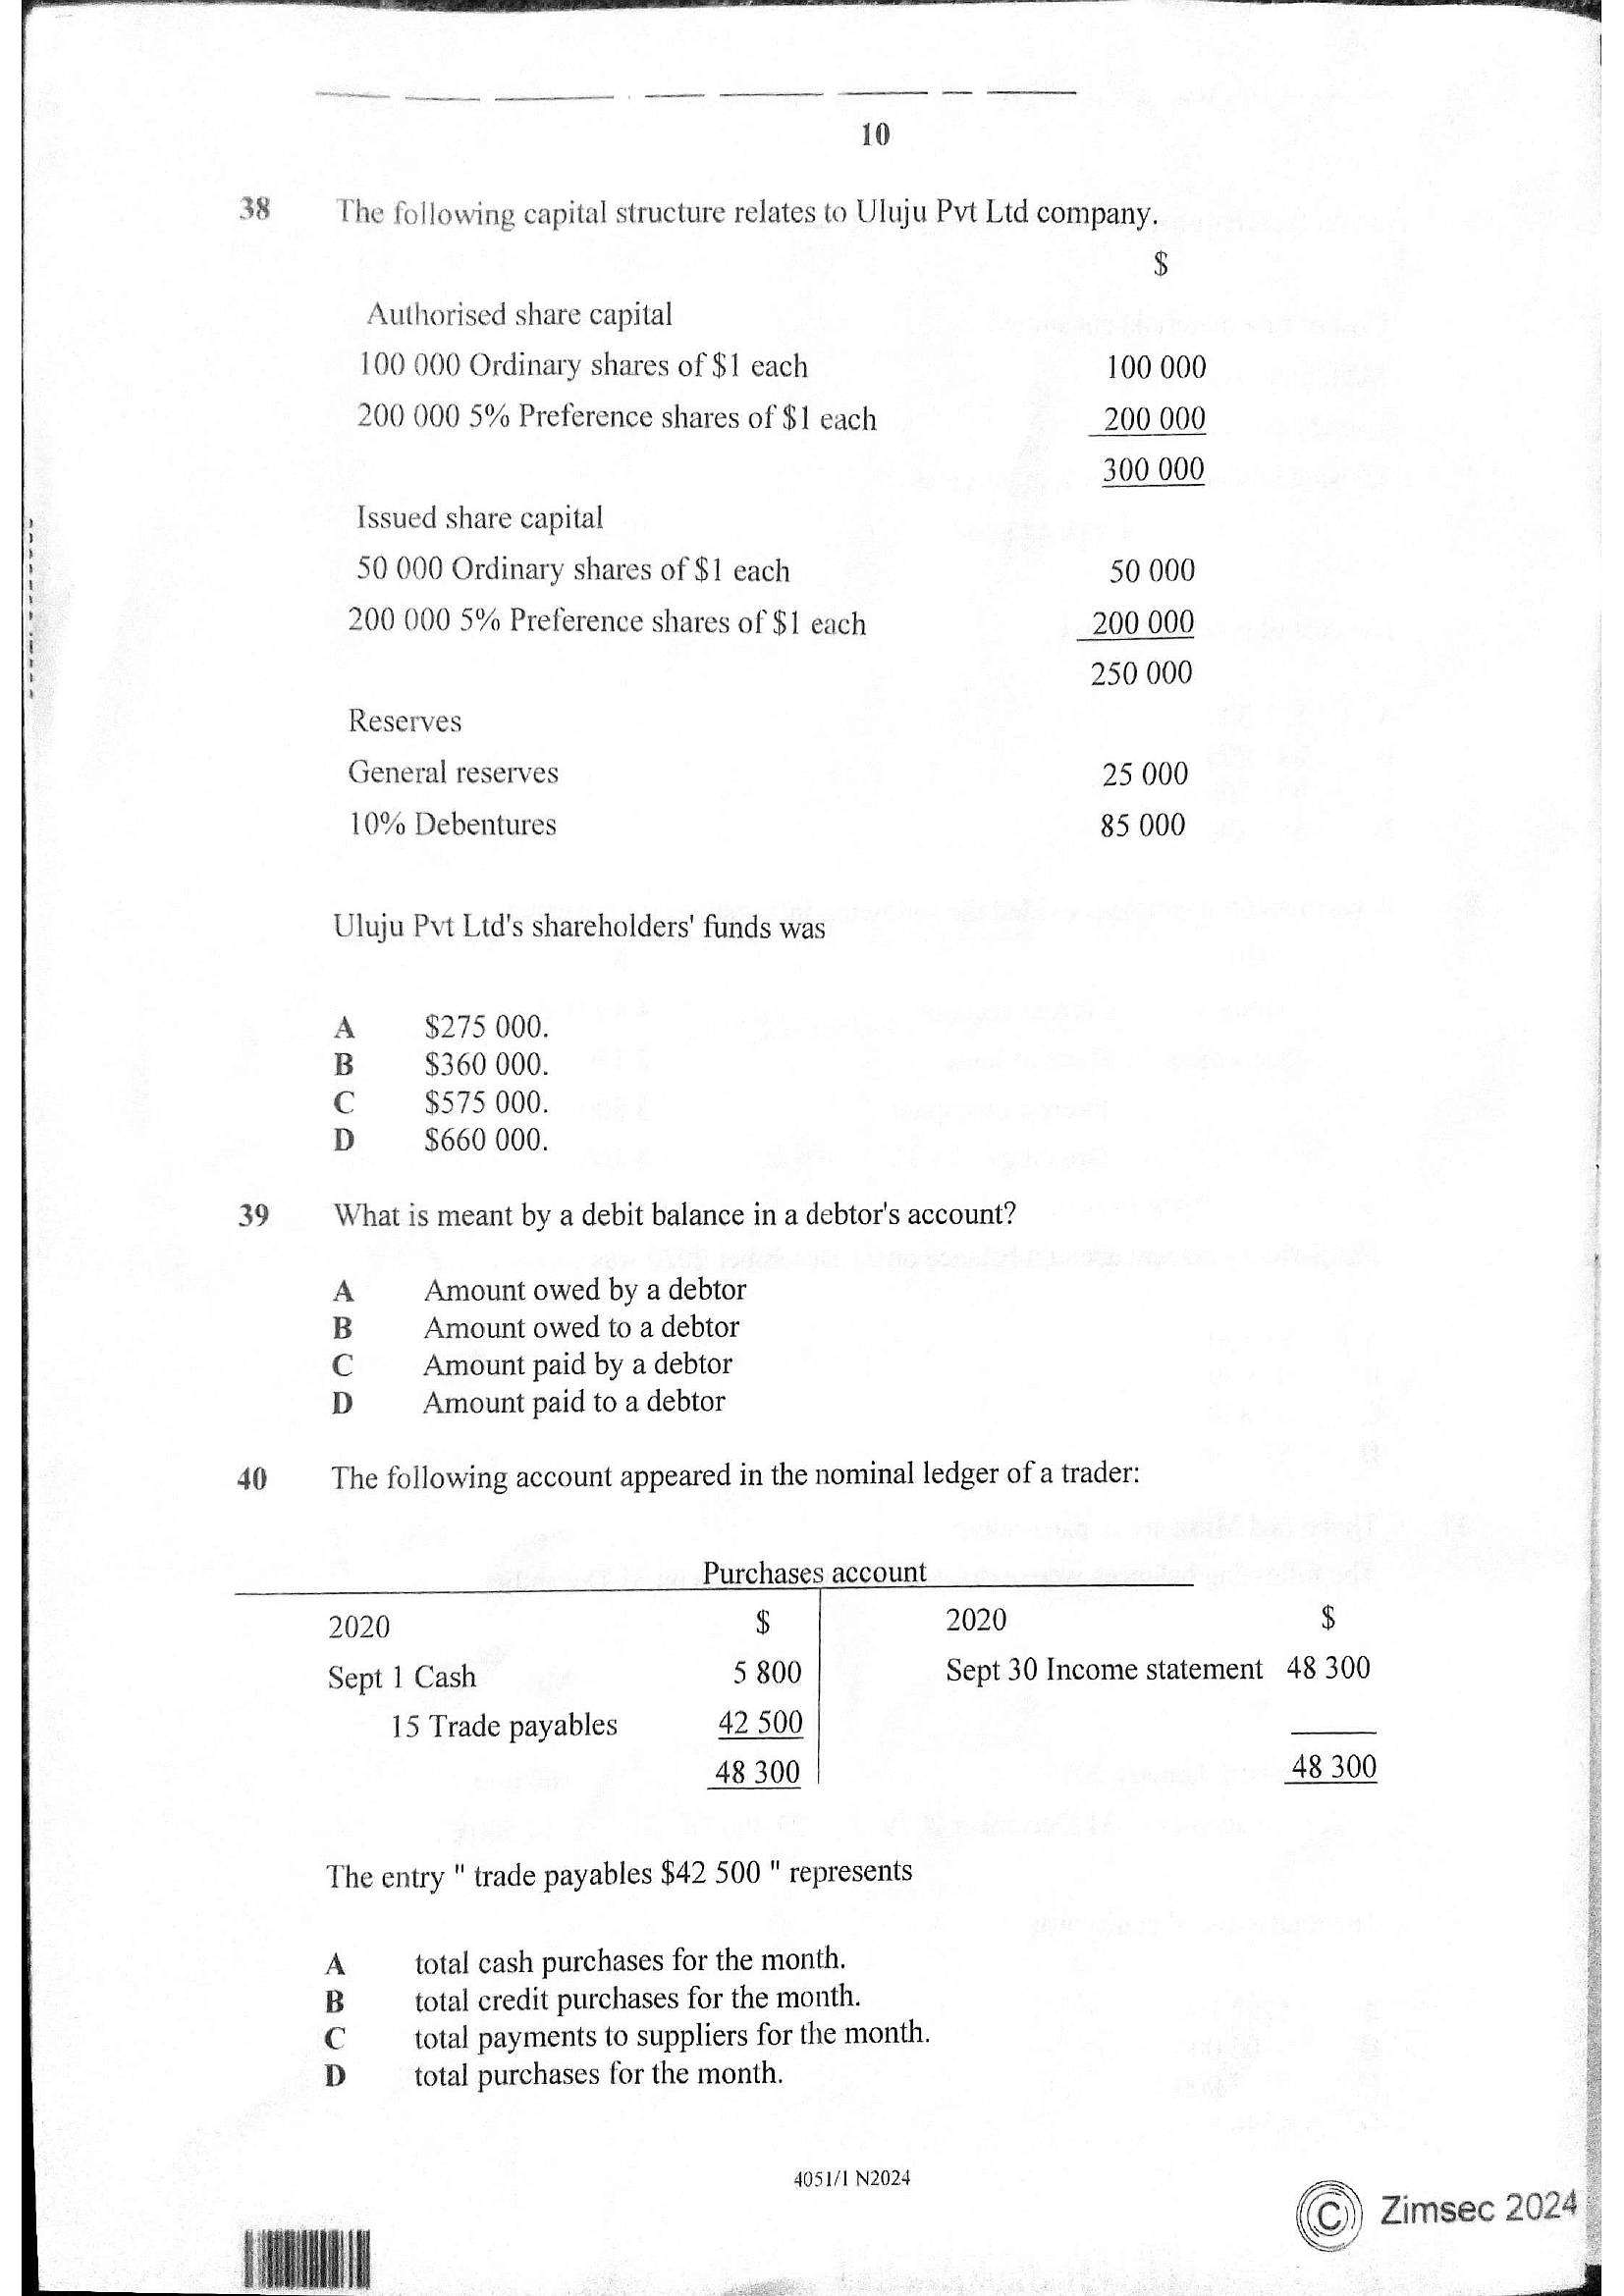
10 38 Che following capital structure relates to Uluju Pvt Ltd company. $Authorised share capital
100 000 Ordinary shares of $1 each 100 000
200 000 5% Preference shares of $1 each 200 000
300.000
Issued share capital
50 000 Ordinary shares of $1 each 50 000
200 000 5% Preference shares of $1 each 200 000
250 000
Reserves
General reserves 25 000
10% Debentures 85 000
Uluju Pvt Ltd's shareholders' funds was
A $275 000.
B $360 000.
Cc $575 000.
D $660 000.
39 What is meant by a debit balance in a debtor's account?
A Amount owed by a debtor
B Amount owed to a debtor
Cc Amount paid by a debtor
D Amount paid to a debtor
40 The following account appeared in the nominal ledger of a trader:
Purchases account
2020 $ 2020
Sept 1 Cash 5 800
15 Trade payables 42 500
A8 300
The entry " trade payables $42 500 " represents
total cash purchases for the month.
total credit purchases for the month.
total payments to suppliers for the month.
total purchases for the month.
4051/1 N2024
Sept 30 Income statement 48 300
---
Struggling with the concepts in this paper?
Revise syllabus notes, key exam points, and interactive practice questions for Business Accounts: